Non Dispersive Infrared Market (2026 - 2035)

Non Dispersive Infrared Market Size, Share and Research Report By Product Type (Fixed/Wall-Mount Modules, Smart and Connected Sensors, Portable/Handheld Analyzers, Industrial Process Analyzers), By Gas Detected (Carbon Dioxide, Refrigerants, Hydrocarbons, Medical and Anesthetic Gases), By End-Use Industry (HVAC and Building Automation, Healthcare and Life Sciences, Industrial Safety, Automotive and Transportation, Agriculture), By Platform (Module-Level Sensors, PCB-Mount Chip Sensors, Standalone Instruments, Integrated System Nodes), By Regional (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Industry Forecast to 2035.
ID: MRFR/SEM/20508-HCR 128 Pages Ankit Gupta Last Updated: September 17, 2026
Non Dispersive Infrared Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.31%
2025 Market SizeUSD 0.81 Billion
2035 Market SizeUSD 1.58 Billion
Key Players
Honeywell International Inc.
Sensirion AG
Vaisala Oyj
Amphenol Advanced Sensors
Siemens AG
Emerson Electric Co.
Opportunities
  • Sensor-as-a-Service Contracting
  • Automatic Compliance Reporting
  • South American and African Institutional Retrofit

Non Dispersive Infrared Market Summary

The Non-Dispersive Infrared Market reached USD 0.81 billion in 2025 and opens the forecast window at USD 0.83 billion in 2026, climbing to USD 1.58 billion by 2035 at a 7.31% CAGR. Two catalysts anchor that trajectory. California's AB 841 school ventilation program, which channels roughly USD 600 million into classroom air-handling upgrades, has made continuous CO₂ logging a procurement default rather than an option [1]. In parallel, the European F-Gas Regulation (EU) 2024/573 obliges operators of commercial refrigeration systems above 500 tCO₂e to install automatic leak detection, pulling optical sensing into equipment categories that previously relied on manual audits [2].

Legacy instrumentation is losing ground quickly. Catalytic pellistors and electrochemical cells — cheap but drift-prone and poisoned by silicones — are being displaced by optical benches that hold calibration for a decade. Photoacoustic architectures compress the optical path into 14 mm packages, allowing designers to place a detector inside a thermostat, a vehicle cabin vent, or a wearable. The US Inflation Reduction Act's 179D deduction refunds up to 30% of qualifying retrofit spend, effectively subsidizing this substitution across commercial real estate [3].

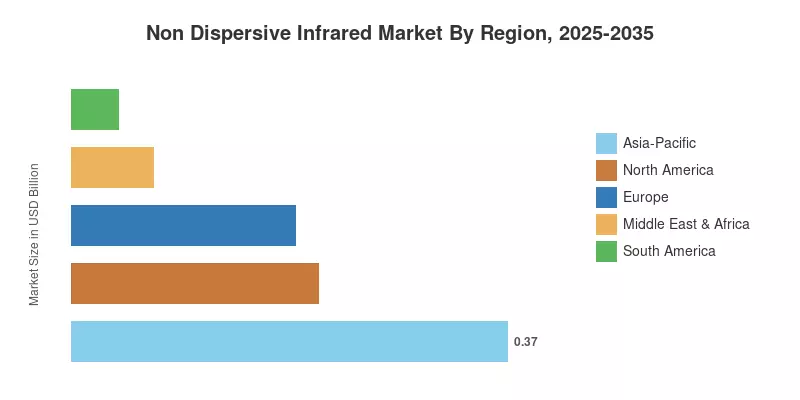
Regionally, Asia-Pacific commands 45.10% of 2025 revenue in the Non-Dispersive Infrared Market, supported by high-volume Chinese and Korean module fabrication. The Middle East & Africa posts the fastest expansion at 8.40% CAGR as Gulf green-building codes tighten. North America ranks second, propelled by ASHRAE 62.1 ventilation compliance across institutional portfolios. Through 2035, the Non-Dispersive Infrared Market shifts from compliance hardware toward networked, self-diagnosing sensing infrastructure.

Key Report Takeaways

• By Product Type

  • Fixed and Wall-Mount Modules held 40.20% share of the Non-Dispersive Infrared Market in 2025, sustained by institutional retrofit volume.
  • Smart and Connected Sensors are forecast to expand at a 7.85% CAGR through 2035 as Matter interoperability removes installer lock-in.

• By Gas Detected

  • Carbon Dioxide (CO₂) contributed USD 0.40 billion of Non-Dispersive Infrared Market revenue in 2025
  • Refrigerants advance at an 8.34% CAGR as F-Gas and Kigali deadlines force automatic leak detection.

• By End-Use Industry

  • HVAC and Building Automation captured 33.40% share in 2025, anchored by ventilation code enforcement
  • Healthcare and Life Sciences records a 7.92% CAGR, driven by capnography in every emergency bay.

• By Platform

  • Module-Level Sensors accounted for 46.90% of 2025 revenue in the Non-Dispersive Infrared Market.
  • PCB-Mount Chip Sensors grow at 7.98% CAGR inside consumer and automotive designs.

• By Region

  • Asia-Pacific led the Non-Dispersive Infrared Market with 45.10% revenue share in 2025
  • Middle East & Africa expands at 8.40% CAGR through 2035
  • Europe generated USD 0.19 billion in 2025 under refrigerant compliance spending

Market Size and Forecast (2021–2035)

Figures below combine bottom-up shipment modelling across four platform classes with top-down validation against reported segment revenue from listed sensor manufacturers, customs data on optical component flows, and building-permit registries in twelve national markets. Historical years are reconciled against audited filings; forecast years apply calibrated adoption curves weighted by regulatory enforcement dates.
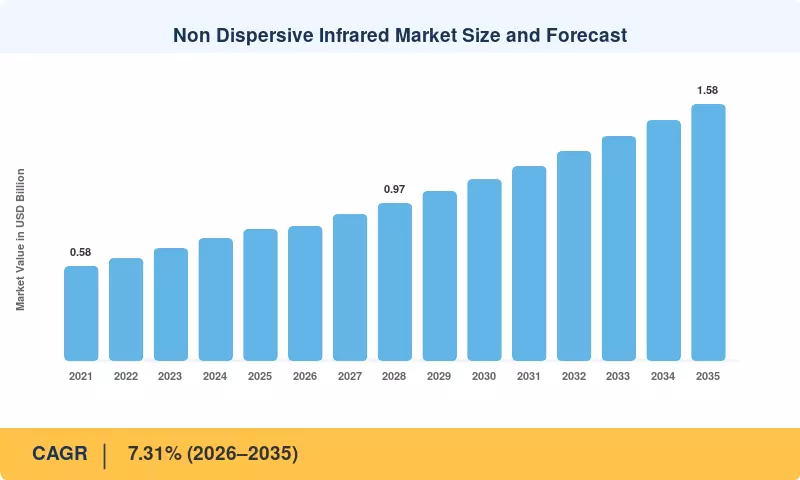
Non Dispersive Infrared Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Impact percentages below are directional estimates of each driver's relative contribution to growth momentum in the Non-Dispersive Infrared Market. They reflect analyst weighting of regulatory scope, addressable installed base, and procurement lead time. They are not additive and should not be summed to reconstruct the headline CAGR.

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Mandatory indoor-air-quality legislation ~1.6% North America, Europe, China Short-term (≤2 yr)
Refrigerant leak-detection mandates ~1.3% Europe, North America Medium-term (2–4 yr)
Miniaturization of photoacoustic optics ~1.2% Asia-Pacific, North America Medium-term (2–4 yr)
Vehicle cabin and EV thermal monitoring ~1.0% Asia-Pacific, Europe Long-term (≥4 yr)
Green-building certification schemes ~0.9% Middle East, Europe Medium-term (2–4 yr)
Calibration-free warranty economics ~0.8% Global Short-term (≤2 yr)
Controlled-environment agriculture ~0.6% Asia-Pacific, North America Long-term (≥4 yr)


Mandatory Indoor-Air-Quality Legislation

California AB 841 committed approximately USD 600 million to school ventilation assessment and upgrade, with districts required to verify outdoor-air delivery rates rather than assume them [1]. Verification demands continuous measurement, and CO₂ is the accepted proxy. Beijing's DB11/T 1811 standard applies comparable logic to metro-area office towers. Each mandate converts a discretionary sensor purchase into a line item that survives budget review, which is why order books in this category show low cancellation rates.

Refrigerant Leak-Detection Mandates

Regulation (EU) 2024/573 requires automatic leak detection on stationary systems above 500 tCO₂e and tightens HFC quotas by roughly 95% against a 2015 baseline by 2036 [2]. Detecting R-1234yf against water-vapor interference requires narrow-bandpass optics that pellistors cannot deliver. Operators facing per-installation fines calculate that a EUR 400 detector is cheaper than one enforcement action, so replacement cycles have compressed from ten years to four.

Miniaturization of Photoacoustic Optics

Photoacoustic designs fold the optical path into a sealed cavity, shrinking packages to roughly 14 mm and cutting current draw below levels that coin cells can sustain [7]. That opens smartwatch, air-purifier, and dashboard sockets previously closed to optical gas sensing. Unit volumes in these consumer channels run an order of magnitude above industrial volumes, so even modest attach rates shift the revenue mix meaningfully by the early 2030s.

Vehicle Cabin and EV Thermal Monitoring

Euro NCAP's 2026 protocol update rewards cabin-monitoring systems addressing occupant alertness, and CO₂ accumulation is a documented drowsiness precursor [8]. Electric-vehicle makers face a second incentive: recirculation strategy affects HVAC load, and HVAC load affects range. Embedding a cabin detector lets thermal software recirculate longer without air-quality penalty, recovering an estimated 3–5% of winter range in cold-climate driving cycles.

Green-Building Certification Schemes

Abu Dhabi's Estidama Pearl rating and Dubai's Al Sa'fat code both award credits for demand-controlled ventilation, which is unimplementable without continuous concentration data [6]. Gulf developers pursuing anchor-tenant leases treat these ratings as commercial necessities. With regional construction pipelines exceeding USD 90 billion in active projects, specification volume alone explains why the Middle East posts the highest growth rate in this study.

Calibration-Free Warranty Economics

Incumbent suppliers now ship probes with ten-year calibration-free warranties, eliminating an annual service visit that facility managers price at USD 150–250 per device [9]. Over a decade, that avoided cost exceeds the hardware price. Offshore and remote-site operators weigh this more heavily still, because calibration-gas logistics dominate total cost of ownership where a technician visit requires a helicopter booking.

Controlled-Environment Agriculture

Vertical farms enrich growing chambers to roughly 1,500 ppm to lift photosynthetic yield, and enrichment without measurement wastes gas that represents 6–9% of operating cost [10]. Sensors must survive 95% relative humidity without drift, which favors sealed optical benches over electrochemical alternatives. Japanese and Dutch operators lead adoption, and Gulf food-security programs are replicating the model with state financing.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Price compression from high-volume manufacturers ~-1.1% Global Short-term (≤2 yr)
Optical bench cost floor versus MEMS alternatives ~-0.8% Asia-Pacific Medium-term (2–4 yr)
Fragmented IAQ enforcement outside OECD ~-0.7% South America, Africa Long-term (≥4 yr)
Cross-sensitivity and humidity error in field use ~-0.5% Global Medium-term (2–4 yr)
Retrofit labor scarcity in building services ~-0.4% Europe, North America Short-term (≤2 yr)


Price Compression from High-Volume Manufacturers

Chinese module suppliers have driven entry-level CO₂ detector pricing below USD 12 at volume, roughly 40% under 2021 levels [5]. Unit growth therefore outpaces revenue growth in the thermostat and air-purifier channels. Established vendors defend margin through warranty length and embedded analytics rather than price, but the blended average selling price still declines about 4% annually.

Optical Bench Cost Floor Versus MEMS Alternatives

Optical designs carry an irreducible bill of materials — emitter, filter, detector, chamber — that MEMS metal-oxide devices avoid [7]. Where regulation specifies a threshold alarm rather than an accurate reading, buyers increasingly accept the cheaper alternative. This substitution is concentrated in consumer air purifiers and low-tier building controls, capping penetration in the highest-volume tiers of the addressable base.

Fragmented Enforcement Outside OECD Markets

Ventilation standards exist in most South American and African building codes, but inspection capacity is thin; compliance audits in Brazil reach an estimated 15% of commercial stock annually [11]. Without enforcement, specified sensors are value-engineered out during construction. Demand in these geographies therefore tracks multinational tenant requirements rather than domestic law, limiting the addressable base considerably.

Cross-Sensitivity and Humidity Error in Field Use

Field investigations of installed detectors reveal accuracy loss of more than ±10% in locations where condensation cycles are common, especially in unconditioned mechanical rooms [12]. Remediation necessitates the use of heated cavities or dual-wavelength compensation, both of which add cost. Procurement teams who had a bad first deployment are reluctant to expand until they have internally validated it, which adds two to three quarters to sales cycles.


Retrofit Labor Scarcity in Building Services

European building-services contractors estimate vacancy rates of close to 12% for commissioning personnel, and installed sensors have no compliance value unless commissioned [13]. Projects therefore fall behind irrespective of hardware. Wireless mesh topologies help reduce this by reducing down on cabling work; however, the actual commissioning procedure requires a competent person onsite.


Non Dispersive Infrared Market Opportunities

Sensor-as-a-Service Contracting

Consolidating hardware, calibration, dashboards and compliance reporting into a monthly fee turns a capital acquisition into an operational expense, which clears the budget faster in school districts and public hospitals. Vendors get recurring income at gross margins way higher than hardware, and get visibility into fleet drift driving the next product cycle. Contracts of five to seven years also block the price-driven substitution outlined in


Automatic Compliance Reporting

Building owners that are subject to ventilation codes are required to provide evidence, and that evidence is now collected manually from logger exports. Sensors that create WELL and Title 24 paperwork without human intervention remove billable consultant hours of USD 8,000-15,000 per building each year. Whoever owns the reporting layer owns renewal since switching suppliers requires reconstructing an audit trail that regulators have already accepted.


South American and African Institutional Retrofit

Enforcement gaps described in cut both ways: they suppress current demand but leave a large untouched installed base. Multilateral financing — including World Bank green-building credit lines — is beginning to attach ventilation performance conditions to disbursement. Suppliers who localize service networks ahead of that financing wave will face little incumbent resistance when specification volume arrives.

Automotive Design-In Cycles

Cabin monitoring described in enters production programs on five-year design cycles, meaning 2026–2027 wins determine revenue through 2032. Automotive qualification is expensive and slow, which deters entrants and protects those who complete it. Suppliers already carrying AEC-Q103 qualification can amortize that investment across multiple platforms at volumes industrial channels never reach.

Carbon-Capture and Process Verification

Capture facilities require concentration verification on pressurized lines, and laser analyzers priced above USD 30,000 dominate by default. Ruggedized optical probes rated for 40-bar service undercut that price by an order of magnitude while meeting measurement uncertainty thresholds under emerging monitoring, reporting, and verification protocols [14]. As carbon credits require verified tonnage, instrumentation moves from operational necessity to revenue infrastructure.

Non Dispersive Infrared Market Future Outlook

Edge Intelligence Replaces Scheduled Maintenance

On-chip inference is moving diagnostics from calendar-based service to condition-based alerts. Detectors now flag lens fouling by recognizing signal-envelope changes before measurement accuracy degrades, which preserves compliance continuity and removes the pretext for competitive displacement at service intervals. As inference cost falls, the differentiator shifts from optical performance to the quality of the drift model. Vendors with a decade of field telemetry hold an advantage that new entrants cannot buy, and the Non-Dispersive Infrared Market will consolidate around that data asset.

Networked Sensing Economics

Thread and Matter adoption has cut installation labor by roughly 30% by eliminating repeaters and proprietary gateways, opening retrofit work to general electrical contractors [16]. That expands the qualified installer pool dramatically in markets constrained by commissioning scarcity. Once a building runs an interoperable mesh, adding a detector becomes a marginal decision rather than a project, and sensor density per building rises. Density growth, more than building count growth, drives unit volume through the back half of the forecast.

Decarbonization Measurement Infrastructure

The International Energy Agency projects carbon capture capacity reaching approximately 435 Mt annually by 2030 under announced pledges, and every tonne claimed requires verified measurement [14]. Concurrently, corporate reporting under CSRD obliges roughly 50,000 European entities to disclose operational emissions with auditable data. Instrumentation that was previously an operating cost becomes an input to a financial disclosure, which changes who signs the purchase order and how tolerant they are of measurement uncertainty.

Consumer and Mobility Channel Maturation

Package sizes below 15 mm and power budgets compatible with battery operation place gas sensing inside products that ship in tens of millions of units. Automotive cabin monitoring, wearable respiratory tracking, and smart-thermostat integration each represent volumes the industrial base never approached. Margins in these channels are thin and design cycles unforgiving, but they reset the scale of the Non-Dispersive Infrared Market. By 2035 consumer and mobility channels should account for a materially larger revenue share than in 2025.

Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
Asia-Pacific 45.10% share Module fabrication scale, urban IAQ standards, EV cabin design-in
North America USD 0.21 Billion School and institutional retrofit, refrigerant compliance
Europe USD 0.19 Billion F-Gas enforcement, EPBD renovation wave
Middle East & Africa 8.40% CAGR Green-building certification, food-security agriculture
South America 4.60% share Multinational tenant standards, cold-chain expansion
Total USD 0.81 Billion —

Regional performance in the Non-Dispersive Infrared Market tracks the strength and enforceability of ventilation and refrigerant regulation more closely than it tracks GDP. Manufacturing concentration reinforces this: Asia-Pacific both produces and consumes the largest share of optical modules.


North America

Country Metric Key Driver
US 82.00% share of region School ventilation funding and ASHRAE 62.1 enforcement
Canada USD 0.03 Billion National Building Code ventilation amendments
Mexico 7.90% CAGR Cold-chain and manufacturing safety monitoring


American demand rests on institutional procurement that survives political cycles because it is embedded in building code rather than appropriation. The Inflation Reduction Act's 179D pathway refunds a substantial share of qualifying retrofit spend, and ESSER-funded ventilation projects created a validated installed base that facilities teams now expand incrementally [3]. Canadian volume concentrates in Ontario and British Columbia institutional stock. Mexican growth follows nearshoring investment, where new food-processing and pharmaceutical plants specify monitoring at construction rather than retrofitting later.

Europe

Country Metric Key Driver
Germany 24.10% share of region Industrial process safety and refrigeration compliance
UK USD 0.03 Billion Building Regulations Part F ventilation requirements
France 7.20% CAGR Mandatory school IAQ surveillance under decree 2022-1690
Italy 9.80% share of region Superbonus-driven renovation of commercial stock
Spain 6.90% CAGR RITE ventilation revisions and hospitality retrofit
Nordic Countries USD 0.02 Billion District-scale demand-controlled ventilation
Russia 3.10% share of region Industrial process monitoring, constrained by sanctions
Rest of Europe 6.40% CAGR EPBD transposition across CEE member states


European demand is regulation-manufactured. The recast Energy Performance of Buildings Directive requires member states to renovate the worst-performing 16% of non-residential stock by 2030, and demand-controlled ventilation is among the cheapest routes to the required performance improvement [15]. French decree 2022-1690 mandates periodic air-quality surveillance in schools and childcare facilities, converting a one-time audit market into recurring instrumentation. German industrial demand is separate and refrigeration-led, tied directly to F-Gas quota enforcement.

Asia-Pacific

Country Metric Key Driver
China 51.20% share of region Urban office IAQ standards and domestic module supply
India 8.90% CAGR Commercial construction and green-certification uptake
Japan USD 0.06 Billion Controlled-environment agriculture and medical gas monitoring
South Korea 9.40% share of region Semiconductor fab process safety and automotive design-in
ASEAN 8.10% CAGR Data-center construction and cold-chain buildout
Rest of Asia-Pacific USD 0.02 Billion Institutional and hospitality retrofit


China anchors the region on both sides of the ledger, manufacturing the modules that set global price floors while enforcing DB11/T office standards that generate domestic volume. Indian demand accelerates from a low base as IGBC and LEED certification become leasing prerequisites in Bengaluru and Hyderabad office parks. Japanese buyers concentrate in vertical farming and hospital instrumentation, where accuracy specifications exclude commodity alternatives. Korean semiconductor fabs deploy optical detection for process gas safety at densities far above commercial building norms.

South America

Country Metric Key Driver
Brazil 61.00% share of region Cold-chain refrigeration and multinational office standards
Argentina USD 0.01 Billion Agricultural storage and grain handling safety
Rest of South America 6.80% CAGR Mining ventilation and hospitality construction


Brazilian demand originates with multinational tenants importing corporate ventilation standards into São Paulo and Rio office leases, and with an expanding cold chain serving protein exports. ANVISA storage requirements for pharmaceutical distribution add a regulated tier that specifies continuous monitoring. Argentine volume is agricultural, concentrated in grain storage where fumigant and CO₂ concentration monitoring protects both product and personnel. Chilean and Peruvian mining ventilation constitutes most of the remainder, where underground air quality is a licensing condition.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 34.60% share of region Giga-project construction and Mostadam certification
UAE USD 0.02 Billion Estidama and Al Sa'fat green-building codes
South Africa 8.30% CAGR Mining ventilation and commercial retrofit
Egypt 7.60% CAGR New administrative capital construction
Rest of MEA 6.20% share of region Healthcare and hospitality development


Gulf construction converts building codes into instrumentation demand at unusual speed because project pipelines are large and centrally directed. Saudi giga-projects specify Mostadam ratings at design stage, embedding demand-controlled ventilation before ground is broken [6]. Emirati regulation is more mature and now drives retrofit as much as new build. South African demand splits between deep-level mining, where ventilation monitoring is a safety-licence condition, and Johannesburg commercial stock responding to load-shedding-driven HVAC optimization.

Non Dispersive Infrared Market By Region, 2025-2035

Non Dispersive Infrared Market Segmentation

By Product Type

Segment Metric (2025) Primary Demand Driver
Fixed/Wall-Mount Modules 40.20% share Institutional ventilation retrofit volume
Smart and Connected Sensors 7.85% CAGR Predictive maintenance and remote firmware updates
Portable/Handheld Analyzers USD 0.13 Billion Occupational safety audits and refinery turnarounds
Industrial Process Analyzers 14.60% share Explosion-proof petrochemical installations


Fixed and Wall-Mount Modules lead on installed-base inertia — every compliance retrofit specifies them by default, and replacement follows a predictable cycle. Smart and Connected Sensors grow fastest because wireless firmware updates eliminate truck rolls and Matter interoperability lets local electricians handle work that once required proprietary installers. Portable/Handheld Analyzers hold a defensible niche in SIL2-certified safety auditing, while Industrial Process Analyzers depend on megasite capital cycles that move slowly but at high ticket value.

By Gas Detected

Segment Metric (2025) Primary Demand Driver
Carbon Dioxide (CO₂) USD 0.40 Billion Ventilation codes and demand-controlled HVAC
Refrigerants 8.34% CAGR F-Gas and Kigali automatic leak-detection mandates
Hydrocarbons (CH₄, C₃H₈) 19.80% share Migration from catalytic pellistors in sour-gas fields
Medical and Anesthetic Gases 6.10% share ISO 80601 operating-room compliance


Carbon Dioxide (CO₂) remains the revenue anchor because ventilation regulation names it explicitly as the compliance proxy, but its growth tracks the market average rather than exceeding it. Refrigerants advance fastest: narrow-bandpass optics separating R-1234yf from water vapor command premium pricing that pellistor incumbents cannot match. Hydrocarbons (CH₄, C₃H₈) migrate to optical detection in high-H₂S fields where ignition risk rules out catalytic elements, while Medical and Anesthetic Gases remain small, accuracy-driven, and margin-rich.

By End-Use Industry

Segment Metric (2025) Primary Demand Driver
HVAC and Building Automation 33.40% share Ventilation code enforcement and certification credits
Healthcare and Life Sciences 7.92% CAGR Capnography expansion beyond operating rooms
Industrial Safety and Process USD 0.19 Billion Permissible exposure limit monitoring
Automotive and Transportation 8.60% share Cabin CO₂ monitoring and EV thermal management
Agriculture and Food Processing 6.70% share Enrichment control and controlled-atmosphere packaging


HVAC and Building Automation leads because ventilation mandates apply to the largest addressable footprint — schools, hotels, offices, and coworking space — and tax credits absorb a meaningful share of retrofit cost. Healthcare and Life Sciences grows fastest as hospitals move capnography from one instrument per operating room to real-time monitoring in every emergency bay. Industrial Safety and Process buyers integrate detection into leak-alert systems triggering below the 5,000 ppm exposure limit, a specification that excludes lower-accuracy substitutes.

By Platform

Segment Metric (2025) Primary Demand Driver
Module-Level Sensors 46.90% share Field-serviceable retrofit kits with Modbus and IP65
PCB-Mount Chip Sensors 7.98% CAGR Consumer devices and automotive dashboard integration
Standalone Instruments 21.30% share Laboratory reference and calibration verification
Integrated System Nodes USD 0.13 Billion Building management system native integration


Module-Level Sensors dominate because industrial retrofit practice is built around swappable units with weatherproof housings and legacy protocol support — service routines refined over decades resist change. PCB-Mount Chip Sensors grow fastest as photoacoustic architectures shrink optical paths into packages that fit smartwatches and dashboard vents, with Bluetooth 5.3 supplying enough transmit power to stream multi-gas data without draining coin cells. Standalone Instruments persist as reference devices; Integrated System Nodes advance where building management vendors bundle sensing into controller hardware.

Competitive Benchmarking

Concentration in the Non-Dispersive Infrared Market sits in the medium band, with an estimated HHI between 850 and 1,050 and a top-five combined share near 44%. No supplier controls a majority in any single segment. The structure splits into three tiers: diversified industrial groups selling detection as part of a safety portfolio, specialist sensor houses competing on optical performance and warranty length, and high-volume Asian manufacturers competing on unit cost. Consolidation pressure is rising in the specialist tier as automotive qualification costs favor scale.

Company Est. Revenue Share Range Key Offerings for Non-Dispersive Infrared Market Strategic Positioning
Honeywell International Inc. ~11–14% Dual-wavelength hydrocarbon detectors, fixed gas monitors Bundles detection into industrial safety systems; strong refinery installed base
Sensirion AG ~8–11% Photoacoustic CO₂ modules, connected building sensors Miniaturization leader; deep design-in with HVAC and consumer OEMs
Vaisala Oyj ~7–10% Long-life CO₂ probes, life-science instrumentation Premium accuracy positioning with decade-long calibration-free warranties
Amphenol Advanced Sensors ~6–9% Board-level modules, telaire building sensors Volume OEM supplier with broad HVAC channel reach
Siemens AG ~5–8% Process analyzers, building automation integration Sells sensing inside larger automation contracts
Emerson Electric Co. ~4–7% Continuous emission analyzers, process instrumentation Focused on process industries and emissions compliance
ABB Ltd. ~4–6% Industrial gas analyzers, stack monitoring systems Strength in power generation and heavy process verticals
Figaro Engineering Inc. ~3–5% Compact CO₂ and hydrocarbon sensor elements Cost-competitive component supply into Asian OEM base
Murata Manufacturing Co., Ltd. ~3–5% Miniature sensor components for consumer devices Leverages passive-component scale for consumer channel entry
SenseAir (Asahi Kasei Microdevices) ~3–5% Building and automotive CO₂ sensing platforms Automotive qualification and cabin-monitoring design wins
Teledyne Technologies Inc. ~2–4% Analytical instruments, medical gas monitoring Niche high-accuracy instrumentation across regulated applications


Recent News & Developments

  • European Commission (February 2024): Regulation (EU) 2024/573 entered force, mandating automatic leak detection on large stationary refrigeration systems and setting an HFC phase-down path to 2050 — creating a compliance-driven replacement cycle for optical detectors [2]
  • Sensirion (May 2024): Launched Wi-Fi-enabled SCD43 modules generating automated compliance documentation for WELL and Title 24 submissions, reducing consultant hours in certification workflows [17]
  • Honeywell (September 2024): Introduced a dual-wavelength hydrocarbon detector with real-time humidity compensation holding ±5% precision across a 5,000 ppm range, targeting sour-gas production sites [18]
  • Vaisala (March 2025): Extended its ten-year calibration-free warranty to carbon-capture-rated probes qualified for 40-bar pressure lines, positioning against laser analyzers priced an order of magnitude higher [9]
  • Asahi Kasei Microdevices (June 2025): Announced automotive-qualified cabin sensing platform design wins with two Asian EV manufacturers for 2027 model-year programs, tied to Euro NCAP occupant-monitoring criteria [8]
  • Amphenol Advanced Sensors (August 2025): Completed acquisition of a European optical bench specialist to expand refrigerant detection capability ahead of F-Gas enforcement deadlines [19]
  • Connectivity Standards Alliance (October 2025): Published Matter 1.4 air-quality device types standardizing sensor onboarding across building platforms, removing gateway dependency for retrofit installations [16]
  • Saudi Building Code Authority (November 2025): Extended Mostadam certification requirements to additional commercial building classes, embedding demand-controlled ventilation in giga-project design specifications [6]

Non Dispersive Infrared Market Report Scope

Parameter Detail
Market Scope Global market for non-dispersive infrared gas sensing hardware, modules, and instruments across product type, gas detected, end-use industry, platform, and geography
Study Period 2021–2035 (Historical: 2021–2024; Base Year: 2025; Forecast: 2026–2035)
CAGR 7.31% (2026–2035)
Market Size Checkpoints USD 0.81 Billion (2025); USD 0.83 Billion (2026); USD 1.12 Billion (2030); USD 1.58 Billion (2035)
Fastest Growing Segments Refrigerants (8.34% CAGR); PCB-Mount Chip Sensors (7.98% CAGR); Healthcare and Life Sciences (7.92% CAGR)
Companies Profiled Honeywell International Inc., Sensirion AG, Vaisala Oyj, Amphenol Advanced Sensors, Siemens AG, Emerson Electric Co., ABB Ltd., Figaro Engineering Inc., Murata Manufacturing Co., Ltd., SenseAir (Asahi Kasei Microdevices), Teledyne Technologies Inc.
Valuation Currency USD Billion, constant 2025 prices

FAQs

What warranty and calibration terms should procurement teams negotiate when buying into the Non-Dispersive Infrared Market?
Insist on calibration-free coverage of at least seven years with a documented drift specification, not just a replacement guarantee. Ask vendors to define accuracy at end-of-warranty rather than at shipment, since that gap determines true cost of ownership [9].
How does optical gas detection compare with metal-oxide MEMS sensing?
Optical benches deliver absolute concentration readings with stable long-term accuracy; MEMS devices infer relative change and require frequent baselining. Choose MEMS only where a threshold alarm suffices and regulation does not demand quantified values [7].
What integration problems most often delay deployments in the Non-Dispersive Infrared Market?
Protocol mismatch between sensors and legacy building management controllers causes most schedule slippage, followed by commissioning labor availability. Specifying Matter or BACnet native support at tender stage avoids gateway retrofits that add cost late [16].
Which certifications matter for medical and pharmaceutical applications?
ISO 80601-2-55 governs respiratory gas monitors and sets the accuracy floor for anesthetic and capnography devices [21]. Pharmaceutical fermentation buyers additionally require documented IQ/OQ validation packages before a sensor can enter a GMP environment.
How should investors read consolidation signals in this sector?
Automotive qualification costs are the pressure point — specialists without AEC-Q credentials face acquisition or exclusion from the highest-volume channel. Watch for optical-bench component makers being absorbed by connector and passive-component groups seeking design-in leverage [19].
Where does the Non-Dispersive Infrared Market face genuine substitution risk?
Consumer air purifiers and entry-tier thermostats, where buyers accept indicative readings at a fraction of the price. Regulated applications requiring quantified concentration values remain structurally protected from cheaper alternatives [5].
What emerging use case is most underestimated today?
Verified measurement for carbon credit issuance. As monitoring, reporting, and verification protocols harden, instrumentation becomes an input to auditable financial disclosure rather than an operating expense, shifting purchase authority toward finance functions [14].
Author
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















