NMC Battery Pack Market Summary
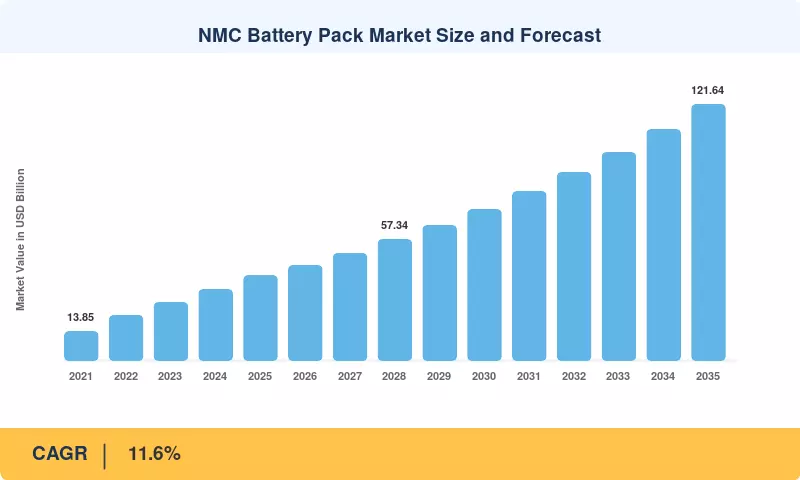
The NMC Battery Pack Market was valued at USD 40.52 Billion in 2025 and is projected to reach USD 45.30 Billion in 2026. It is forecast to climb to USD 121.64 Billion by 2035, a CAGR of 11.6% over 2026–2035. Two catalysts anchor this trajectory. Global electric car sales passed 17 million units in 2024, more than one in five new cars sold [1]. The European Union has also locked in a 100% CO2 reduction target for new cars from 2035 under Regulation (EU) 2023/851 [7], which forces every volume automaker serving Europe to secure long-range traction batteries at scale.
Pack technology is changing fast. Early NMC111 and NMC532 cells, packaged in bulky module-based designs, are giving way to high-nickel NMC811 and 9-series cathodes, cell-to-pack architectures, and large-format 46-series cylindrical cells. Pack prices fell 20% in 2024 to about USD 115 per kWh, the steepest drop since 2017 [3]. Public capital is backing the shift: the U.S. Department of Energy awarded USD 3 billion to 25 battery materials and manufacturing projects in September 2024 [4].
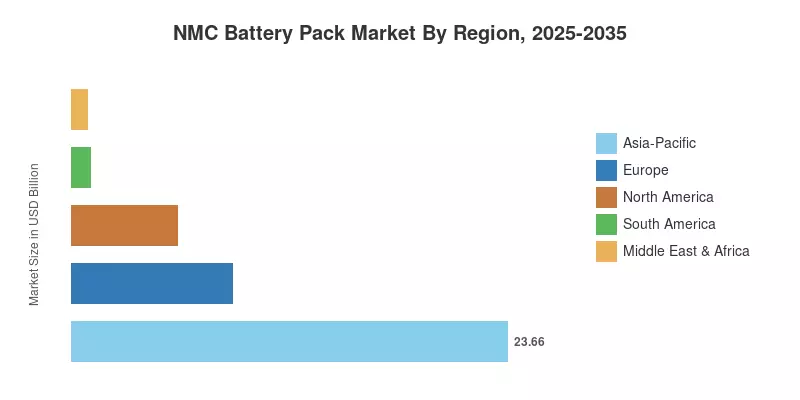
Asia-Pacific dominates the NMC Battery Pack Market with a 58.4% share, led by Chinese and Korean cell makers. North America is the fastest-growing region at a 14.2% CAGR as localized gigafactories in Kansas, Tennessee, Kentucky, and Indiana reach volume. Europe ranks second at USD 8.75 billion, supported by premium German OEMs that favor NMC for long-range models. Over the next decade, competitiveness will hinge on cathode cost, regional content compliance, and pack-level energy density.
Key Report Takeaways
• By Body Type
- Passenger Car holds a 74.6% share of the NMC Battery Pack Market, reflecting the chemistry's fit with long-range consumer EVs.
- M&HDT is the fastest-growing body type at a 16.4% CAGR as heavy-duty CO2 rules tighten.
• By Propulsion Type
- BEV accounts for an 81.2% share of installed NMC pack value.
- PHEV expands at a 12.8% CAGR, driven by extended-range models in North America and Europe.
• By Capacity
- 40 kWh to 80 kWh leads with a 52.7% share.
- Above 80 kWh grows at a 14.6% CAGR on demand for premium SUVs and pickups.
• By Battery Form
- Prismatic commands a 46.8% share.
- Cylindrical advances at a 15.3% CAGR as 46-series cells scale.
• By Method
- Wire bonding holds a 61.5% share.
- Laser welding rises at a 15.8% CAGR.
• By Component
- Cathode represents a 48.9% share of the NMC Battery Pack Market cost base.
- Anode grows at a 13.4% CAGR on silicon-blend adoption.
• By Material Type
- Nickel holds a 34.2% share of material value.
- Lithium grows at a 13.7% CAGR.
• By Region
- Asia-Pacific leads with a 58.4% share.
- North America is the fastest-growing region at a 14.2% CAGR.
Market Size and Forecast (2021–2035)
Market Research Future built this forecast bottom-up from vehicle production data, average pack capacity by body type, and NMC chemistry share by region, then validated totals against cell maker shipments and OEM procurement disclosures. Historical values draw on industry association sales data [10] and battery price surveys [3]; forecast values apply a scenario model weighted toward announced capacity and enacted policy.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



