Mechanical Seals Market (2026 - 2035)

Mechanical Seals Market Research Report By Seal Type (Pump Seals, Compressor Seals, Mixer Seals), By Design Type (Component/Pusher, Cartridge, Split), By End-User Industry (Oil and Gas, Power Generation, Chemical, Water and Waste-Water, Other End-User Industries) - Forecast to 2035
ID: MRFR/Equip/23990-HCR
128 Pages
Snehal Singh
Last Updated: September 02, 2026
Mechanical Seals Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.9%
2025 Market SizeUSD 8.15 Billion
2035 Market SizeUSD 13.15 Billion
Key Players
John Crane
EagleBurgmann
Flowserve
AESSEAL
Trelleborg Sealing Solutions
Parker Hannifin
Opportunities
  • Hydrogen and CO2 Service Qualification
  • Municipal Water Aftermarket in Emerging Economies
  • Reliability Data as a Product

Mechanical Seals Market Summary

The Mechanical Seals Market was valued at USD 8.15 Billion in 2025, opens the forecast window at USD 8.55 Billion in 2026, and is projected to reach USD 13.15 Billion by 2035, expanding at a 4.9% CAGR. Growth rests on two very different foundations. One is the sheer installed base of rotating equipment — millions of centrifugal pumps and compressors that need sealing hardware replaced on predictable cycles. The other is regulatory: fugitive-emission rules under the U.S. EPA's OOOOb standards and the EU Industrial Emissions Directive have made leak-tight sealing a compliance obligation rather than a maintenance preference [6][8].

Equipment operators are steadily retiring single-face packing and gland arrangements in favour of engineered cartridge and dual-pressurised configurations that arrive pre-assembled and pre-set. That shift matters commercially, because a pre-engineered assembly carries roughly three times the unit value of the component it replaces. The International Energy Agency records more than USD 2.9 trillion in global energy investment during 2025, a share of which flows directly into pumping, compression, and separation trains where sealing content is specified early [1].

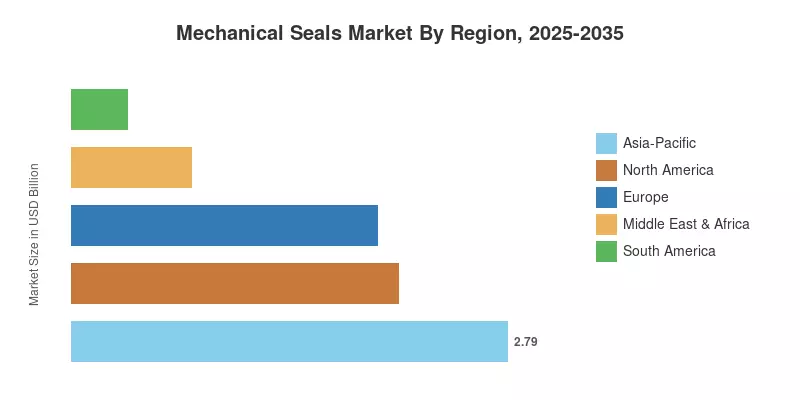
Asia-Pacific anchors the geography, holding 34.2% of 2025 revenue and compounding at 5.0% through 2035. North America follows at 25.6%, supported by dense aftermarket coverage, while Europe's 24.1% reflects hydrogen and decarbonisation retrofits. Over the coming decade, the Mechanical Seals Market will reward suppliers who can price commodity volume and engineer premium duty simultaneously.


Key Report Takeaways

• By Seal Type

  • Pump seals commanded 60.4% of Mechanical Seals Market revenue in 2025, underwritten by the centrifugal pump installed base.
  • Compressor seals are advancing at a 5.1% CAGR as utilities commission hybrid generation assets.
  • Mixer seals generated approximately USD 1.02 Billion in 2025 across chemical and pharmaceutical batch processing.

• By End-User Industry

  • Oil and gas accounted for 30.9% of Mechanical Seals Market revenue in 2025
  • Power generation is the fastest-expanding end-user at a 5.22% CAGR through 2035
  • Water and wastewater applications contributed close to USD 1.33 Billion in 2025

• By Region

  • Asia-Pacific held 34.2% of the Mechanical Seals Market in 2025
  • Middle East & Africa is compounding at 5.3%, the second-fastest regional rate
  • Europe generated roughly USD 1.96 Billion in 2025


Market Size and Forecast (2021–2035)

Figures below are built bottom-up from rotating-equipment population data, seal replacement intervals by service class, and average selling prices collected across OEM and distributor channels, then reconciled top-down against reported segment revenue from listed sealing suppliers. Historical years reflect actual shipments; forecast years apply demand elasticity to industrial capex and MRO budgets.
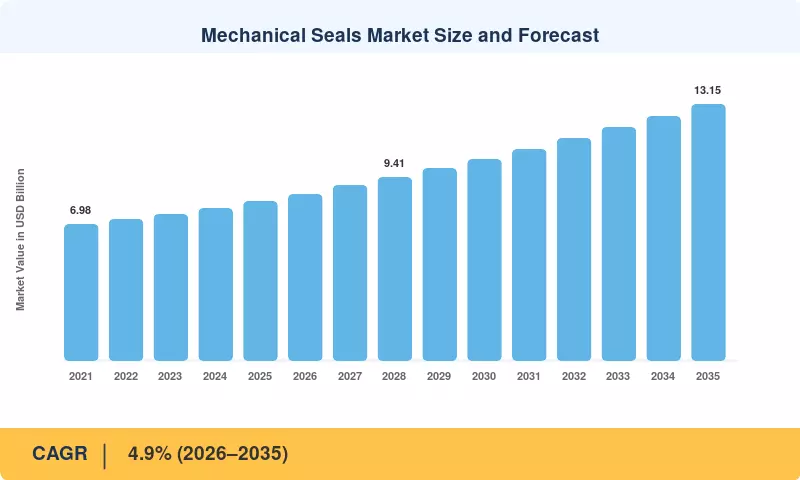
Mechanical Seals Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Asian refining and petrochemical capacity additions +0.9 Asia-Pacific, MEA Medium-term (2–4 yr)
API 682 Fourth Edition compliance upgrades +0.7 Global Short-term (≤2 yr)
Turbine retrofits and hybrid plant commissioning +0.8 North America, Europe, APAC Medium-term (2–4 yr)
Fugitive-emission regulation tightening +0.6 North America, Europe Short-term (≤2 yr)
Hydrogen and CO2 handling infrastructure +0.5 Europe, North America Long-term (≥4 yr)
Municipal water and waste-water capex +0.4 Global Long-term (≥4 yr)
Service-contract and MRO attach expansion +0.6 Global Short-term (≤2 yr)


Emission Rules Convert Sealing Into Compliance Hardware

Regulators stopped treating shaft leakage as a housekeeping issue. The U.S. EPA's OOOOb and OOOOc standards require covered facilities to eliminate or capture emissions from pump seals and compressor packing, and the agency's own regulatory impact analysis estimates USD 20 billion in cumulative compliance costs across affected operators through 2038 [6]. Europe's revised Industrial Emissions Directive imposes parallel obligations on roughly 52,000 installations [8]. Operators respond by replacing single-face arrangements with pressurised dual configurations that vent to a controlled barrier system.

Refinery and Petrochemical Build-Out Across Asia

China and India together added more than 1.1 million barrels per day of refining capacity between 2023 and 2025, and India's stated ambition is 450 million tonnes of annual throughput by 2030 [11]. Every new crude unit, hydrocracker, and aromatics train arrives with hundreds of pumps. Specification practice in these projects increasingly defaults to a double mechanical seal API 682 arrangement in hydrocarbon service, which lifts average unit value well above commodity replacement pricing.

Power Generation Retrofit Economics

Utilities are keeping existing turbine fleets in service longer while adding flexible gas capacity. The IEA reports global power sector investment above USD 1.5 trillion in 2025, with grid and generation upgrades absorbing the majority [1]. Retrofit work on boiler feed pumps, condensate extraction pumps, and centrifugal compressors generates dense sealing content per project, which is why power generation records the highest end-user growth rate in this study at 5.22%.

Service Contracts Reshape Revenue Quality

Suppliers have moved from selling parts to selling uptime. Reliability agreements now bundle installation, monitoring, and guaranteed mean-time-between-repair targets, and vendors report attach rates above 40% on installed fleets under such agreements [12]. Recurring revenue smooths the capex cycle and raises switching costs materially.


Restraints Impact Analysis

Restraint weightings follow the same directional convention as Section 4. They represent drag on Mechanical Seals Market expansion rather than subtractive components of the published CAGR.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Seal-less pump substitution −0.5 Europe, Japan Medium-term (2–4 yr)
Hard-face raw material cost volatility −0.4 Global Short-term (≤2 yr)
Commodity price erosion from regional suppliers −0.4 Asia-Pacific Medium-term (2–4 yr)
Shortage of qualified sealing technicians −0.3 North America, Europe Long-term (≥4 yr)
Downstream capex deferral cycles −0.3 MEA, South America Medium-term (2–4 yr)


Seal-Less Technology Takes the Easy Duties

Magnetic-drive and canned-motor pumps eliminate the dynamic seal. For low-flow, high-hazard chemical duties, plant engineers increasingly prefer that architecture, and European specifiers have adopted it fastest under REACH-driven exposure limits [7]. The substitution threat is real but bounded: seal-less units carry efficiency penalties and struggle above moderate head and viscosity thresholds, which protects the high-value applications.

Input Cost Exposure on Hard Faces

Performance depends on face materials and those materials’ pricing is unrelated to seal demand. A silicon carbide seal face depends on high-purity carbide feedstock, the spot pricing of which varied over 25% between 2023 and 2025 as abrasives and semiconductor purchasers vied for the same supply [10]. Vendors that are taking that volatility on fixed pricing frame agreements have taken 150 to 200 basis points of gross margin compression.


Price Compression in Commodity Categories

Standard component seals, now supplied by regional producers in Asia at a fraction of the Western list price. Distributors report bid margins on non-critical duties in excess of 45 percent [13]. Global brands have very much thrown in the towel on tier and moved capacity to designed and certified product lines.


Mechanical Seals Market Opportunities

Hydrogen and CO2 Service Qualification

Few providers can confirm sealing performance in pure hydrogen or dense phase CO2. Qualification credentials are a gatekeeping asset in the Mechanical Seals Market [3] as IEA is tracking over 460 announced low-emission hydrogen projects that have reached final investment decision phases. Early qualifying directly translates into lock-in of specifications for a decade of plant life.


Municipal Water Aftermarket in Emerging Economies

Utilities in South and Southeast Asia run aging pump fleets with limited shutdown windows. That constraint has provided a constant pull for split mechanical seal repair, where the cartridge inserts without dismantling the pump or disturbing coupling alignment. The World Bank estimates the funding shortfall for water infrastructure to be around USD 260 billion per year, and an increasing proportion of this spending is for rehabilitation rather than new construction [9].


Reliability Data as a Product

Instrumented seal support systems now stream barrier pressure, temperature, and flow to plant historians. Suppliers who own that telemetry can price failure-risk guarantees and sell condition-based service tiers rather than parts. Two major vendors already report monitoring-linked contracts covering more than 15,000 seal points globally [12].

Cryogenic and Specialty Gas Niches

LNG expansion, air separation, and semiconductor gas handling all demand sealing at extreme temperature differentials. These are low-volume, high-margin pockets within the Mechanical Seals Market where engineering depth beats price.

Localised Manufacturing in the Gulf

Saudi Arabia's In-Kingdom Total Value Add programme and comparable UAE mandates require local content thresholds on major project awards [5]. Suppliers establishing regional assembly and repair centres gain preferential access to Aramco and ADNOC framework agreements.


Mechanical Seals Market Future Outlook

Condition Monitoring Becomes Standard Specification

Sensor-equipped support systems will move from optional to default on critical duties. Plants running predictive programmes report unplanned downtime reductions between 20% and 30%, and that evidence is now firm enough for insurers and reliability engineers to write it into specifications [12]. Suppliers in the Mechanical Seals Market who cannot deliver telemetry-ready hardware will find themselves excluded from framework agreements.

Aftermarket Economics Overtake OEM Volume

Original equipment channels grow with capex; service revenue grows with the installed base. As the global rotating asset population ages, service and repair will account for an increasing share of total supplier revenue, shifting valuation logic toward recurring-revenue multiples.

Materials Science as Competitive Moat

Diamond-coated and engineered composite faces extend service life in abrasive and dry-running duties. Vendors holding coating know-how capture disproportionate value because face technology, not housing design, determines failure behaviour in the hardest applications.

Decarbonisation Rewires the Demand Mix

IRENA estimates that meeting climate targets requires energy transition investment above USD 4 trillion annually through 2030 [3]. Carbon capture compression, hydrogen handling, and heat-pump-driven industrial systems each introduce sealing duties without precedent in existing catalogues. The Mechanical Seals Market will therefore see catalogue expansion at the premium end even as legacy hydrocarbon volume plateaus.


Mechanical Seals Market Segmentation

By Seal Type

Pump seals dominate the Mechanical Seals Market because centrifugal pumps outnumber every other sealed rotating machine by an order of magnitude.

Segment Metric Primary Demand Driver
Pump Seals 60.4% share (2025) Centrifugal pump installed base and MRO cycles
Compressor Seals 5.1% CAGR Gas processing, LNG and turbine retrofits
Mixer Seals USD 1.02 Billion (2025) Chemical, pharmaceutical and food batch processing


Compressor seals carry the highest unit value in the taxonomy. A single dry-gas arrangement on a main refrigerant compressor can exceed the value of several hundred general-service pump seals, which is why suppliers chase this category despite modest unit volumes. Pump seals, conversely, deliver predictable cash flow — replacement intervals are well characterised, and procurement is routine rather than project-driven.

By Design Type

Design mix reveals where the Mechanical Seals Market is moving in value terms.

Segment Metric Primary Demand Driver
Component/Pusher 4.95% CAGR Cost-sensitive general service and OEM fitment
Cartridge 41.0% share (2025) Pre-set assemblies reducing installation error
Split USD 1.26 Billion (2025) Large pumps where disassembly is impractical


Cartridge designs win because they remove the technician from the setting equation. Installation errors historically caused a substantial share of premature failures; a pre-assembled unit with fixed axial setting eliminates that variable and pairs naturally with the shrinking pool of experienced fitters [14]. Component designs survive on price and remain the default for OEM first-fill on standard duties.

By End-User Industry

End-user distribution explains the Mechanical Seals Market sensitivity to energy capex cycles.

Segment Metric Primary Demand Driver
Oil and Gas 30.9% share (2025) Refining, upstream and midstream pumping
Power Generation 5.22% CAGR Turbine retrofits and hybrid plant commissioning
Chemical USD 1.61 Billion (2025) Aggressive media and containment requirements
Water and Waste-Water 16.3% share (2025) Municipal rehabilitation and desalination
Other End-User Industries 4.5% CAGR Pulp and paper, mining, food processing


Oil and gas remains the anchor, but its share is slowly eroding as power generation and water applications grow faster. That rotation improves portfolio stability for suppliers, since municipal water spending follows regulated capital programmes rather than commodity prices.


Regional Market Share Analysis

Region 2025 Metric Primary Investment Themes
North America 25.6% share Emission compliance, LNG export trains, reliability contracts
Europe USD 1.96 Billion Hydrogen readiness, IED compliance, plant life extension
Asia-Pacific 34.2% share Refining capacity, petrochemical build-out, power additions
South America 4.4% CAGR Pre-salt offshore, fertiliser and mining pumping
Middle East & Africa USD 0.77 Billion Gas processing, desalination, local content mandates
Total USD 8.15 Billion

Regional distribution in the Mechanical Seals Market tracks heavy-process capacity rather than population or GDP. Asia-Pacific leads on installed rotating equipment; North America leads on aftermarket intensity per asset.


North America

Country Metric Key Driver
US 78.4% of region Gulf Coast LNG and petrochemical corridor
Canada USD 0.28 Billion Oil sands upgrading and pipeline pumping
Mexico 4.7% CAGR Dos Bocas refinery ramp and PEMEX modernisation


American demand skews toward engineered product because compliance exposure is highest there. Gulf Coast liquefaction capacity under construction exceeds 90 million tonnes per annum, and each train specifies dry-gas sealing on main refrigerant compressors with redundant separation systems [1]. Aftermarket density is the region's structural advantage: distributor networks stock cartridge assemblies for same-day replacement, which sustains premium pricing that Asian markets do not support.

Europe

Country Metric Key Driver
Germany 24.6% of region Chemical park modernisation
UK USD 0.24 Billion North Sea life extension and water utility AMP cycles
France 4.3% CAGR Nuclear fleet refurbishment
Italy 11.2% of region Machinery OEM export base
Spain USD 0.13 Billion Renewable hydrogen clusters
Nordic Countries 4.5% CAGR Pulp, paper and carbon capture pilots
Russia 8.1% of region Domestic substitution of Western supply
Rest of Europe USD 0.22 Billion Central European process capacity


European buyers pay for documentation as much as hardware. Revised IED obligations covering tens of thousands of installations force operators to demonstrate emission performance at each sealing point, and Germany's chemical cluster operators have committed multi-year budgets to sealing upgrades within broader plant modernisation programmes [8]. France adds a distinct pull through EDF's Grand Carénage nuclear refurbishment, where primary and auxiliary circuit pumps require qualified sealing under nuclear codes.

Asia-Pacific

Country Metric Key Driver
China 41.3% of region Integrated refining-petrochemical complexes
India 5.9% CAGR Refinery expansion to 450 MTPA target
Japan USD 0.42 Billion Precision machinery and semiconductor gas handling
South Korea 8.4% of region Shipbuilding and offshore fabrication
ASEAN 5.4% CAGR Petrochemical and palm processing investment
Rest of Asia-Pacific USD 0.19 Billion Mining and general industry


Asia-Pacific's dominance in the Mechanical Seals Market is a function of project pipeline, not replacement intensity. China commissioned several integrated complexes exceeding 300,000 barrels per day between 2023 and 2025, each carrying thousands of sealing points at first fill [11]. India's growth rate leads globally as public-sector refiners execute expansion at Panipat, Barauni, and Numaligarh. The competitive consequence is a two-tier structure: global brands win critical-service specifications while domestic manufacturers capture general-service volume.

South America

Country Metric Key Driver
Brazil 58.6% of region Petrobras pre-salt production systems
Argentina USD 0.09 Billion Vaca Muerta unconventional development
Rest of South America 4.1% CAGR Copper mining and fertiliser processing


Brazilian demand concentrates offshore. Petrobras has committed capital exceeding USD 100 billion across its multi-year business plan, with the majority directed to exploration and production where topside pumping and gas compression dominate equipment content [5]. Argentine growth depends on midstream build-out from Vaca Muerta, which remains sensitive to currency and financing conditions.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 31.5% of region Jafurah gas development and downstream integration
UAE USD 0.14 Billion ADNOC capacity expansion to 5 MMbpd
South Africa 4.2% CAGR Mining dewatering and chemical processing
Egypt 9.6% of region Fertiliser and gas processing capacity
Rest of MEA USD 0.16 Billion Desalination and utility infrastructure


Gulf operators buy on qualified vendor lists that change slowly, making incumbency valuable and displacement difficult. Saudi Aramco's Jafurah development alone represents a multi-decade unconventional gas programme with associated processing trains, while desalination capacity across the region continues to expand under national water strategies [5]. Local content requirements now shape award decisions as much as technical merit.


Mechanical Seals Market By Region, 2025-2035

Competitive Benchmarking

Concentration in the Mechanical Seals Market is moderate. The top five suppliers together hold an estimated 42–46% of global revenue, producing an approximate HHI in the 700–900 band — consolidated enough that specification decisions cluster around a handful of qualified names, fragmented enough that regional manufacturers thrive in commodity duties. Competition turns on qualification credentials, service network density, and face-material capability rather than list price.

Company Est. Revenue Share Range Key Offerings for Mechanical Seals Market Strategic Positioning
John Crane (Smiths Group) ~11–14% Dry-gas, cartridge and support systems Broadest critical-service portfolio; strong service network
EagleBurgmann ~10–13% Engineered pump and compressor sealing Deep European process-industry incumbency
Flowserve ~8–11% Integrated pump and sealing packages Leverages pump OEM position for attach rates
AESSEAL ~5–7% Split and cartridge assemblies Fast delivery model; strong water and general industry
Trelleborg Sealing Solutions ~4–6% Polymer and hybrid sealing components Materials specialist across mixed applications
Parker Hannifin ~3–5% Sealing components and systems Diversified motion-control channel reach
Freudenberg Sealing Technologies ~3–5% Engineered elastomeric and mechanical sealing Automotive-adjacent scale in materials
A.W. Chesterton ~2–4% Seals plus reliability services Service-led differentiation
Eagle Industry ~2–4% Precision seals for machinery and marine Japanese OEM alignment
Meccanotecnica Umbra ~2–3% Standard and custom mechanical seals Cost-competitive European manufacturing
Garlock (EnPro Industries) ~1–3% Sealing and gasketing systems Broad industrial sealing adjacency
James Walker ~1–3% High-specification and cryogenic sealing Niche extreme-duty specialist


Recent News & Developments

  • U.S. EPA (March 2024): Finalised methane rules covering pump and compressor emissions at oil and gas facilities, accelerating dual-seal retrofit demand across North America [6]
  • European Union (April 2024): Adopted the revised Industrial Emissions Directive, extending emission-control obligations to additional process installations and tightening documentation requirements [8]
  • John Crane (September 2024): Expanded its diagnostics platform with additional condition-monitoring channels for barrier fluid systems, deepening the service-contract proposition [12]
  • AESSEAL (June 2024): Commissioned new manufacturing capacity in India to shorten lead times for the Mechanical Seals Market across South Asia [13]
  • Flowserve (February 2025): Announced a decarbonisation-focused product programme covering sealing for CO2 and hydrogen compression duties [3]
  • EagleBurgmann (November 2024): Completed qualification testing of gas-lubricated arrangements for hydrogen blending service at European utility sites [3]
  • Saudi Aramco (January 2025): Advanced the Jafurah gas programme with additional processing train awards, expanding qualified-vendor sealing demand in the Gulf [5]
  • API (2024): Continued balloting activity on sealing standard revisions, reinforcing the compliance-driven upgrade cycle for hydrocarbon service equipment [4]


Mechanical Seals Market Report Scope

Parameter Detail
Market Scope Global mechanical sealing hardware and associated support systems for pumps, compressors and mixers
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 4.9% (2026–2035)
Market Size Checkpoints USD 8.15 Billion (2025); USD 8.55 Billion (2026); USD 13.15 Billion (2035)
Fastest Growing Segments Compressor Seals; Power Generation; Asia-Pacific
Companies Profiled 12 leading suppliers across global and regional tiers
Valuation Currency USD Billion

FAQs

How should procurement teams evaluate total cost of ownership in the Mechanical Seals Market?
Compare installed life, mean-time-between-repair, and barrier system energy draw — not purchase price. Life-cycle studies show acquisition cost typically represents under 15% of total spend over a pump's service life [15].
What certifications matter most when qualifying a new sealing supplier?
Look for ISO 21049 conformity, documented API 682 category and arrangement compliance, and third-party material traceability. Nuclear and marine duties add code-specific approvals that generalist suppliers rarely hold [21].
How do OEM and aftermarket channels differ across the Mechanical Seals Market?
OEM fitment prioritises cost and standardisation, so component designs dominate. Aftermarket buyers optimise for reliability and installation speed, which pushes them toward cartridge and split formats at higher unit values [15].
What lead-time risks should Mechanical Seals Market buyers plan around?
Hard-face materials drive delays. Carbide and coated face stock runs on long production cycles, so engineered assemblies commonly quote eight to fourteen weeks against two weeks for standard components [10].
Can existing sealing systems be adapted for hydrogen blending?
Rarely without modification. Hydrogen's small molecular size and low lubricity demand revised face pairings and barrier gas arrangements, and most operators require fresh qualification testing before commissioning [3].
What contractual protections work against premature seal failure?
Negotiate guaranteed mean-time-between-repair thresholds with credit remedies rather than simple warranty replacement. Tie payment milestones to demonstrated running hours, and require root-cause analysis on every failure [12].
Does condition monitoring justify its cost on general-service pumps?
Usually not. Monitoring pays back on critical and hazardous duties where unplanned shutdown costs exceed six figures per event; general-service pumps remain economically served by scheduled replacement [12].      
Author
Author
Author Profile
Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry associations, technical standards organizations, and authoritative engineering publications. Key sources included the International Organization for Standardization (ISO) – specifically ISO 21049/API 682 standards for mechanical seals, American Petroleum Institute (API), American Society of Mechanical Engineers (ASME), European Sealing Association (ESA), Fluid Sealing Association (FSA), U.S. Department of Energy (DOE) Office of Energy Efficiency & Renewable Energy, International Energy Agency (IEA), U.S. Environmental Protection Agency (EPA), Occupational Safety and Health Administration (OSHA), European Chemical Industry Council (Cefic), World Energy Council, BP Statistical Review of World Energy, U.S. Energy Information Administration (EIA), International Renewable Energy Agency (IRENA), Process Equipment Manufacturers' Association (PEMA), and national industrial statistics bureaus from key manufacturing markets. These sources were used to collect equipment installation data, regulatory compliance standards, material performance studies, industry capacity trends, and competitive landscape analysis for component seals, cartridge seals, carbon/graphite/ceramic/metal seal technologies, and end-user industry adoption patterns.


Primary Research

During the primary research process, both supply-side and demand-side stakeholders were interviewed to gather qualitative and quantitative insights. Mechanical seal manufacturers, pump OEMs, and compressor OEMs all had supply-side sources, such as CEOs, VPs of Engineering, global product line directors, and heads of aftermarket service. Reliability engineers, maintenance managers, and procurement directors from oil and gas companies, chemical processing plants, power utilities, water treatment plants, and food processing companies were some of the demand-side sources. Primary research confirmed market segmentation, confirmed product development roadmaps, and gathered information on replacement cycle patterns, total cost of ownership metrics, and specification standards by industry vertical.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Region: North America (32%), Europe (29%), Asia-Pacific (34%), Rest of World (5%)


Market Size Estimation

Global market valuation was derived through revenue mapping and equipment installation base analysis. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across component seals, cartridge seals, unitized seals, and buffer seal categories

Analysis of reported and modeled annual revenues specific to mechanical seal portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (installed base × replacement rate × ASP by industry) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















