Lwan Market Summary
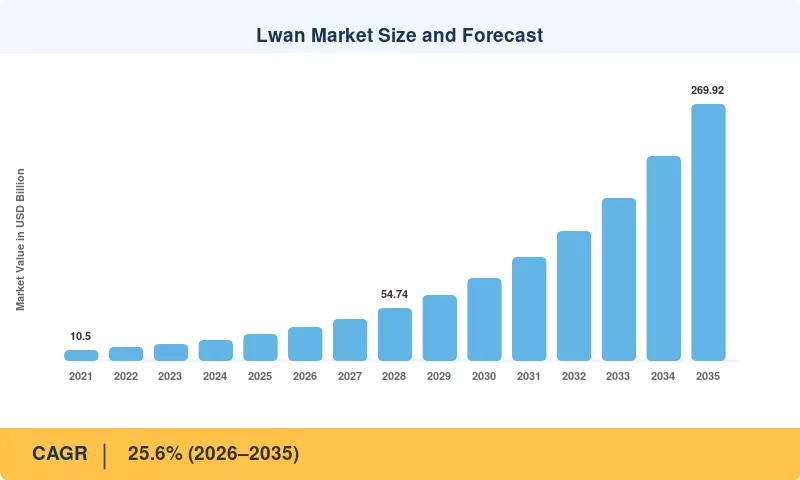
The Lwan Market was valued at USD 27.80 Billion in 2025 and is projected to reach USD 34.70 Billion in 2026, climbing to USD 269.92 Billion by 2035 at a CAGR of 25.6% over 2026–2035. Two catalysts anchor this trajectory. India's Revamped Distribution Sector Scheme commits roughly USD 36 billion to replace 250 million conventional electricity meters with smart prepaid units [6], while the U.S. Department of Energy's USD 10.5 billion Grid Resilience and Innovation Partnerships program funds utility telemetry at scale [7]. Both programs lean heavily on low-power wide area networks to connect millions of battery-powered endpoints at a per-device cost that cellular broadband cannot match.
Underneath the headline numbers, the technology stack is being rebuilt. Legacy 2G and 3G machine connections, drive-by meter reading and proprietary mesh radios are giving way to standardized LoRa, NB-IoT, LTE-M and, increasingly, 5G RedCap links. The 3GPP Release 17 and Release 18 specifications formalized reduced-capability 5G devices [2][3], and Semtech's certified RedCap module cuts power draw by about 65% compared with LTE alternatives [11]. That efficiency gain matters because device batteries, not radio chips, usually determine field lifetime.
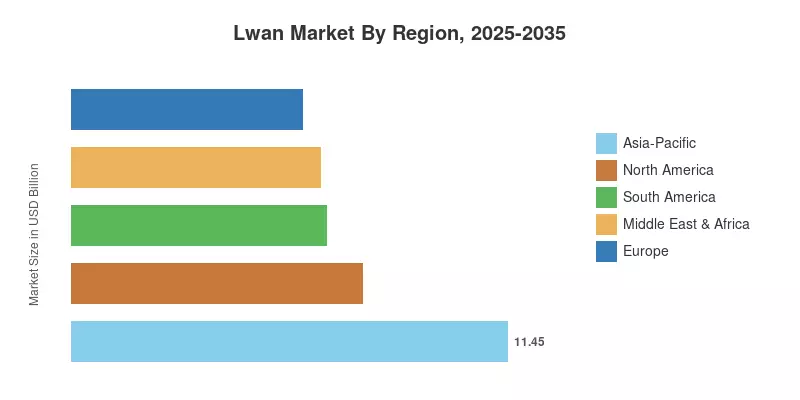
Asia-Pacific leads with a 41.2% share in 2025 and also records the fastest regional growth, propelled by Chinese NB-IoT mandates and Indian metering tenders [9][6]. North America ranks second, supported by CBRS-based private networks and remote patient monitoring reimbursement [17][12]. Europe follows closely on the back of smart-metering obligations [5]. Over the forecast decade, competitive advantage in the Lwan Market will shift from radio coverage toward platforms that manage devices, data and security across mixed protocols.
Key Report Takeaways
• By Network Technology
- LoRa held a 34.6% share of the Lwan Market in 2025, supported by low-cost gateways and unlicensed spectrum
- 5G RedCap is the fastest-growing technology, expanding at a 26.9% CAGR through 2035
- NB-IoT accounted for a 17.3% share, anchored by China's operator-led metering rollouts
• By Component
- Hardware (Modules, Gateways, Antennas) captured a 44.2% share in 2025 as utilities and cities expanded installed bases
- Platform revenue grows at a 27.6% CAGR as buyers consolidate device management and analytics
• By Deployment Model
- Public Network deployments represented a 56.4% share in 2025
- Private/Enterprise Network demand rises at a 28.1% CAGR, led by manufacturing and hospitals
• By End-User Industry
- Utilities held a 24.2% share in 2025, the largest of any vertical in the Lwan Market
- Healthcare posts a 26.7% CAGR as remote patient monitoring moves into routine care
- Smart City Infrastructure generated USD 4.17 Billion in 2025
• By Region
- Asia-Pacific commanded a 41.2% share in 2025
- North America generated USD 7.65 Billion in 2025
- South America grows at a 24.1% CAGR, driven by Brazilian utility modernization
Market Size and Forecast (2021–2035)
Market Research Future built the Lwan Market estimates from a bottom-up model of connected-device shipments, module and gateway average selling prices and recurring connectivity and platform fees, cross-checked against operator disclosures, vendor annual reports and public tender data [11][16][23][24][25]. Historical values for 2021–2024 reflect reported deployments; 2025 is the base year; 2026–2035 values are forecast at a constant compound rate.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



