Laboratory Proficiency Testing Market (2026 - 2035)

Laboratory Proficiency Testing Market Research Report By Test Type (Biological, Chemical, Forensic, Microbiological, Other), By Lab Accreditations (CAP 15189, ISO 17025, CLIA, Other), By Lab Size (Small Laboratories (1-5 employees), Medium Laboratories (6-10 employees), Large Laboratories (11+ employees)), By Application (Clinical Diagnostics, Environmental Monitoring, Food Safety, Research and Development, Other) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast 2025 To 2035

Forecast Period
2026-2035
CAGR
6.6%
2025 Market Size
USD 1.69 Billion
2035 Market Size
USD 3.20 Billion
Healthcare ● Updated August 24, 2026 Report ID: MRFR/HC/24623-HCR | Pages: 128 | Author: Satyendra Maurya, Rahul Gotadki

Laboratory Proficiency Testing Market Summary

The Laboratory Proficiency Testing Market was valued at USD 1.69 Billion in 2025 and opens the forecast window at USD 1.80 Billion in 2026, climbing to USD 3.20 Billion by 2035 at a 6.6% CAGR. Two catalysts explain the slope. Revised CLIA grading criteria for blood alcohol and blood lead analytes, effective January 2025, tightened allowable error bands across roughly 260,000 certified U.S. testing sites [1]. In parallel, the EPA's Clean Water Act Methods Update Rule added validated PFAS procedures that laboratories cannot claim competence in without documented external quality assessment [2].

Technology is the second story. Legacy dry-chemistry and manual titration schemes, which anchored scheme design for three decades, are giving way to PCR panels, digital droplet platforms and cell-based potency assays where inter-laboratory variance runs materially higher. Providers have responded with commutable matrix materials and cloud scoring engines; Bio-Rad and LGC together committed more than USD 140 million to quality-systems digitisation between 2023 and 2025 [3]. That spending reframes the Laboratory Proficiency Testing Market as an operations lever rather than a filing obligation.

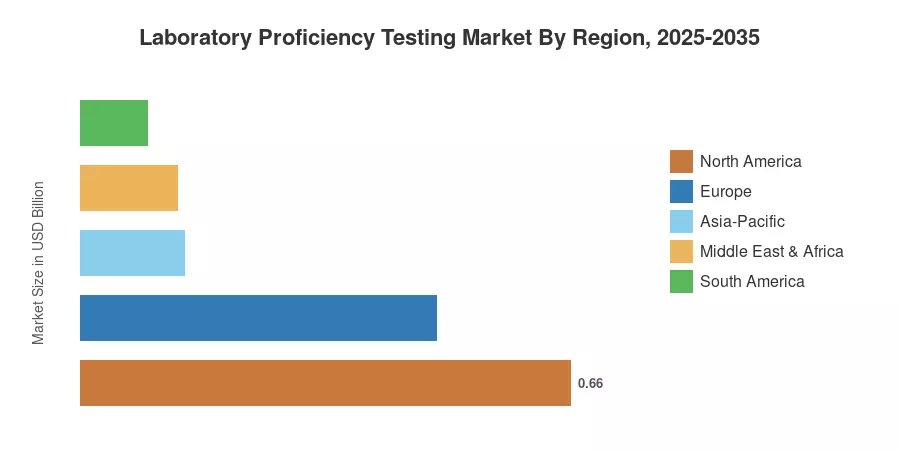
Regionally, North America held 39.0% of the Laboratory Proficiency Testing Market in 2025 on the strength of CLIA and CAP enrolment volumes. Asia-Pacific advances fastest at an 8.5% CAGR as India's NABL and China's CNAS expand accredited scopes. Europe sits second at 28.5%, propelled by ISO 15189 transition deadlines. Expect scheme consolidation to accelerate well before 2030.


Key Report Takeaways

• By Technology

  • Cell Culture-based Assays held 25.2% of the Laboratory Proficiency Testing Market in 2025, reflecting biologics potency workload.
  • PCR & Molecular Methods are advancing at a 7.4% CAGR through 2035 as syndromic panels proliferate
  • Chromatography schemes generated USD 0.35 billion in 2025 revenue, led by residue and contaminant panels.

• By Industry

  • Clinical Diagnostics commanded 35.5% share of the Laboratory Proficiency Testing Market in 2025
  • Pharmaceutical & Biologics is the fastest-growing industry vertical at a 7.8% CAGR to 2035
  • Food & Beverage Testing contributed USD 0.26 Billion in 2025 under FDA LAAF pressure.

• By Region

  • North America accounted for 39.0% of global revenue in 2025
  • Asia-Pacific is projected to post an 8.5% CAGR through 2035, the fastest of any region
  • Europe generated USD 0.48 Billion in 2025 across accredited scheme enrolments


Market Size and Forecast (2021–2035)

Estimates blend accreditation-body enrolment registries, provider revenue disclosures, scheme-level pricing surveys across 41 countries, and bottom-up modelling of accredited laboratory counts. Historical years reconcile against audited filings from listed participants; forecast years apply enrolment elasticity to accreditation growth. Every figure in the Laboratory Proficiency Testing Market series is expressed in USD Billion at 2025 constant prices.
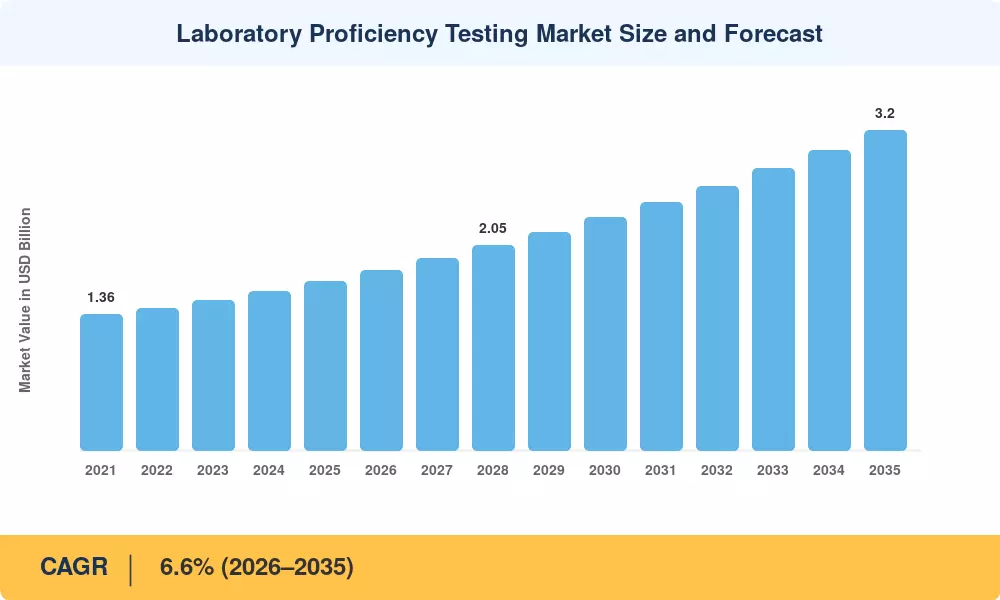
Laboratory Proficiency Testing Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Revised CLIA analyte grading criteria +0.9 North America Short-term (≤2 yr)
EPA PFAS methods under CWA Methods Update Rule +0.8 North America, Europe Medium-term (2–4 yr)
FDA LAAF accreditation for food testing +0.7 Global Medium-term (2–4 yr)
ISO/IEC 17025 and ISO 15189 scope expansion in Asia +1.1 Asia-Pacific Long-term (≥4 yr)
Migration to molecular and cell-based assay formats +0.9 Global Long-term (≥4 yr)
Digital scheme platforms and automated analytics +0.6 Global Medium-term (2–4 yr)
Cannabis and novel-food testing mandates +0.4 North America, Europe Short-term (≤2 yr)


Regulatory Tightening in Clinical Chemistry

CMS memorandum QSO-25-10-CLIA narrowed acceptance limits for blood lead to ±2 µg/dL or 10%, whichever is greater, forcing thousands of hospital and reference laboratories to re-validate instrument calibration and buy supplementary challenge rounds [1]. Failure carries real cost: a single unsuccessful analyte cycle triggers corrective action documentation, and two consecutive failures can suspend Medicare billing for that test. Providers repriced accordingly, and clinical scheme revenue inside the Laboratory Proficiency Testing Market rose faster than enrolment counts during 2025.

PFAS and Environmental Method Expansion

Environmental laboratories carry the heaviest new-method burden. EPA Methods 1633 and 1621 introduced 40 target analytes at parts-per-trillion sensitivity, and accredited scopes now demand documented performance evidence before a laboratory may report regulatory data [2]. State drinking-water programmes in California, New Jersey and Michigan added their own confirmation rounds. Scheme providers responded with quarterly PFAS challenge sets priced 30–45% above conventional metals panels.

Accreditation Growth Across Asia-Pacific

India's National Accreditation Board for Testing and Calibration Laboratories crossed 9,400 accredited facilities in 2025, roughly double its 2019 base, while CNAS in China now recognises more than 15,000 conformity-assessment bodies [7]. Accreditation is the gating mechanism for scheme participation — every new certificate creates a recurring annual obligation. That structural link explains why Asia-Pacific outpaces mature regions by nearly two percentage points of annual growth.

Assay Complexity and Method Migration

Molecular and cell-based workflows generate wider inter-laboratory dispersion than classical chemistry, so regulators mandate more frequent verification. WHO's biologics guidance and the pharmacopoeial move toward relative potency reporting both push sponsors toward multi-round participation [8]. Complexity also raises the per-round price ceiling, because commutable cell-based materials cost several times what lyophilised serum pools cost to produce.


Restraints Impact Analysis

Restraint weightings reflect analyst assessment of demand suppression and pricing drag. Values are directional indicators of relative severity within the Laboratory Proficiency Testing Market, not deductions applied to the compound growth rate.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Public-health laboratory budget compression −0.6 North America, Europe Short-term (≤2 yr)
Scheme fragmentation and duplicate enrolment cost −0.5 Global Medium-term (2–4 yr)
Scarcity of accredited reference-material producers −0.4 Asia-Pacific, MEA Long-term (≥4 yr)
Cold-chain and customs friction on sample shipment −0.3 MEA, South America Medium-term (2–4 yr)
Slow harmonisation of matrix-matched criteria −0.4 Global Long-term (≥4 yr)


Budget Pressure on Public Laboratories

Federal public-health preparedness funding in the United States fell roughly 11% in real terms between FY2023 and FY2025, and state laboratory directors have reported cutting discretionary quality spending first [10]. Because scheme enrolment is annual and renewable, it becomes an easy line item to trim to the regulatory minimum. That behaviour caps volume growth in the Laboratory Proficiency Testing Market even while regulatory intensity rises.


Fragmented Scheme Landscape

In order to satisfy several certification authorities, laboratories that operate internationally often enroll in three or four overlapping schemes. EURACHEM guidelines nevertheless allow national authorities to designate local suppliers, while ILAC mutual-recognition agreements minimize but do not completely eliminate redundancy [11]. Procurement teams are pushing back on renewal prices more and more since duplicate spend provides no additional analytical assurance.


Reference Material Supply Constraints

Fewer than 40 producers worldwide hold ISO 17034 accreditation for the matrices most in demand — whole blood, complex food homogenates and biological potency standards [12]. Lead times of 14 to 20 weeks are common. Supply scarcity constrains how quickly providers can launch new challenge panels in emerging geographies, which throttles the addressable base in exactly the regions growing fastest.


Laboratory Proficiency Testing Market Opportunities

Digital Scoring and Benchmarking Platforms

A compliance transaction is transformed into a continuous performance dashboard by cloud submission portals with real-time Z-score visualization. Subscription premiums of 20–30% over paper-based cycles may be charged by providers who reveal peer-group comparators [3]. There is still a lot of headroom because adoption is still less than half of enrolled locations.


Data Monetisation and Analytics Services

Payers assessing network quality and instrument manufacturers rating platform stability can both profit from aggregated, de-identified performance data from hundreds of laboratories. Two of the biggest scheme operators currently have licenses for anonymized method-comparison datasets. This causes the Laboratory Proficiency Testing Market's revenue mix to change from round-by-round fees to recurring analytics contracts.


Emerging-Market Scheme Localisation

Africa's accredited laboratory base grew at double-digit rates through the SANAS and AFRAC networks, yet most participants still import challenge materials at punitive freight cost [13]. Regionally manufactured, climate-stable matrices priced for local budgets represent an unserved pocket. Similar logic applies across ASEAN and Andean markets.

Cell and Gene Therapy Potency Verification

No mature scheme yet covers viral vector titre or CAR-T potency at scale, though more than 2,000 advanced-therapy trials were active globally in 2025 [8]. First movers can set methodological precedent and lock in sponsor relationships. This is the highest-margin white space in the Laboratory Proficiency Testing Market today.

Bundled Accreditation Support

Small laboratories struggle with corrective-action documentation more than with the analytics itself. Bundling root-cause templates, training modules and audit-ready records with challenge rounds raises attach rates and switching costs.


Laboratory Proficiency Testing Market Future Outlook

Autonomous Result Interpretation

Before a lab fails a round, machine-learning scoring will forecast instrument drift instead of just highlighting outliers. Repeat corrective interventions have decreased by 20–25%, according to providers testing predictive models [3]. Subscription analytics should make up a sizable portion of the Laboratory Proficiency Testing Market's earnings by the early 2030s.


Platform Economics and Scheme Consolidation

Expect diverse life-science groups to continue acquiring specialist providers due to fixed costs in material manufacture and the accreditation maintenance incentive scale. As digital distribution becomes the norm, sub-scale operators with fewer than 1,500 participants will experience margin compression [11].


Decentralised and Point-of-Care Verification

Near-patient testing devices already handle a growing share of clinical volume, yet current scheme design assumes centralised laboratory workflows. Adapting challenge materials to cartridge-based analysers is a solvable engineering problem with a large installed base behind it [8].

Traceability and Sustainability Reporting

Freight-intensive material distribution sits awkwardly with corporate emissions targets, and large hospital networks now request supplier carbon disclosures. Regional manufacturing and lyophilised, ambient-stable formats reduce both cost and footprint — a rare alignment of economics and ESG that should reshape distribution across the Laboratory Proficiency Testing Market by 2032 [14].


Laboratory Proficiency Testing Market Segmentation

Segment structure across the Laboratory Proficiency Testing Market follows the taxonomy accreditation bodies themselves use, which keeps enrolment data comparable across jurisdictions.

By Industry Type

Segment Metric (2025) Primary Demand Driver
Clinical Diagnostics 35.5% share CLIA and ISO 15189 mandates
Microbiology 18.2% share Sterility and pathogen detection verification
Pharmaceutical & Biologics 7.8% CAGR GMP release testing and potency assays
Food & Beverage Testing USD 0.26 Billion FDA LAAF and export certification
Environmental Testing 6.9% CAGR PFAS and effluent monitoring rules
Others USD 0.14 Billion Forensic, petrochemical and materials testing


Clinical Diagnostics dominates the Laboratory Proficiency Testing Market because participation is legally compulsory across most developed regulatory regimes, producing predictable annual renewals at high retention. Pharmaceutical & Biologics grows fastest for the opposite reason — participation is voluntary but competitively necessary, and biologics assays require more rounds per method than small-molecule chemistry. Sponsors running comparability studies for biosimilars typically enrol in four to six distinct challenge categories.

By Technology

Segment Metric (2025) Primary Demand Driver
Cell Culture-based Assays 25.2% share Biologics potency and sterility verification
Chromatography USD 0.35 Billion Residue, impurity and contaminant panels
Immunoassays 18.6% share Hormone, serology and marker testing
PCR & Molecular Methods 7.4% CAGR Syndromic panels and oncology profiling
Spectrophotometry 6.1% CAGR Metals, water quality and clinical chemistry
Others USD 0.13 Billion Mass spectrometry, flow cytometry, sequencing


Cell culture formats lead on share because potency and sterility work carries the highest regulatory scrutiny per test and the widest inherent variability. Molecular methods grow fastest as laboratories replace single-target PCR with multiplex panels that require analyte-by-analyte verification rather than a single competence demonstration. Chromatography holds steady value on the strength of food and environmental residue schemes.

By Provider Type

Segment Metric (2025) Primary Demand Driver
Independent / Third-Party Providers 50.2% share Vendor-neutral credibility with accreditors
Instrument-Manufacturer Programs USD 0.36 Billion Bundled platform support contracts
Government / Regulatory Bodies 7.2% CAGR National reference laboratory mandates
Academic & Professional Associations 12.4% share Specialty discipline schemes


Buyers prefer vendor-neutral schemes because assessors scrutinise conflicts of interest when a manufacturer grades performance on its own platform. Manufacturer programmes survive where they are bundled into service agreements at negligible incremental cost. Government schemes grow quickly in Asia-Pacific and Africa, where national reference laboratories are being funded to serve as domestic providers.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 39.0% share CLIA regrade compliance, PFAS panels
Europe USD 0.48 Billion ISO 15189 transition, food authenticity
Asia-Pacific 8.5% CAGR (2026–2035) Accreditation scope expansion, local material production
South America 5.6% share Agricultural residue testing, ANVISA alignment
Middle East & Africa 7.7% CAGR (2026–2035) Public-health capacity building, water quality
Total USD 1.69 Billion

Geographic performance across the Laboratory Proficiency Testing Market tracks accreditation density far more closely than it tracks GDP. Mature regulatory regimes deliver volume; expanding accreditation regimes deliver growth.


North America

Country Metric (2025) Key Driver
US 82.4% of region CLIA analyte regrade and CAP enrolment volume
Canada USD 0.07 Billion IQMH scheme consolidation across provinces
Mexico 6.8% CAGR EMA accreditation growth in food export testing


American demand is structurally inelastic because participation is statutory rather than discretionary. CAP alone administers surveys covering more than 20,000 laboratories, and the 2025 grading revision forced supplementary enrolment in toxicology and trace-metals categories [1]. Canadian volumes concentrate in Ontario and Quebec, where provincial accreditation is mandatory for hospital laboratories. Mexico's growth stems from USMCA food-export verification rather than clinical testing, making it the most sector-skewed national market in the Laboratory Proficiency Testing Market.

Europe

Country Metric (2025) Key Driver
Germany 23.1% of region DAkkS-driven ISO 15189 conversion
UK USD 0.09 Billion UKAS medical laboratory accreditation
France 6.4% CAGR COFRAC mandatory clinical accreditation
Italy 10.2% of region Regional health authority quality audits
Spain USD 0.03 Billion Food and agricultural residue verification
Nordic Countries 5.9% CAGR Environmental and water testing scope growth
Russia 4.8% of region State laboratory network standardisation
Rest of Europe USD 0.05 Billion CEE accreditation catch-up


France remains the strictest jurisdiction: COFRAC requires full accreditation for every clinical laboratory activity, a mandate no other large European state matches. Germany's volume advantage comes from the sheer count of accredited environmental and industrial testing sites rather than clinical density. The ISO 15189:2022 transition deadline concentrated a wave of gap-assessment work into 2026 and 2027, pulling scheme purchases forward across the region [5].

Asia-Pacific

Country Metric (2025) Key Driver
China 30.6% of region CNAS conformity-assessment body expansion
India 9.8% CAGR NABL accreditation doubling, pharma export QC
Japan USD 0.07 Billion JAB clinical and pharmacopoeial alignment
South Korea 9.1% of region KOLAS scope growth in biologics
ASEAN 8.9% CAGR Food safety harmonisation under AFSRB
Rest of Asia-Pacific USD 0.03 Billion Donor-funded laboratory strengthening


India is the single most consequential growth engine in the regional Laboratory Proficiency Testing Market. Pharmaceutical exporters facing FDA and EMA inspection risk treat scheme participation as insurance, and NABL's accredited base expansion translates almost mechanically into recurring enrolments [7]. China's volume is larger but grows more slowly because domestic providers compete aggressively on price. Korean demand skews toward biosimilar potency work.

South America

Country Metric (2025) Key Driver
Brazil 56.3% of region ANVISA and INMETRO accreditation requirements
Argentina USD 0.02 Billion Agricultural export residue certification
Rest of South America 6.5% CAGR Andean mining and water testing programmes


Brazilian agribusiness exports drive the region's residue and mycotoxin scheme demand, with INMETRO-accredited laboratories required to demonstrate ongoing competence for EU-bound shipments [9]. Currency volatility complicates multi-year contracting, so providers increasingly quote in local currency with annual reset clauses. Chilean and Peruvian mining laboratories represent the fastest sub-national pocket.

Middle East & Africa

Country Metric (2025) Key Driver
Saudi Arabia 27.4% of region SFDA laboratory capacity under Vision 2030
UAE USD 0.02 Billion EIAC accreditation and food import screening
South Africa 7.7% CAGR SANAS clinical and water testing expansion
Egypt 11.2% of region EGAC pharmaceutical and food verification
Rest of MEA USD 0.02 Billion Donor-funded diagnostic network programmes


Gulf states are building laboratory infrastructure faster than they are building quality-assurance depth, creating a lag that scheme providers are actively courting. South Africa's SANAS network anchors sub-Saharan participation and increasingly acts as a regional hub for material distribution [13]. Freight cost and customs clearance for temperature-controlled shipments remain the binding constraint across much of the continent.


Laboratory Proficiency Testing Market By Region, 2025-2035

Competitive Benchmarking

Concentration in the Laboratory Proficiency Testing Market is moderate. Estimated HHI sits near 780, with the top five participants holding roughly 44–48% of global revenue and a long tail of national and discipline-specific providers holding the remainder. Fragmentation persists because accreditation bodies recognise local schemes, protecting regional incumbents from displacement even when global operators offer superior analytics.

Company Est. Revenue Share Range Key Offerings for Laboratory Proficiency Testing Market Strategic Positioning
LGC Standards ~11–14% AXIO, QNM and Elevate schemes; reference materials Broadest multi-sector portfolio; ISO 17034 depth
Bio-Rad Laboratories ~9–12% Unity quality control, EQAS clinical schemes Clinical chemistry scale with integrated QC data
Merck KGaA ~7–10% Supelco challenge sets; certified standards Chromatography and analytical chemistry strength
Thermo Fisher Scientific ~6–9% Clinical and environmental scheme portfolios Bundles with installed instrument base
College of American Pathologists ~6–8% Surveys and anatomic pathology programmes Accreditor-linked credibility in US clinical labs
American Proficiency Institute ~4–6% Clinical laboratory challenge modules Cost-competitive CLIA-focused alternative
Randox Laboratories ~4–6% RIQAS international clinical schemes Strong emerging-market distribution footprint
Fera Science (FAPAS) ~3–5% Food, feed and water challenge materials Recognised authority in food authenticity
Waters Corporation ~3–5% Separation science verification programmes Method-linked pharmaceutical positioning
Eurofins Scientific ~2–4% Environmental and food scheme operations Leverages global testing network for matrices
NSI Lab Solutions ~2–3% Water and environmental challenge samples Specialist depth in US drinking-water rules
Phenova (Antylia Scientific) ~2–3% Environmental and PFAS study programmes Early mover on ultra-trace PFAS panels


Recent News & Developments

  • Centers for Medicare & Medicaid Services (January 2025): Revised CLIA acceptance criteria for blood lead and blood alcohol took effect, raising precision requirements and driving supplementary enrolment across US clinical laboratories [1]
  • US Environmental Protection Agency (August 2024): Finalised Clean Water Act method updates incorporating PFAS procedures, creating new mandatory verification categories for effluent laboratories [2]
  • LGC Standards (March 2024): Expanded its AXIO clinical portfolio with cell-based potency challenge sets aimed at biologics manufacturers, targeting the fastest-growing industry vertical [3]
  • Randox Laboratories (September 2024): Extended RIQAS distribution partnerships across the Gulf Cooperation Council, adding regional material staging to cut delivery lead times [13]
  • International Organization for Standardization (December 2023): Publication and phased rollout of ISO 15189:2022 accelerated gap assessments and scheme purchasing across European clinical laboratories [5]
  • US Food and Drug Administration (June 2024): Expanded recognition under the Laboratory Accreditation for Analyses of Foods programme, widening the accredited base subject to competence verification [6]
  • Bio-Rad Laboratories (November 2025): Launched an integrated analytics layer linking daily quality-control data with external challenge results for trend-based failure prediction [3]
  • National Accreditation Board for Testing and Calibration Laboratories, India (April 2025): Surpassed 9,400 accredited facilities, expanding the addressable enrolment base across pharmaceutical and food testing [7]


Laboratory Proficiency Testing Market Report Scope

Parameter Detail
Market Scope Global Laboratory Proficiency Testing Market by industry type, technology, provider type and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.6% (2026–2035)
Market Size Checkpoints USD 1.69 Billion (2025); USD 1.80 Billion (2026); USD 3.20 Billion (2035)
Fastest Growing Segments Pharmaceutical & Biologics (industry); PCR & Molecular Methods (technology); Asia-Pacific (region)
Companies Profiled 12 leading providers including LGC Standards, Bio-Rad Laboratories, Merck KGaA, Thermo Fisher Scientific, College of American Pathologists, Randox Laboratories
Valuation Currency USD Billion, 2025 constant prices

FAQs

How should a procurement team evaluate providers in the Laboratory Proficiency Testing Market?
Prioritise ISO 17043 accreditation scope, matrix commutability, and turnaround from submission to report. Ask for participant counts per analyte — thin peer groups produce unstable Z-scores regardless of provider reputation [11].
Does scheme participation reduce accreditation audit findings?
Yes, measurably. Laboratories with documented multi-round histories face fewer competence-related nonconformities during assessment, because assessors accept performance evidence in place of extended technical review [4].
What integration challenges arise when adopting digital platforms in the Laboratory Proficiency Testing Market?
LIMS-to-portal mapping is the main friction point, since analyte codes rarely align out of the box. Budget four to eight weeks for validation and mapping work per instrument family [3].
Are manufacturer-run schemes acceptable to accreditation bodies?
Generally yes, provided the scheme itself holds ISO 17043 accreditation. Some assessors still request supplementary vendor-neutral evidence where the manufacturer supplies both the analyser and the grading [11].
Which niches in the Laboratory Proficiency Testing Market carry the strongest pricing power?
Cell and gene therapy potency, ultra-trace PFAS, and forensic toxicology. Each combines scarce reference materials with regulatory consequence, letting providers price two to four times conventional clinical rounds [8].
How do laboratories handle analytes with no available scheme?
Alternative performance assessment applies: split-sample exchange with a peer facility, or spiked-recovery studies against certified materials. Both require documented acceptance criteria agreed before testing [16].
What is the realistic cost of a failed round?
Direct re-enrolment is minor; corrective action is not. Staff time, root-cause investigation and possible retesting typically consume 40 to 80 hours per failed analyte in mid-sized clinical facilities [15].    
Author
Author
Author Profile
Satyendra Maurya LinkedIn Research Analyst
An accomplished research analyst with high proficiency in market forecasting, data visualization, competitive benchmarking, and others. He holds a pronounced track record in research and consulting projects for sectors such as life sciences, medical devices, and healthcare IT. His capabilities in qualitative and quantitative analysis have resulted in positive client outcomes. Working on niche market trends, opportunities, sales, and forecasted value is part of his skill set.
Co-Author
Co-Author Profile
Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed scientific journals, clinical laboratory publications, and authoritative health and standardization organizations. Key sources included the US Centers for Medicare & Medicaid Services (CMS), Clinical Laboratory Improvement Amendments (CLIA) Program, College of American Pathologists (CAP), International Organization for Standardization (ISO), European Committee for Standardization (CEN), European Accreditation (EA), UK National External Quality Assessment Service (UK NEQAS), American Association for Laboratory Accreditation (A2LA), National Institute of Standards and Technology (NIST), Centers for Disease Control and Prevention (CDC), Food and Drug Administration (FDA), European Medicines Agency (EMA), World Health Organization (WHO) Essential Diagnostics List, International Laboratory Accreditation Cooperation (ILAC), Clinical and Laboratory Standards Institute (CLSI), National Institutes of Health (NIH/NCBI PubMed), OECD Health Statistics, EU Eurostat Health Database, and national health ministry reports from key markets. These sources were used to collect laboratory accreditation statistics, regulatory compliance data, quality assurance studies, testing volume trends, and market landscape analysis for biological, chemical, forensic, and microbiological proficiency testing programs.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. From proficiency testing providers, diagnostic manufacturers, and laboratory accreditation authorities, supply-side sources comprised CEOs, VPs of Quality Assurance, regulatory affairs heads, and commercial directors. Laboratory directors, quality managers, medical technologists, and procurement leads from clinical diagnostic laboratories, hospital laboratories, reference laboratories, environmental testing facilities, food safety laboratories, and research institutions constituted demand-side sources. Market segmentation was validated, proficiency testing program timelines were confirmed, and insights on laboratory adoption patterns, pricing strategies, and accreditation compliance dynamics were garnered through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (38%), Europe (25%), Asia-Pacific (28%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through revenue mapping and proficiency testing program volume analysis. The methodology included:

Identification of 40+ key proficiency testing providers across North America, Europe, Asia-Pacific, and Latin America

Service mapping across biological, chemical, forensic, microbiological, and other specialized testing categories

Analysis of reported and modeled annual revenues specific to proficiency testing portfolios

Coverage of providers representing 70-75% of global market share in 2024

Extrapolation using bottom-up (program participation × ASP by country) and top-down (provider revenue validation) approaches to derive segment-specific valuations

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















