Immunohistochemistry Market (2026 - 2035)

Immunohistochemistry Market Research Report: Size, Share, Trend Analysis By Product (Antibodies (Primary antibodies, and Secondary antibodies), Reagents (Histological Stains, Blocking Sera), Equipment (Slide-staining Systems, Tissue Processing Systems, Slide Scanners) By Applications (Diagnostic applications (Cancer, Infectious diseases, Autoimmune diseases) By End Users (Hospitals & Diagnostic Laboratories, Academic & Research Institutes), And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) –Competitor Industry Analysis and Trends Forecast Till 2035

Forecast Period
2026-2035
CAGR
7.25%
2025 Market Size
USD 3.21 billion (2025)
2035 Market Size
USD 6.46 billion (2035)
Life Sciences ● Updated August 24, 2026 Report ID: MRFR/LS/19924-HCR | Pages: 128 | Author: Nidhi Mandole, Rahul Gotadki

Immunohistochemistry Market Summary

The Global Immunohistochemistry Market size was valued at USD 3.21 Billion in 2025, and the market is projected to grow from USD 3.44 Billion in 2026 to USD 6.46 Billion by 2035, registering a CAGR of 7.25% during the forecast period 2026–2035. Two forces drive that trajectory: the global cancer burden—WHO estimated 20 million new cases in 2023 alone [1]—and the widening mandate for companion diagnostic testing before targeted-therapy prescriptions, which health authorities in the US, EU, and Japan now require across an expanding list of solid-tumor indications [2].

Laboratories that formerly depended on manual chromogenic staining are quickly transitioning to automated, high-throughput slide-staining machines capable of processing 200 or more slides each run. The incorporation of digital pathology is accelerating this transformation; in 2024, the CAP published updated guidelines supporting the use of AI-assisted grading for HER2 and PD-L1 biomarkers [3]. This need is further augmented by investments in drug-development outsourcing. Contract research businesses as a group are expected to invest more than USD 1.8 billion in histopathology services between 2023 and 2025.


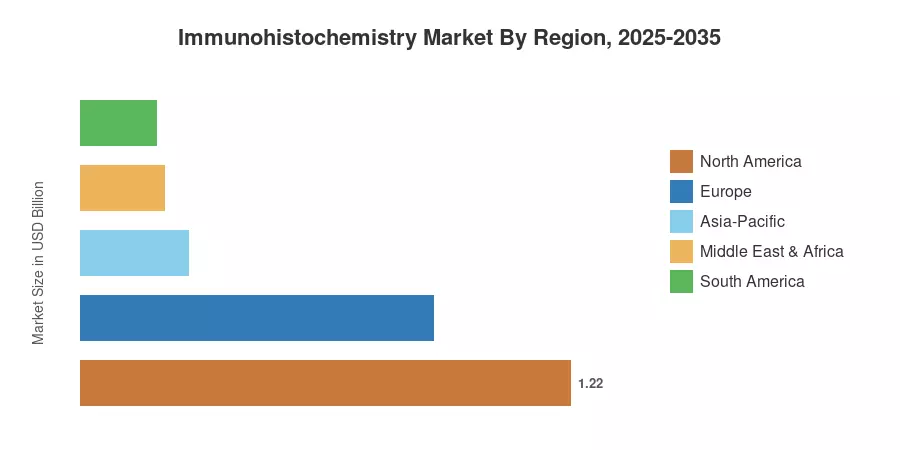
The Immunohistochemistry Market is dominated by North America, with 37.9% of the 2025 revenue, propelled by broad insurer coverage and a foundation of installed advanced staining systems. The fastest-growing region is Asia-Pacific, which is expected to develop at a CAGR of 8.47% to 2035, thanks to the growing pathology infrastructure in China and the growing network of recognized diagnostic laboratories in India. Europe represents 27.5% of worldwide revenue and has the second-largest position. Emerging economies are anticipated to adhere to precision-medicine mandates, and the Immunohistochemistry Market is set to have prolonged double-digit regional growth pockets through the mid-2030s.


Key Report Takeaways

• By Product

  • Antibodies commanded 38.6% of the Immunohistochemistry Market in 2025, underpinned by continuous catalog expansion of monoclonal and recombinant antibody clones.
  • Equipment revenues are forecast to reach USD 1.14 billion by 2035, reflecting laboratory automation investments.
  • Software solutions are projected to expand at an 8.18% CAGR through 2035, the fastest among product sub-segments.

• By Application

  • Diagnostics held a 56.5% share of the Immunohistochemistry Market in 2025, sustained by oncology biomarker panel expansion.
  • Drug discovery and testing are advancing at an 8.34% CAGR, fueled by biopharma outsourcing and immuno-oncology pipelines.

• By Geography

  • North America led with 37.9% revenue share in 2025.
  • Asia-Pacific is expected to register the highest CAGR at 8.47% between 2026 and 2035.


Market Size and Forecast (2021–2035)

Market Research Future (MRFR) leverages a combination of bottom-up and top-down approaches, triangulating supplier revenues, trade-association shipment data and end-user procurement surveys across 30+ countries. Historical figures are sourced from verified corporate filings and customs databases, and prospective forecasts are at the segment level, regression, adjusted for macro-economic and regulatory factors. All figures are in 2025 USD billion constant.
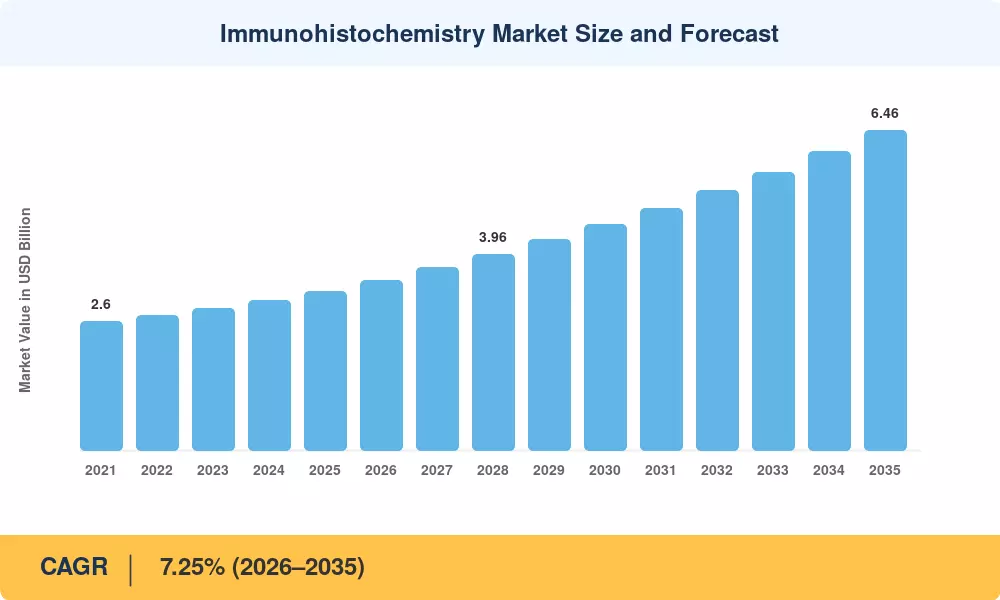
Immunohistochemistry Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising global cancer incidence +1.6% Global Long-term
Companion-diagnostics regulatory mandates +1.3% North America, Europe Medium-term
AI-enabled digital pathology integration +1.1% North America, Asia-Pacific Medium-term
Laboratory automation in middle-income countries +0.9% Asia-Pacific, South America Long-term
Immuno-oncology drug pipeline expansion +0.8% Global Short-term
Recombinant antibody technology advancement +0.7% Europe, North America Medium-term
CRO histopathology outsourcing growth +0.6% Global Short-term


Rising Global Cancer Incidence

GLOBOCAN 2023 data reported roughly 20 million new cancer cases worldwide, a figure projected to approach 27.5 million by 2035 [1]. Every malignant-tissue specimen entering a pathology workflow requires at least one—and frequently four to six—IHC biomarker tests for classification and therapy selection. This volume effect remains the single largest structural growth engine for the Immunohistochemistry Market, providing a durable demand floor irrespective of technology cycles.

Companion-Diagnostics Regulatory Mandates

The regulatory landscape for IHC is becoming increasingly stringent, particularly in the European Union. With the full enforcement of the In Vitro Diagnostic Regulation (IVDR) as of May 2026, many diagnostic assays have been reclassified into higher-risk categories. This shift mandates rigorous clinical evidence and oversight by Notified Bodies, which effectively increases the barrier to entry. For manufacturers, this favors validated, commercial-grade IHC kits over laboratory-developed tests (LDTs). Similarly, the FDA continues to expand the list of cleared companion diagnostic (CDx) devices, reinforcing the role of standardized IHC platforms in modern clinical oncology.


AI-Enabled Digital Pathology Integration

The digital pathology market is undergoing steady expansion, with the global market size projected to grow at a compound annual growth rate (CAGR) of over 12% through 2033. Healthcare networks are increasingly adopting whole-slide imaging (WSI) scanners and image management systems to streamline pathology workflows, reduce physical slide handling, and enable remote consultation. While the industry is moving toward AI-assisted interpretation, adoption is currently focused on high-throughput environments and research-led institutions. Hospitals are integrating these tools primarily to improve diagnostic consistency and operational efficiency, with payers beginning to evaluate reimbursement frameworks for AI-supported diagnostic interpretation.


Laboratory Automation in Middle-Income Countries

Emerging economies are prioritizing the modernization of their laboratory infrastructure to manage the rising prevalence of chronic diseases. In China, government-led "Smart Hospital" and "Internet + Healthcare" initiatives, supported by the 15th Five-Year Plan, are accelerating the adoption of digital pathology and automated diagnostic platforms to address the shortage of trained pathologists. Similarly, India’s digital health missions are driving investment into modernized pathology networks. These public-investment waves are fueling "greenfield" demand for automated IHC stainers and digital infrastructure in regions that are transitioning away from manual, legacy workflows toward standardized, high-capacity diagnostic systems.


Restraints Impact Analysis

Negative-impact estimates below reflect restraining pressure on the headline CAGR and are derived from regulatory-cost modeling, supply-chain surveys, and clinical-adoption barrier analyses. They do not subtract linearly from the growth rate.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High cost of validated antibody clones –0.7% Global Long-term
Stringent IVDR / FDA device reclassification compliance –0.6% Europe, North America Medium-term
Pre-analytical variability in tissue fixation –0.5% Global Long-term
Shortage of trained histopathologists –0.4% Asia-Pacific, Africa Long-term
Reimbursement uncertainty for multiplex panels –0.3% North America, Europe Short-term


High Cost of Validated Antibody Clones

A single diagnostic-grade primary antibody clone can cost USD 350–700 per 1 mL vial, and laboratories running 15-marker oncology panels face annual reagent bills exceeding USD 200,000 [14]. For resource-limited settings, these costs restrict adoption to high-volume reference laboratories, limiting the addressable Immunohistochemistry Market in low- and lower-middle-income countries. Antibody shelf-life constraints further inflate effective per-test costs when specimen throughput is low.

IVDR and FDA Device Reclassification Compliance

Europe's IVDR transition reclassified IHC kits from self-certified Class A to Class C or D devices, requiring clinical-performance studies and notified-body audits [15]. The FDA's parallel reclassification of certain IHC assays as Class II medical devices adds 510(k) submission timelines averaging 9–14 months. Compliance costs—estimated at USD 1.2–3.5 million per assay—disproportionately burden mid-size reagent manufacturers and slow innovation velocity in the Immunohistochemistry Market.

Shortage of Trained Histopathologists

The Royal College of Pathologists reported a 32% vacancy rate across NHS histopathology departments in 2024 [17]. Sub-Saharan Africa averages fewer than one pathologist per million population. While AI-assisted scoring alleviates part of this bottleneck, human oversight remains mandatory for final diagnostic sign-off in virtually every regulatory jurisdiction, constraining how quickly new IHC testing volume can ramp.


Immunohistochemistry Market Opportunities

Multiplex IHC for Spatial Biology Research

Spatial proteomics is transitioning from niche academic curiosity to a mainstream translational-research tool. Multiplex IHC platforms capable of staining 40-plus biomarkers on a single tissue section are unlocking immuno-oncology insights that single-plex assays cannot provide [7]. Pharmaceutical companies increasingly require spatial-biomarker data for clinical-trial patient stratification, opening a high-value service opportunity within the Immunohistochemistry Market.

Point-of-Care Rapid IHC Testing

Microfluidic cartridge-based IHC prototypes demonstrated 20-minute staining-to-result workflows at USCAP 2024, suggesting that intraoperative margin assessment could shift from frozen-section H&E to rapid IHC biomarker confirmation [11]. If validated at scale, point-of-care IHC would address surgical-suite demand currently unmet by centralized laboratory workflows and create an entirely new revenue stream.

Emerging-Market Laboratory Build-Outs

Africa's diagnostic-laboratory base is projected to grow 45% between 2025 and 2035, driven by Global Fund, PEPFAR, and World Bank pathology-infrastructure grants [8]. Countries such as Nigeria, Kenya, and Ethiopia are establishing national cancer-registry programs that mandate IHC-confirmed histological diagnosis, converting latent diagnostic need into active procurement.

Software-as-a-Service Image-Analysis Platforms

Cloud-based IHC image-analysis platforms are moving to subscription pricing, reducing upfront capital expenditure for smaller laboratories. SaaS models—priced at USD 1,500–4,000 per seat per year—allow laboratories to access AI-driven biomarker scoring without purchasing dedicated workstations [3]. This business model shift expands the addressable customer base for the Immunohistochemistry Market and creates recurring revenue streams for software developers.

Veterinary Pathology Expansion

Companion-animal oncology referrals rose 18% year-over-year in 2024, and veterinary diagnostic laboratories are adopting IHC panels for lymphoma sub-typing and mast-cell grading [19]. While still a small fraction of overall market revenue, veterinary pathology represents a high-growth adjacency with limited competitive saturation.


Immunohistochemistry Market Future Outlook

AI-Driven Autonomous Pathology Workflows

By 2030, integrated AI platforms are expected to manage end-to-end IHC workflows—from slide scanning through biomarker scoring to report generation—with minimal human intervention. estimates that AI-enabled pathology could reduce diagnostic labor costs by 25–35% across high-volume laboratories [3]. Regulatory bodies are developing performance-based approval frameworks specifically for AI-IHC decision-support systems, which will progressively unlock autonomous sign-off authority for routine biomarker panels in the Immunohistochemistry Market.

Spatial Biology and the Multiplex Staining Supercycle

The shift from single-plex chromogenic assays to 40-plus-marker multiplex fluorescence panels represents a technology supercycle comparable to the genomics transition from Sanger sequencing to next-generation platforms. The spatial-biology instrument segment alone is forecast to exceed USD 900 million by 2032 [7]. As pharmaceutical sponsors embed spatial IHC data into regulatory submissions, clinical-trial-grade multiplex staining will become a non-negotiable capability for reference laboratories serving the Immunohistochemistry Market.

Sustainability in Reagent Manufacturing

Mounting ESG reporting requirements are pushing reagent manufacturers toward solvent-free formulations, recyclable packaging, and lower-energy cold-chain logistics. Roche Diagnostics is committed to a 50% reduction in Scope 1 and 2 emissions from its diagnostic-reagent plants by 2030 [12]. Laboratories making procurement decisions increasingly weigh environmental certifications alongside technical performance, meaning sustainability credentials will become competitive differentiators across the Immunohistochemistry Market.

Decentralized Pathology Networks

Telemedicine-enabled pathology networks—where peripheral clinics digitize IHC slides and transmit images to centralized expert readers—are gaining traction in underserved regions. WHO's 2024 roadmap for laboratory strengthening endorses hub-and-spoke telepathology as a scalable model for low-resource settings [17]. These networks expand the addressable end-user base for IHC reagents and instruments without requiring every facility to employ an on-site pathologist.


Immunohistochemistry Market Segmentation

By Product

Segment Key Metric Primary Demand Driver
Antibodies (Primary Antibodies, Secondary Antibodies) 38.6% share (2025) Expanding biomarker test menus
Equipment USD 1.14 billion (2035) Automation of staining workflows
Software 8.18% CAGR (2026–2035) AI-based image analysis adoption
Reagents & Kits USD 0.52 billion (2025) Pre-validated, ready-to-use kit formats


Antibodies remain the backbone of the Immunohistochemistry Market, with primary antibodies constituting the largest expenditure line as laboratories adopt broader oncopanels. Recombinant monoclonal clones are displacing polyclonal alternatives due to superior batch-to-batch consistency, a shift that is lifting average selling prices. The segment's dominance reflects the fundamental biology of IHC: every assay requires at least one target-specific antibody, making reagent demand directly proportional to test volume.

Software is the fastest-growing product category, powered by cloud-hosted image-analysis platforms that enable quantitative biomarker scoring. Vendor strategies increasingly bundle software licenses with instrument placements, creating recurring revenue streams and reducing the hardware-replacement cycle's impact on top-line growth within the Immunohistochemistry Market.

By Application

Segment Key Metric Primary Demand Driver
Diagnostics 56.5% share (2025) Regulatory-mandated companion diagnostics
Drug Discovery and Testing 8.34% CAGR (2026–2035) Immuno-oncology pipeline expansion


Diagnostics dominates application-level revenue because every oncology pathology workflow incorporates IHC as a standard step in tumor classification. The Immunohistochemistry Market benefits from a growing list of FDA-cleared and CE-marked CDx assays that mandate IHC-based biomarker verification before prescribing targeted therapies. Drug discovery and testing, while smaller in absolute terms, is growing faster as CROs expand tissue-analysis capabilities to serve biopharma clients conducting immuno-oncology clinical trials across dozens of indication areas.

By Detection Method

Segment Key Metric Primary Demand Driver
Indirect Immunohistochemistry 65.5% share (2025) Signal amplification for low-abundance targets
Direct Immunohistochemistry 7.92% CAGR (2026–2035) Simplified protocols for high-throughput labs


Indirect detection methods dominate the Immunohistochemistry Market because signal amplification via secondary-antibody layering delivers the sensitivity required for low-abundance biomarkers. Direct methods, though simpler and faster, are gaining share as conjugated primary antibodies with improved fluorophore brightness reduce the need for amplification in high-throughput reference laboratories.

By End User

Segment Key Metric Primary Demand Driver
Hospitals and Diagnostic Centers 51.8% share (2025) Routine surgical-pathology volume
Academic and Research Institutes 8.38% CAGR (2026–2035) Grant-funded spatial biology research
Pharmaceutical & Biotech Companies USD 0.48 billion (2025) In-house tissue-analysis capabilities


Hospitals and diagnostic centers represent the largest end-user segment within the Immunohistochemistry Market, processing millions of surgical-biopsy and resection specimens annually. Academic institutes post the fastest growth rate as spatial-proteomics research grants from NIH, ERC, and JSPS fund high-plex IHC instrument installations.


Regional Market Share Analysis

Region Key Metric (2025) Primary Investment Themes
North America 37.9% revenue share CDx mandates, AI pathology, laboratory consolidation
Europe 27.5% revenue share IVDR compliance, academic research funding
Asia-Pacific 8.47% CAGR (2026–2035) Hospital-lab upgrades, manufacturing capacity
South America USD 0.19 billion Public-health program expansion
Middle East & Africa USD 0.21 billion Cancer-registry establishment, donor-funded labs
Total USD 3.21 billion

The Immunohistochemistry Market exhibits pronounced geographic concentration, with North America and Europe collectively accounting for over 65% of 2025 revenue. Asia-Pacific, however, is reshaping the competitive map, with capacity build-outs and expanding oncology infrastructure underpinning the fastest regional CAGR.


North America

Country Key Metric Key Driver
US 78.4% of regional share Medicare CDx reimbursement expansion
Canada 13.1% of regional share Provincial cancer-program standardization
Mexico 8.52% CAGR (2026–2035) IMSS laboratory modernization initiative


The United States dominates the North American Immunohistochemistry Market, supported by the highest per-capita pathology utilization globally and a regulatory environment that continuously expands the CDx-required biomarker list. CMS reimbursement for IHC panels increased by an average 6.2% across CPT codes 88342–88344 in the 2025 physician fee schedule [2]. Canada's interprovincial cancer-strategy alignment is driving uniform IHC test-menu adoption across all ten provinces.

Europe

Country Key Metric Key Driver
Germany 23.8% of regional share University-hospital digitalization programs
UK 19.5% of regional share NHS Genomic Medicine Service integration
France 7.12% CAGR (2026–2035) Plan France Médecine Génomique 2025+
Italy USD 0.12 billion (2025) National oncology-network IHC standardization
Spain 6.95% CAGR (2026–2035) ISCIII precision-medicine grants
Nordic Countries USD 0.09 billion (2025) Cross-border pathology-sharing platforms
Russia 7.35% CAGR (2026–2035) Federal oncology center expansion
Rest of Europe USD 0.11 billion (2025) EU Horizon Europe research grants


Europe's Immunohistochemistry Market is shaped by IVDR enforcement, which is consolidating reagent procurement toward globally certified manufacturers. Germany and the UK together control over 43% of regional revenue, leveraging extensive academic hospital networks and mature digital-pathology infrastructure.

Asia-Pacific

Country Key Metric Key Driver
China 34.2% of regional share National Health Commission lab-upgrade program
India 9.18% CAGR (2026–2035) Ayushman Bharat diagnostic expansion
Japan 22.5% of regional share PMDA companion-diagnostics approvals
South Korea 8.74% CAGR (2026–2035) MOHW precision-oncology investment
ASEAN USD 0.08 billion (2025) Regional cancer-center build-outs
Rest of Asia-Pacific 7.91% CAGR (2026–2035) Bilateral aid-funded pathology programs


Asia-Pacific is the fastest-growing region within the Immunohistochemistry Market, propelled by China's USD 2.4 billion county-hospital upgrade program and India's target of deploying 1,200 new pathology-enabled health centers by 2028 [8]. Japan's established regulatory pathway for companion diagnostics and South Korea's national precision-oncology initiative provide high-value growth anchors.

South America

Country Key Metric Key Driver
Brazil 56.3% of regional share SUS oncology-pathway IHC requirements
Argentina 7.48% CAGR (2026–2035) National Cancer Institute modernization
Rest of South America USD 0.04 billion (2025) PAHO laboratory-strengthening grants


Brazil accounts for the majority of South American demand, driven by the Unified Health System's expanding oncology-diagnostic protocols that mandate IHC testing for breast, lung, and colorectal cancer staging. Argentina's national cancer institute is investing in automated staining capacity to reduce dependence on manual laboratory workflows.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 28.5% of regional share Vision 2030 healthcare-city development
UAE 7.82% CAGR (2026–2035) Medical-tourism diagnostic-excellence strategy
South Africa 22.1% of regional share NHLS reference-laboratory expansion
Egypt 8.04% CAGR (2026–2035) Universal health-insurance rollout
Rest of MEA USD 0.05 billion (2025) Global Fund pathology-infrastructure grants


The Middle East & Africa region is building from a low base but growing rapidly as governments invest in cancer-registry programs and diagnostic infrastructure. Saudi Arabia's Medical City projects in Riyadh and Jeddah include state-of-the-art histopathology laboratories equipped with fully automated IHC staining lines.


Immunohistochemistry Market By Region, 2025-2035

Competitive Benchmarking

The Immunohistochemistry Market is moderately concentrated, with the top five players projected to account for around 55-60% of the global revenue. The Herfindahl-Hirschman Index is between 1,200 and 1,500, reflecting a market that is neither monopolistic nor totally fragmented. The strategy revolves around vertical integration or merging antibody portfolios, instrument platforms and digital-pathology software to provide comprehensive laboratory solutions.

Company Est. Revenue Share Range Key Offerings for the Immunohistochemistry Market Strategic Positioning
Roche Diagnostics (Ventana) ~14–17% VENTANA automated stainers, OptiView & UltraView detection kits Integrated diagnostics ecosystem leader
Danaher (Leica Biosystems / Abcam) ~12–15% BOND staining platforms, recombinant RabMAb antibodies End-to-end reagent-instrument-software portfolio
Agilent Technologies (Dako) ~10–13% Autostainer Link 48, EnVision FLEX detection systems Strong CDx assay partnerships
Thermo Fisher Scientific ~7–10% Invitrogen antibody catalog, Lab Vision autostainers Broadest antibody catalog coverage
Bio-Rad Laboratories ~4–6% Droplet-based multiplex platforms, IHC-grade antibodies Multiplex and quality-control niche
Merck KGaA (MilliporeSigma) ~3–5% Sigma-Aldrich antibody portfolio, IHC reagent kits Research-reagent depth
Cell Signaling Technology ~3–5% Validated SignalStain IHC kits, phospho-specific antibodies Translational-research focus
BioGenex ~2–4% Xmatrx automated stainers, tissue-microarray solutions Cost-competitive automation
PerkinElmer (Revvity) ~2–4% Opal multiplex fluorescence, Vectra imaging platform Spatial-biology pioneer
Sakura Finetek ~2–3% Tissue-Tek Prisma Stainers, embedding & processing instruments Specimen-preparation workflow


Recent News & Developments

  • Roche Diagnostics (October 2021): Received FDA clearance for a new PD-L1 (SP263) IHC companion-diagnostic assay targeting non-small-cell lung cancer checkpoint-inhibitor regimens, expanding the Immunohistochemistry Market CDx portfolio [2].


  • Cell Signaling Technology (January 2024): Released a 12-marker multiplex IHC panel for tumor-microenvironment profiling, validated on FFPE tissue across six solid-tumor types [7].
  • US FDA (September 2023): Published updated guidance on the analytical validation of IHC assays used as companion diagnostics, tightening performance-benchmark requirements [15].
  • Revvity (formerly PerkinElmer) (June 2023): Introduced the PhenoImager HT 2.0 spatial-biology platform with improved spectral unmixing for high-plex fluorescence IHC workflows [22].


Immunohistochemistry Market Report Scope

Item Detail
Market Scope Global Immunohistochemistry Market — products, applications, detection methods, end users, and 5 regions / 20+ countries
Study Period 2021–2035
CAGR (Forecast) 7.25% (2026–2035)
Base-Year Market Size USD 3.21 billion (2025)
Forecast-Endpoint Market Size USD 6.46 billion (2035)
Fastest Growing Product Segment Software (8.18% CAGR)
Fastest Growing Region Asia-Pacific (8.47% CAGR)
Companies Profiled 10 (Roche, Danaher, Agilent, Thermo Fisher, Bio-Rad, Merck KGaA, Cell Signaling Technology, BioGenex, Revvity, Sakura Finetek)
Valuation Currency USD billion

FAQs

How does multiplex IHC differ from standard single-marker chromogenic staining in clinical practice?
Multiplex IHC applies multiple antibodies simultaneously on one tissue section, enabling spatial co-localization of several biomarkers. Standard chromogenic staining visualizes only one target per slide, requiring serial sections and consuming more tissue [7].
What validation steps should a laboratory follow when switching primary-antibody vendors?
Labs must run parallel testing of the new and existing clones on 20–40 characterized tissue controls, comparing staining intensity, specificity, and concordance. Regulatory frameworks like CAP and IVDR require documented validation before clinical use [15].
How does IHC compare to flow cytometry for solid-tumor biomarker analysis?
IHC preserves tissue architecture, allowing pathologists to evaluate biomarker expression within a morphological context. Flow cytometry requires cell suspensions and works best for hematologic malignancies rather than solid-tissue specimens [16].
What pre-analytical fixation variables most affect IHC staining quality?
Formalin fixation duration between 6 and 72 hours and cold ischemia time before fixation are the primary variables. Under-fixation causes weak staining; over-fixation masks epitopes through excessive cross-linking [16].
Are IHC-based companion-diagnostic assays reimbursed uniformly across US payers?
Medicare reimburses IHC CDx under CPT codes 88342–88344 at national rates, but commercial payers vary by plan. Prior-authorization requirements for multi-marker panels remain inconsistent across insurers [18].
What emerging biomarkers are expanding IHC test menus beyond traditional oncology applications?
Neurodegenerative disease markers like phospho-tau and alpha-synuclein are entering clinical IHC workflows. Transplant-rejection grading using C4d staining is also gaining standardization across renal-pathology practice [21].
How do automated staining platforms reduce inter-operator variability compared to manual methods?
Automated platforms standardize incubation times, reagent volumes, and wash cycles, eliminating operator-dependent technique differences. Published studies report coefficient-of-variation reductions from 15–20% (manual) to under 5% (automated) [20].    
What is the current size of the immunohistochemistry market?
The immunohistochemistry market reached USD 3.21 billion in 2025 and is projected to reach USD 6.46 billion by 2035.
What is the CAGR of the immunohistochemistry market?
The immunohistochemistry market is projected to grow at a CAGR of 7.25% during the forecast period 2026–2035.
Which region leads the immunohistochemistry market?
North America holds the largest share at 37.9%, while Asia-Pacific is the fastest-growing region at 8.47% CAGR.
What is driving growth in the immunohistochemistry market?
Growth in the immunohistochemistry market is primarily driven by rising global cancer incidence and the expanding regulatory mandate for companion diagnostic testing alongside targeted-therapy prescriptions.
Author
Author
Author Profile
Nidhi Mandole LinkedIn Senior Research Analyst
She is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Nidhi is comfortably versed in data centric research backed by healthcare educational background. She leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. Her key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, she showcases extensive affinity towards learning new skills and remain fascinated in implementing them.
Co-Author
Co-Author Profile
Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed medical journals, clinical pathology publications, and authoritative healthcare organizations. Key sources included the US Food & Drug Administration (FDA), European Medicines Agency (EMA), Centers for Medicare & Medicaid Services (CMS), National Institutes of Health (NIH), National Cancer Institute (NCI), National Center for Biotechnology Information (NCBI/PubMed), Centers for Disease Control and Prevention (CDC), World Health Organization (WHO) Global Health Observatory, International Agency for Research on Cancer (IARC), College of American Pathologists (CAP), American Society of Clinical Pathology (ASCP), European Society of Pathology (ESP), International Society for Immunohistochemistry and Molecular Morphology (ISIMM), International Clinical Cytometry Society (ICCS), Association of Pathology Chairs (APC), National Pathology Quality Registry (NPQR), European Confederation of Medical Laboratory Associations (EC4), Organisation for Economic Co-operation and Development (OECD) Health Statistics, EU Eurostat Health Database, and national health ministry reports from key markets. These sources were used to collect pathology procedure statistics, regulatory approval data for IHC assays and antibodies, clinical diagnostic guidelines, cancer incidence and prevalence data, research funding trends, and market landscape analysis for antibodies (primary and secondary), reagents (histological stains, blocking sera), equipment (slide-staining systems, tissue processing systems, slide scanners), and diagnostic applications across cancer, infectious diseases, and autoimmune diseases.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of product development, heads of diagnostic reagents, heads of regulatory affairs, and commercial directors from manufacturers of immunohistochemistry reagents, antibody developers, OEMs of diagnostic equipment, and life sciences firms were examples of supply-side sources. Board-certified pathologists, clinical laboratory directors, histotechnologists, procurement leads from hospitals and diagnostic labs, principal investigators, core facility directors from academic and research institutions, and research scientists from pharmaceutical R&D departments were among the demand-side sources. Primary research gathered information on clinical adoption patterns of companion diagnostic assays, pricing strategies for antibody panels, reimbursement dynamics for IHC testing, and laboratory automation trends. It also validated market segmentation across product categories (antibodies, reagents, and equipment) and confirmed product pipeline timelines for multiplex IHC and automated platforms.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

By Region: North America (38%), Europe (25%), Asia-Pacific (28%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through revenue mapping and diagnostic procedure volume analysis. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America specializing in antibodies (primary antibodies, secondary antibodies), reagents (histological stains, blocking sera), and equipment (slide-staining systems, tissue processing systems, slide scanners)

Product mapping across IHC consumables, instruments, and software/digital pathology solutions

Analysis of reported and modeled annual revenues specific to immunohistochemistry portfolios, including antibody sales for diagnostic and research applications, reagent kits for cancer diagnostics, and automated staining platform revenues

Coverage of manufacturers representing 75-80% of global market share in 2024, including major players such as Roche (Ventana), Thermo Fisher Scientific, Agilent Technologies (Dako), Merck KGaA, Abcam, BioGenex, Cell Signaling Technology, Leica Biosystems (Danaher), and PerkinElmer

Extrapolation using bottom-up (diagnostic test volume × ASP by country, research antibody consumption × pricing by application) and top-down (manufacturer revenue validation, segment-wise growth correlation) approaches to derive product-specific and application-specific valuations

Validation against cancer diagnostic testing volumes, pathology laboratory automation adoption rates, and research funding allocations in immuno-oncology and biomarker discovery

Cross-reference with companion diagnostic market trends and personalized medicine adoption metrics to ensure comprehensive coverage of the diagnostic applications segment (cancer, infectious diseases, autoimmune diseases) and end-user segments (hospitals & diagnostic laboratories, academic & research institutes)

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















