Hemostats Market Summary
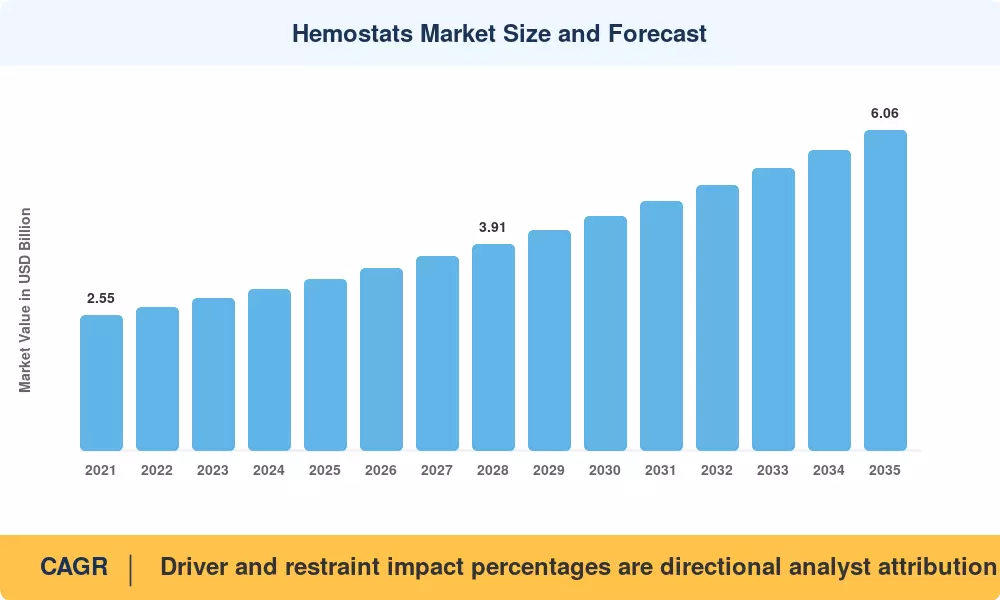
The Hemostats Market was valued at USD 3.24 billion in 2025 and opens the forecast window at USD 3.45 billion in 2026, climbing to USD 6.06 billion by 2035 at a 6.45% CAGR. Surgical volume recovery is the engine. The Australian Institute of Health and Welfare recorded 771,600 public-hospital elective surgery admissions in 2023–24, a 5% jump over the prior year [1], and comparable rebounds across OECD systems have pushed consumable reorder rates well past pre-2020 baselines [2]. Every additional procedure carries a bleeding-control line item, which is why the Hemostats Market tracks operating-room throughput more tightly than almost any other surgical consumable category.
Materials science is rewriting the category from the inside. Gauze, bone wax, and simple oxidized cellulose pads are ceding ground to biopolymer platforms — alginate, chitosan, and recombinant thrombin composites — engineered for faster clot initiation and predictable resorption. Research published in the International Journal of Biological Macromolecules in April 2024 documented materially shorter hemostasis times for sodium-alginate-treated wounds versus conventional dressings [3]. Manufacturers responded with capital: combined R&D and capacity spending across the top five suppliers exceeded USD 1.1 billion in 2024, much of it aimed at flowable and powder formats that reach irregular bleeding surfaces where topical hemostat products in sheet form underperform.
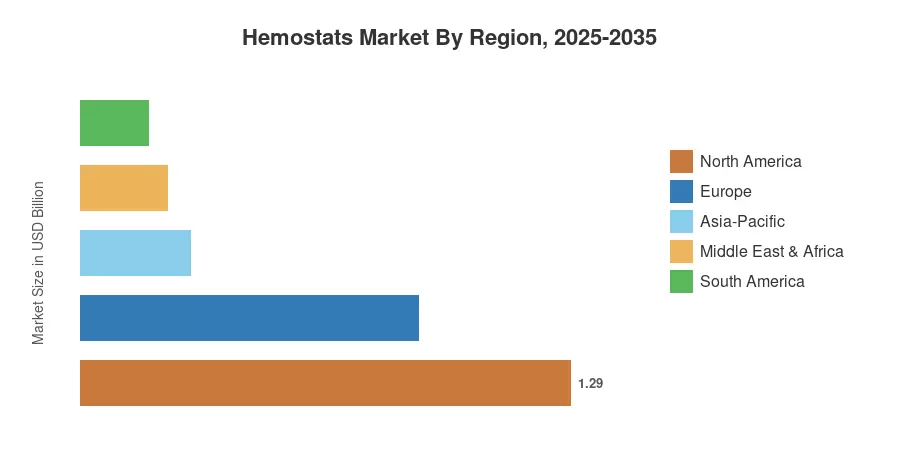
Geography splits along familiar lines. North America holds a 39.8% share of the Hemostats Market, anchored by high per-capita surgical intensity and premium reimbursement. Asia-Pacific grows fastest at an 8.9% CAGR through 2035, powered by hospital construction in China and India. Europe remains second-largest on share, though EU MDR recertification costs are slowing new SKU introductions [5]. The next decade belongs to whoever industrializes biologic hemostats at commodity cost.
Key Report Takeaways
• By Type
- Absorbable Hemostats command a 76.5% share of the Hemostats Market in 2025, reflecting surgeon preference for materials that need no retrieval step
- Non-Absorbable Hemostats post a 7.0% CAGR (2026–2035), sustained by trauma and military field-care demand
• By Application
- General Surgery accounts for 31.4% of application demand, the single largest procedural pool
- Cardiovascular Surgery represents USD 0.73 billion in 2025 revenue, the highest value-per-case segment
• By End User
- Ambulatory Surgical Centers expand at an 8.4% CAGR as case migration accelerates
• By Region
- North America leads the Hemostats Market with a 39.8% revenue share
- Asia-Pacific delivers the fastest regional expansion at 8.9% CAGR
- Europe contributes USD 0.89 billion in 2025
Market Size and Forecast (2021–2035)
Figures below blend supplier-reported surgical consumables revenue, national procedure registries, hospital group purchasing organization tender data, and customs-level trade flows for hemostatic device HS codes. Historical years are reconciled against audited segment disclosures from publicly listed suppliers; forecast years apply procedure-volume elasticity by region. The Hemostats Market series is expressed in constant 2025 US dollars.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



