Hazardous Area Equipment Market Summary
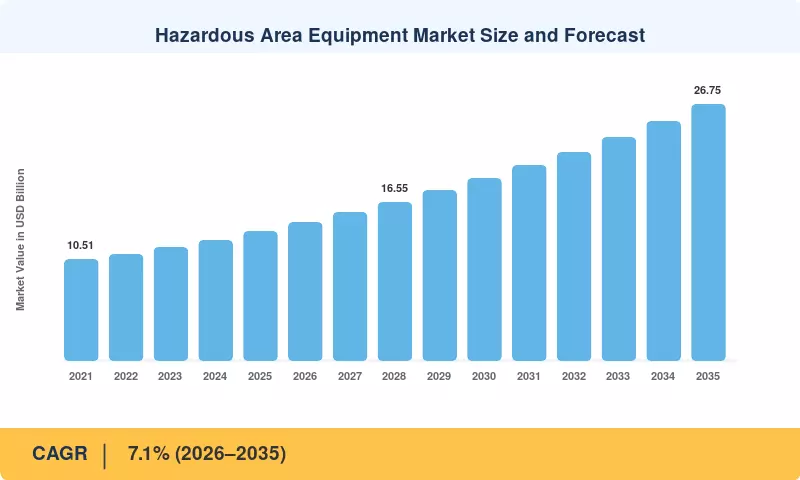
The Hazardous Area Equipment Market reached USD 13.47 billion in 2025 and opens the forecast window at USD 14.43 billion in 2026, climbing to USD 26.75 billion by 2035 at a 7.1% CAGR. Two catalysts anchor that trajectory. Global upstream capital spending returned to roughly USD 570 billion in 2025 after a decade of restraint [1], and the European Commission's continued enforcement of Directive 2014/34/EU has forced a certification refresh across thousands of Zone 1 and Zone 2 installations [6]. Both push certified hardware demand well past replacement rates.
Technology substitution is reshaping specification sheets. Flameproof fluorescent luminaires, hardwired analog loops, and pneumatic actuation are giving way to certified LED fixtures, wireless HART and WirelessHART instrumentation, and digitally addressable control nodes rated for explosive atmospheres. The U.S. Department of Energy's industrial decarbonization program, backed by roughly USD 6.3 billion in demonstration funding, has accelerated that swap in chemical and refining assets [8].
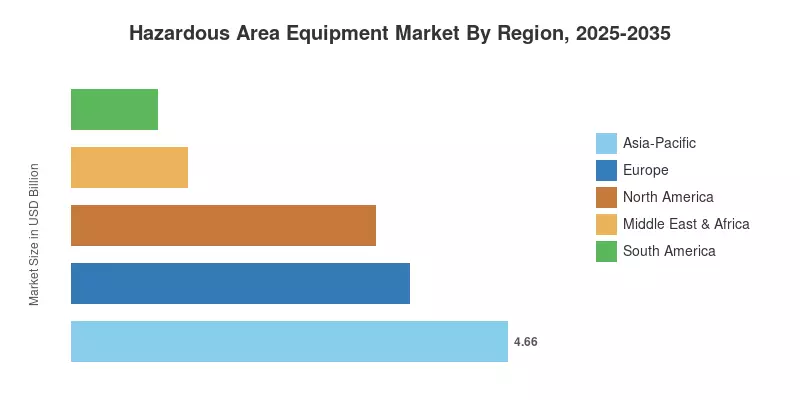
Asia-Pacific anchors the Hazardous Area Equipment Market with a 34.6% revenue share in 2025 and simultaneously grows fastest at 8.4% through 2035, driven by Chinese petrochemical capacity and Indian mining modernization. Europe follows at 26.8%, sustained by certification-led replacement rather than greenfield build. North America ranks third but leads in per-site spending intensity. Through the next decade, the Hazardous Area Equipment Market will be shaped less by new plant construction and more by the retrofit economics of aging, digitally underserved assets.
Key Report Takeaways
• By Equipment
- Automation and Control Products lead the Hazardous Area Equipment Market with a 29.8% revenue share in 2025, reflecting integrated Zone 1 control node adoption
- Enclosures post a 6.8% CAGR through 2035 as stainless and GRP housings displace cast aluminium in corrosive offshore duty
- Surveillance Systems reach USD 1.17 billion in 2025 on certified thermal and gas-imaging camera deployment
• By End-User Industry
- Oil and Gas holds 31.5% of the Hazardous Area Equipment Market, the largest single vertical
- Mining and Metals expands at an 8.6% CAGR, the fastest of any end-user, on underground safety mandates
- Chemical contributes USD 2.45 billion in 2025 revenue across batch and continuous process assets
• By Region
- Asia-Pacific commands 34.6% of global revenue in 2025
- Middle East & Africa records USD 1.24 billion, concentrated in Gulf upstream and downstream expansion
- Europe grows at 5.9% CAGR, the slowest major region, constrained by a mature installed base
Market Size and Forecast (2021–2035)
Figures below combine bottom-up equipment shipment tracking across eight product categories with top-down validation against certification body throughput data, published capital expenditure disclosures from 40 operators, and distributor sell-through sampling in 22 countries. Historical values are reconciled to reported segment revenues in vendor annual filings; forecast values apply certification-cycle replacement modeling layered onto announced project pipelines.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


