Globe Valve Market (2026 - 2035)

Globe Valve Market Research Report By End-User (Oil & Gas, Chemicals, Power & Energy, Water & Wastewater, Others) - Forecast to 2035
ID: MRFR/Equip/40853-HCR 200 Pages Aarti Dhapte Last Updated: October 05, 2026
Globe Valve Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)3.96%
2025 Market SizeUSD 8.62 Billion
2035 Market SizeUSD 12.71 Billion
Key Players
Emerson Electric Co.
Flowserve Corporation
SLB
IMI plc
KITZ Corporation
Velan Inc.
Opportunities
  • Emerging-Market Water and Industrial Projects
  • Diagnostics-as-a-Service and Data Monetization
  • Hydrogen and Carbon Capture Applications

Globe Valve Market Summary

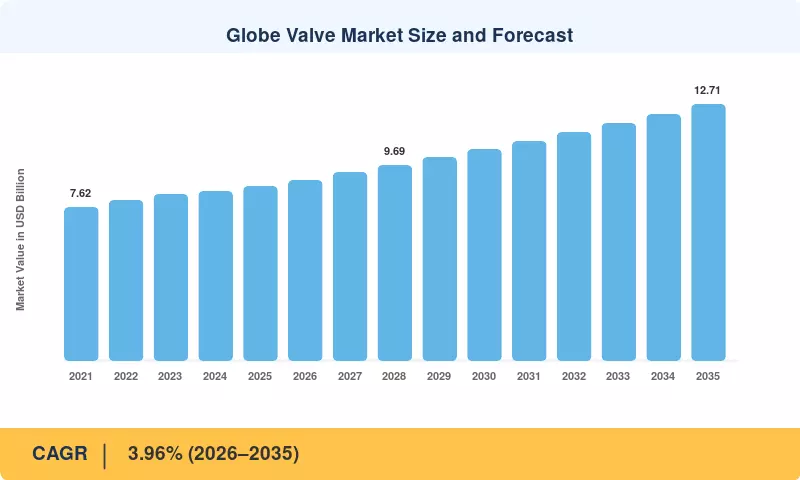
The Globe Valve Market was valued at USD 8.62 billion in 2025 and is projected to reach USD 8.96 billion in 2026, then climb to USD 12.71 billion by 2035 at a CAGR of 3.96% over 2026–2035. Two catalysts anchor that trajectory. Global upstream oil and gas spending reached roughly USD 570 billion in 2024 [1], sustaining demand for throttling valves on wellheads, separators, and gas processing trains. Separately, the U.S. Bipartisan Infrastructure Law committed about USD 55 billion to water and wastewater systems [3], opening a long municipal procurement cycle.

Buyers are replacing manually operated, graphite-packed valves with automated globe valves with digital positioners, low-emission packing (API 624 and ISO 15848-1 [5][6]) and onboard diagnostics. The U.S. EPA methane rule, which is projected to reduce around 58 million tons of methane from 2024 to 2038 [4], is expediting the replacement of leak-prone stems throughout oil and gas facilities. This is a value shift away from commodity castings and toward engineered trim, actuation and condition monitoring.


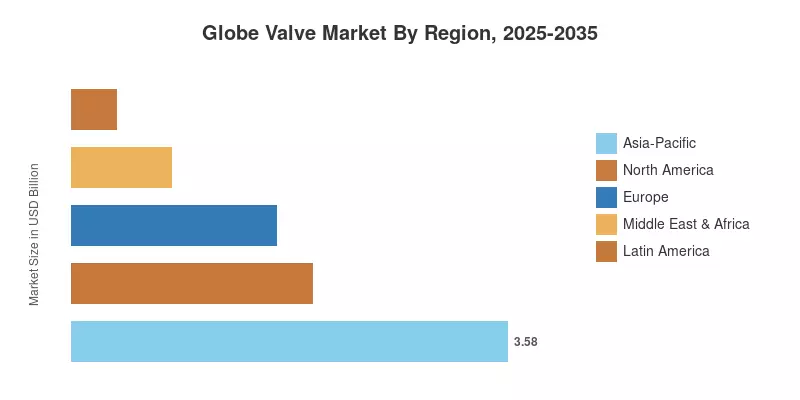
Asia-Pacific, the largest market for Globe Valves with a share of 41.5% in 2025, is the fastest-growing market with an anticipated CAGR of 4.8% driven by the investment in refining, chemicals and water in China and India. North America is second, buoyed by shale gas processing, LNG export facilities and federal water funding. The coming decade will see compliance-driven replacement matter as much as greenfield capacity.


Key Report Takeaways

• By End-User

  • Oil & Gas holds the largest position in the Globe Valve Market at a 33.5% share in 2025, driven by gas processing and LNG export capacity.
  • Water & Wastewater is the fastest-expanding end-user, growing at a 5.1% CAGR through 2035 as utilities modernize treatment and distribution networks.
  • Chemicals account for USD 1.55 billion in 2025, anchored by petrochemical integration projects in Asia.

• By Region

  • Asia-Pacific commands a 41.5% share of the Globe Valve Market, led by China's refining and chemical complexes.
  • North America represents USD 1.98 billion in 2025, supported by methane compliance retrofits and LNG build-out.
  • Latin America is set to grow at a 4.3% CAGR, aided by offshore upstream activity in Brazil and Guyana.

Market Size and Forecast (2021–2035)

The prediction was developed using bottom-up shipment projections across end-user sectors and was cross-referenced with manufacturer revenue disclosures [16][17], energy and water capital expenditure data [1][3], and interviews conducted by MRFR with valve distributors and EPC procurement teams. Historical values are recorded activity. Forecast values are a continuous growth path calibrated to project pipelines and regulatory timeframes.
Globe Valve Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Oil, gas, and LNG capital spending +0.9% North America, Middle East & Africa Medium-term (2–4 yr)
Methane and fugitive emission regulation +0.7% North America, Europe Short-term (≤2 yr)
Water and wastewater infrastructure funding +0.6% North America, Asia-Pacific Long-term (≥4 yr)
Process automation and valve diagnostics +0.5% Global Medium-term (2–4 yr)
Power generation build-out, including nuclear +0.4% Asia-Pacific, Europe Long-term (≥4 yr)
Chemical and refining capacity in Asia +0.4% Asia-Pacific Medium-term (2–4 yr)


Oil, Gas, and LNG Capital Spending

Upstream oil and gas investment held near USD 570 billion in 2024, according to the IEA [1]. Globe valves sit at the heart of choke, separator level, and gas dehydration control loops, so capex flows translate directly into orders. North American LNG export capacity is set to more than double between 2024 and 2028 [2], and each liquefaction train requires several thousand control and isolation valves, many in high-pressure or cryogenic globe configurations.

Methane and Fugitive Emission Regulation

The EPA's December 2023 methane rule targets roughly 58 million tons of avoided emissions through 2038 [4]. Europe followed with Regulation (EU) 2024/1787, which mandates leak detection and repair across oil and gas assets [7]. Operators are replacing stem-packed valves with units qualified to API 624 [5] and ISO 15848-1 [6]. Globe valves, with their rising stems, are a frequent leak source, which makes them a priority retrofit item.

Water and Wastewater Infrastructure Funding

About USD 55 billion in U.S. federal funding is flowing to drinking water, lead pipe removal, and wastewater upgrades [3]. India's Jal Jeevan Mission, with an outlay exceeding INR 3.6 lakh crore, has extended tap connections to well over 150 million rural households [8]. Treatment plants depend on globe valves for chemical dosing, filter backwash, and pressure regulation, giving this driver a long and predictable tail.

Process Automation and Valve Diagnostics

Plants are adding smart positioners that track valve travel, friction, and air supply in real time. Emerson reported more than USD 17 billion in fiscal 2024 sales, with its intelligent devices business citing strong control valve demand [16]. Diagnostic data lets operators move from scheduled overhauls to condition-based maintenance, cutting unplanned shutdowns and raising the value of each installed valve.

Power Generation Build-Out, Including Nuclear

More than 60 nuclear reactors were under construction worldwide in 2024, according to the IAEA [10]. Feedwater, steam bypass, and turbine control applications use severe-service globe valves rated for high temperature and pressure. Combined-cycle gas plants in Asia and the Middle East add parallel demand, and nuclear-grade valves carry premium pricing because of N-stamp qualification requirements.

Chemical and Refining Capacity in Asia

China added significant refining and ethylene capacity between 2021 and 2024, and the IEA projects petrochemicals will account for a growing share of oil demand growth through 2030 [11]. Integrated refinery-chemical complexes in Zhejiang, Guangdong, and Gujarat specify thousands of globe valves per site for corrosive and high-temperature service, keeping Asian order books full.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Fragmented regional certifications and standards −0.4% Global Long-term (≥4 yr)
Raw material and alloy price volatility −0.3% Global Short-term (≤2 yr)
Substitution by ball and butterfly valves −0.3% Global Long-term (≥4 yr)
Oil price cyclicality and project deferrals −0.3% North America, Middle East & Africa Medium-term (2–4 yr)
Tariffs and trade barriers on steel products −0.2% North America Short-term (≤2 yr)


Fragmented Regional Certifications and Standards

Manufacturers must qualify the same design to API, ASME, EN, PED, and national standards such as China's GB series [5][12]. Each certification adds testing cost and lead time. Smaller producers often cannot afford multiple qualifications, which limits export reach and pushes larger firms to build regional plants, tying up capital that could otherwise fund product development.

Raw Material and Alloy Price Volatility

Globe valve bodies and trim rely on carbon steel, stainless steel, and nickel alloys. Nickel prices briefly exceeded USD 100,000 per tonne on the LME in March 2022 before trading was suspended [13]. Such swings squeeze margins on fixed-price EPC contracts and push buyers to delay discretionary replacement orders.

Substitution by Ball and Butterfly Valves

Globe valves create higher pressure drop than quarter-turn designs. Where tight throttling is not essential, engineers increasingly select characterized ball or high-performance butterfly valves, which cost less in large sizes [14]. This substitution is most visible in water distribution and HVAC, where energy efficiency drives specification.

Oil Price Cyclicality and Project Deferrals

Oil and gas remains the largest end-user, so commodity price swings ripple through orders. The 2020 downturn cut upstream investment by roughly 30% [1], and many projects took two years to restart. Any repeat would delay valve packages that are typically ordered 12–18 months before commissioning.

Tariffs and Trade Barriers on Steel Products

The U.S. raised Section 232 tariffs on steel and aluminum to 50% in June 2025 [15]. Valve assemblers that import castings from China and India face higher landed costs, and some project owners are deferring non-critical replacements until supply chains settle.

Globe Valve Market Opportunities

Emerging-Market Water and Industrial Projects

India, Southeast Asia, and Saudi Arabia are funding desalination, treatment, and industrial cluster projects at scale. Saudi Arabia's Vision 2030 water program targets major capacity additions through privatized independent water projects [9]. Suppliers that localize assembly can win share against imports and qualify for domestic content preferences.

Diagnostics-as-a-Service and Data Monetization

Smart positioners already collect travel, friction, and pressure data. Vendors can package that data into subscription monitoring services that predict trim wear and packing failure. This shifts revenue from one-time hardware sales to recurring contracts and deepens customer lock-in across fleets of installed valves.

Hydrogen and Carbon Capture Applications

The IEA counts low-emissions hydrogen and CCUS among the fastest-growing project pipelines in its tracking [1]. Hydrogen service demands specialized materials that resist embrittlement, while CO2 injection requires high-pressure, corrosion-resistant trim. Early qualification positions suppliers for premium-priced orders as projects reach final investment decision.

Low-Emission Retrofit Kits for the Installed Base

Millions of installed globe valves predate API 624 [5]. Retrofit packing and bonnet kits let operators meet methane rules without full valve replacement. This aftermarket is less cyclical than project sales and carries higher margins.

Small Modular Reactor Supply Chains

Several SMR designs are moving toward licensing in North America and Europe. Each design needs a qualified nuclear valve supply chain, and early vendor selection often locks in decades of spares revenue.

Globe Valve Market Future Outlook

Diagnostics and Autonomous Plant Operations

By the early 2030s, most new control valves will ship with digital positioners capable of self-diagnosis. Operators are pairing this data with plant-wide analytics to predict failures weeks in advance. Vendors that turn diagnostics into actionable maintenance schedules will capture a larger share of lifecycle value than those selling hardware alone [16].

Energy Transition Applications

The IEA's Net Zero scenarios require large build-outs of hydrogen, CCUS, and nuclear capacity this decade [1][10]. Each needs valves qualified for unfamiliar media, pressures, and temperatures. Early material qualification and testing investment will separate leaders from followers as these projects reach construction.

Water Security and Reuse

The World Bank estimates that water scarcity could cost some regions up to 6% of GDP by 2050 [20]. That risk is pushing governments toward reuse, desalination, and leakage reduction, all of which rely on precise flow and pressure control. Water will likely remain the fastest-growing end-user through 2035.

Supply Chain Localization and Emissions Reporting

Tariffs and energy security concerns are pushing buyers toward regional sourcing [15]. At the same time, scope 3 reporting under the EU Corporate Sustainability Reporting Directive asks suppliers to document product carbon footprints [21]. Manufacturers with regional plants and verified emissions data will gain an edge in tenders.

Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America USD 1.98 Billion LNG export, methane compliance, water funding
Europe 19.5% share EU methane regulation, chemical plant upgrades, nuclear refurbishment
Asia-Pacific 41.5% share Refining-chemical integration, water supply, power generation
Latin America 4.3% CAGR Offshore upstream, mining, water utilities
Middle East & Africa USD 0.82 Billion Gas processing, desalination, downstream expansion
Total USD 8.62 Billion —


North America

Country Metric Key Driver
United States 84% of regional market LNG terminals and EPA methane rule retrofits
Canada 3.6% CAGR Oil sands maintenance and LNG Canada operations


The North American Globe Valve Market benefits from a rare overlap of greenfield and compliance spending. Gulf Coast LNG projects such as Plaquemines and Corpus Christi Stage 3 are adding liquefaction capacity [2], while the EPA methane rule obliges operators to fix or replace leaking components [4]. Canada's LNG Canada facility began exporting in 2025, sustaining aftermarket demand in British Columbia.

Europe

Country Metric Key Driver
Germany USD 0.43 Billion Chemical plant modernization and district heating
United Kingdom 19% of regional market North Sea decommissioning and Sizewell C nuclear
France 3.4% CAGR Nuclear fleet life extension under EDF programs
Rest of Europe USD 0.56 Billion Norwegian gas, Dutch and Italian refining


Europe's demand rests on replacement rather than new capacity. The EU Methane Regulation requires leak detection and repair surveys across oil and gas infrastructure [7], and Germany's chemical sector is upgrading valves for energy efficiency after the 2022 gas price shock. France's nuclear life-extension program sustains orders for severe-service valves.

Asia-Pacific

Country Metric Key Driver
China 46% of regional market Refining-chemical integration and power plants
India 6.2% CAGR Jal Jeevan Mission and refinery expansions
Japan USD 0.48 Billion Nuclear restarts and plant maintenance
South Korea 8% of regional market Shipbuilding, LNG carriers, and petrochemicals
Rest of Asia-Pacific USD 0.58 Billion Southeast Asian refining and Australian LNG


Asia-Pacific holds the largest slice of the Globe Valve Market because it hosts most of the world's new refining, petrochemical, and power capacity [11]. China's domestic manufacturers compete hard on price, while India's water and refinery programs lift demand for imported and locally made valves alike [8]. South Korea's LNG carrier backlog adds cryogenic valve orders.

Latin America

Country Metric Key Driver
Latin America (regional aggregate) 4.3% CAGR Pre-salt offshore development and mining water systems


Latin America's growth leans on offshore oil. Petrobras' 2025–2029 business plan allocates about USD 111 billion in capex, much of it to pre-salt FPSOs [18], and Guyana's Stabroek block continues to add production vessels. Mining operations in Chile and Peru add steady demand for water and slurry control.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 38% of regional market Aramco gas expansion and desalination
South Africa 3.8% CAGR Water utility rehabilitation and Eskom maintenance
Rest of Middle East & Africa USD 0.36 Billion Qatar North Field LNG and UAE downstream


Gas monetization drives the Middle East & Africa Globe Valve Market. Saudi Aramco is expanding gas output through the Jafurah unconventional field [19], while Qatar's North Field expansion will lift LNG capacity substantially by 2030. Desalination and water reuse programs add a second, less cyclical demand stream [9].

Globe Valve Market By Region, 2025-2035

Globe Valve Market Segmentation

By End-User

Segment Metric (2025) Primary Demand Driver
Oil & Gas 33.5% share Gas processing, LNG, and methane compliance retrofits
Chemicals USD 1.55 Billion Refining-chemical integration in Asia
Power & Energy 22.0% share Nuclear, combined-cycle, and HVAC applications
Water & Wastewater 5.1% CAGR Federal and national water infrastructure programs
Others USD 0.95 Billion Pharmaceuticals, food processing, pulp and paper


Oil & Gas leads the Globe Valve Market by end-user because choke, separator, and compressor anti-surge loops require precise throttling under high pressure. Water & Wastewater grows fastest, as utilities in the U.S., India, and the Gulf replace aging valves and add treatment capacity [3][8]. Power & Energy demand spans steam, feedwater, and building HVAC systems, while Chemicals favors alloy trims for corrosive service. The Others category covers pharmaceuticals, food processing, and pulp and paper plants.

Competitive Benchmarking

The Globe Valve market is moderately concentrated. The top five providers account for an estimated 28–34% of revenue, and the Herfindahl-Hirschman Index is between 650–800, indicating a somewhat fragmented field. Global companies dominate severe-service and automated valves, while hundreds of regional suppliers compete on standard cast-steel items in China, India and Italy.

Company Est. Revenue Share Range Key Offerings for Globe Valve Market Strategic Positioning
Emerson Electric Co. ~8–11% Fisher control valves, digital positioners Automation-led leader with deep diagnostics portfolio
Flowserve Corporation ~6–9% Valtek and MOGAS severe-service valves Aftermarket-heavy, expanding severe-service range
SLB (Cameron) ~4–6% Oil and gas globe and choke valves Upstream-focused, integrated with well systems
Crane Company ~3–5% Engineered globe valves for process and nuclear Niche specialist in severe and nuclear service
IMI plc ~3–5% IMI Critical Engineering control valves Premium severe-service and power applications
KITZ Corporation ~3–5% Industrial bronze and steel globe valves Strong Asian distribution and cost position
Velan Inc. ~2–4% Forged and cast steel globe valves Nuclear and power plant specialist
Samson AG ~2–4% Pneumatic control valves and positioners European process industry focus
Valmet (Neles) ~2–4% Control valves and intelligent controllers Pulp, paper, and process automation integration
Neway Valve ~2–4% API globe valves for oil, gas, and chemicals Price-competitive Chinese exporter gaining share


Recent News & Developments

  • Flowserve (February 2023): Agreed to acquire Velan to expand its nuclear and severe-service portfolio; the deal was terminated later that year after French government objections, keeping Velan independent [17].
  • Crane Company (April 2023): Completed its separation from Crane NXT, creating a focused industrial firm with an expanded process flow technologies segment [22].
  • U.S. EPA (December 2023): Finalized methane standards for oil and gas operations, triggering retrofit demand for low-emission valves [4].
  • European Union (August 2024): Methane Regulation (EU) 2024/1787 entered into force, mandating leak detection and repair across the gas value chain [7].
  • Flowserve (December 2024): Announced the acquisition of MOGAS Industries, strengthening its severe-service valve range for mining and refining [17].
  • Emerson (March 2025): Completed the purchase of remaining AspenTech shares, tying asset optimization software more closely to its valve and automation hardware [16].
  • U.S. Government (June 2025): Raised Section 232 tariffs on steel and aluminum imports to 50%, raising costs for importers of valve castings [15].

Globe Valve Market Report Scope

Parameter Details
Market Scope Globe valves for flow regulation across oil and gas, chemicals, power and energy, water and wastewater, and other industries
Study Period 2021–2035 (Historical: 2021–2024; Base Year: 2025; Forecast: 2026–2035)
CAGR 3.96% (2026–2035)
Market Size Checkpoints USD 8.62 Billion (2025); USD 8.96 Billion (2026); USD 10.47 Billion (2030); USD 12.71 Billion (2035)
Fastest Growing Segments Water & Wastewater (end-user); Asia-Pacific (region)
Companies Profiled Emerson, Flowserve, SLB, Crane, IMI, KITZ, Velan, Samson, Valmet, Neway Valve
Valuation Currency USD Billion

FAQs

How long are lead times for engineered products in the Globe Valve Market?
Severe-service and alloy globe valves typically take 20–40 weeks from order to delivery. Nuclear-qualified units can exceed a year because of documentation and testing [10]. Buyers should lock valve packages early in project schedules.
When should engineers choose a globe valve over a ball valve?
Choose a globe valve when the loop needs precise throttling across a wide flow range or frequent cycling. Ball valves suit on-off duty with minimal pressure drop [14].
Which certifications matter most when procuring for oil and gas sites?
API 623 covers steel globe valve design, while API 624 qualifies rising-stem valves for low fugitive emissions [5]. Requesting both reduces methane compliance risk under current rules.
How do buyers in the Globe Valve Market evaluate total cost of ownership?
Purchase price often represents under a quarter of lifetime cost. Maintenance labor, packing replacement, and energy lost through pressure drop dominate the rest [14].
Are Chinese and Indian manufacturers competitive for critical service?
Leading Chinese and Indian producers now hold API and PED certifications and win refinery packages. Many end-users still restrict them from nuclear and sour-gas service pending longer track records [12].
What role does additive manufacturing play in globe valve trim?
Additive manufacturing produces complex anti-cavitation and noise-reduction cages that machining cannot easily achieve. It also shortens spare-part lead times for obsolete trims [16].
Which risk could most disrupt the Globe Valve Market outlook?
A sustained oil price collapse poses the largest risk, since oil and gas is the leading end-user. Upstream investment fell about 30% in 2020, delaying valve orders for two years [1].
Author
Author Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Air Operated Double Diaphragm (AODD) Pump Market
Case Study
Industrial Automation & Equipment
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.