Gamification Market Summary
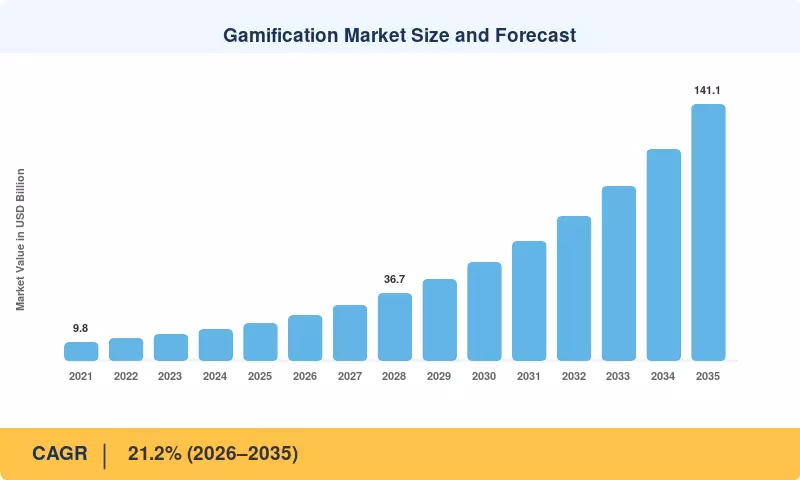
The Gamification Market reached USD 20.6 billion in 2025 and is projected to open the forecast window at USD 25.0 billion in 2026 before climbing to USD 141.1 billion by 2035, a compound annual growth rate of 21.2% across 2026–2035. Two catalysts anchor that trajectory. Enterprise software buyers have shifted budget toward measurable behavior outcomes rather than license seats, and the European Union's Digital Education Action Plan committed EUR 1.1 billion in blended instruments through 2027 toward interactive instructional technology [1][2]. Both forces convert what was once a design experiment into a procurement category with its own line item.
Legacy engagement infrastructure is being dismantled quickly. Static intranet leaderboards, spreadsheet-tracked incentive programs and one-way learning management portals are giving way to API-first engagement layers that read live signals from CRM, HCM and support systems and return progression state in milliseconds. Enterprise spending on interactive workforce applications rose to roughly USD 14.8 billion in 2024 according to industry tracking, with cloud-delivered platforms absorbing the majority of net-new deployments [3].
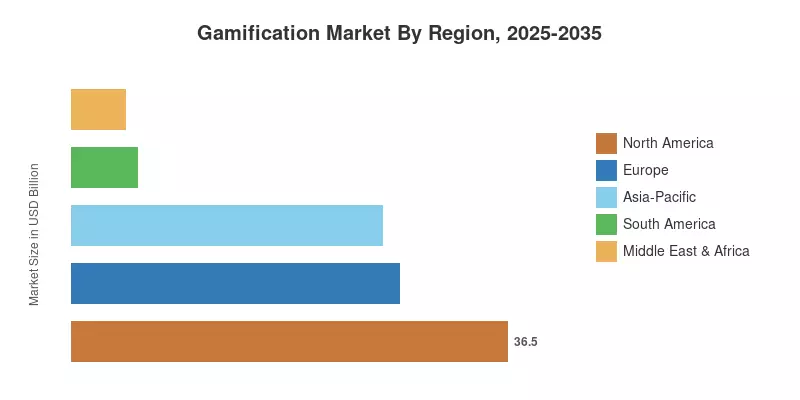
Regionally, North America holds 36.5% of 2025 revenue, supported by dense enterprise SaaS penetration and mature loyalty economics in retail and financial services. Asia-Pacific expands fastest at a 24.6% CAGR, propelled by mobile-first consumer bases in India and Southeast Asia. Europe follows North America with a 27.5% share, where regulated compliance training and accessibility mandates shape platform requirements. Through 2035, the Gamification Market will increasingly be judged on measured behavior change rather than usage counts.
Key Report Takeaways
• By Component
- Platform software commands 68.4% of 2025 Gamification Market revenue, reflecting buyer preference for configurable engines over bespoke builds.
- Support and managed services post the fastest component expansion at a 23.6% CAGR as programs move from launch to sustained operation.
• By Deployment Mode
- Cloud deployments account for 74.6% of installed capacity, driven by rapid connector availability.
- Hybrid architectures grow at a 25.9% CAGR among regulated buyers needing on-premises identity stores.
• By Organization Size
- Large enterprises contribute 63.2% of revenue, concentrated in organizations above 5,000 employees.
- Small and medium enterprises grow at a 24.8% CAGR as per-seat entry pricing falls below USD 5 monthly.
• By Application
- Marketing and sales applications lead with 28.4% share of the Gamification Market.
- Workforce productivity and performance applications expand fastest at a 24.9% CAGR.
• By End-User Industry
- Retail and e-commerce hold 22.6% share, anchored in loyalty and tier progression programs.
- Healthcare and life sciences record the steepest climb at a 25.7% CAGR, tied to adherence and credentialing programs.
• By Region
- North America holds 36.5% of 2025 revenue.
- Asia-Pacific advances at a 24.6% CAGR through 2035.
- Middle East and Africa contributes USD 0.93 billion in 2025, concentrated in Gulf public-sector programs.
Market Size and Forecast (2021–2035)
Estimates combine vendor revenue disclosures, channel partner interviews, procurement benchmarks from enterprise buying consortia, and triangulation against reported deployment counts. Historical values for the Gamification Market were reconstructed from audited filings of publicly listed platform vendors and from private-company funding disclosures, then reconciled against regional software spending series published by national statistical agencies [4][6].


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


