Flow Sensor Market Summary
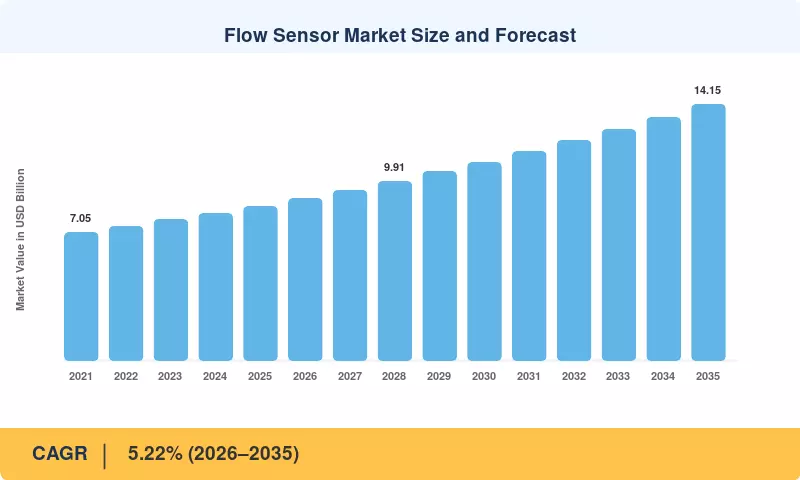
The Flow Sensor Market was valued at USD 8.51 Billion in 2025 and is projected to reach USD 8.95 Billion in 2026, expanding to USD 14.15 Billion by 2035 at a CAGR of 5.22% over 2026–2035. Two policy catalysts anchor this trajectory. The U.S. Infrastructure Investment and Jobs Act set aside roughly USD 55 billion for water infrastructure [3], and the U.S. EPA's 2024 methane rule requires oil and gas operators to quantify and repair emissions far more rigorously than before [4].
Underneath the deployed base, tech is evolving. Orifice plates and mechanical turbine meters, which were previously the standard in process plants, are being replaced by multipath ultrasonic, Coriolis, and electromagnetic designs that include onboard diagnostics. The American Water Works Association predicts that the renewal of U.S. water pipes and systems will require USD 1 trillion over the course of 25 years [1]. Utilities are including the cost of meter replacement in this expenditure. Currently, operators can validate the health of meters in situ with self-verification firmware, which has significantly altered the way in which plants allocate funds for process instrumentation.
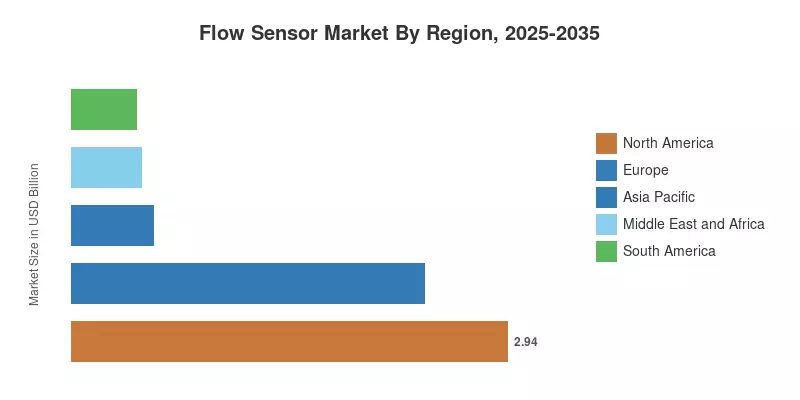
North America commands a 34.6% regional market share, which is bolstered by municipal metering upgrades and shale midstream activity. Driven by rural water programs in India and chemical capacity additions in China, the Asia Pacific region is the fastest-growing, with a compound annual growth rate (CAGR) of 6.41%. The methane and wastewater directives have propelled Europe to a 28.0% share, resulting in its second-place ranking. The rate at which operators convert compliance obligations into instrumented, data-rich assets will determine growth over the next decade.
Key Report Takeaways
• By Type
- Liquid applications account for 61.5% of the Flow Sensor Market in 2025, led by water utilities and chemical processing
- Gas measurement expands at a 4.12% CAGR, supported by pipeline monitoring and combustion control
• By Technology
- Differential Pressure holds the largest technology share at 28.5%, anchored by a deep installed base
- Ultrasonic is the fastest-growing technology at a 6.55% CAGR as clamp-on retrofits gain favor
- Coriolis generates USD 1.43 Billion in 2025 revenue from custody-transfer and batching duties
• By Installation Type
- Inline systems capture 44.6% of revenue, favored in greenfield plant construction
- Clamp-On deployments grow at a 6.66% CAGR as brownfield sites avoid shutdowns
• By End-user Industry
- Chemical and Petrochemical leads with a 27.8% share of the Flow Sensor Market on the back of process safety mandates
- Water and Wastewater expands fastest at a 6.64% CAGR under loss-reduction and reuse directives
• By Region
- North America holds a 34.6% share, the largest of any region
- Asia Pacific grows at a 6.41% CAGR, the fastest worldwide
- Europe generates USD 2.38 Billion in 2025 revenue
Market Size and Forecast (2021–2035)
Market Research Future sized the Flow Sensor Market using a bottom-up model that aggregates shipment volumes and average selling prices by technology and installation type, cross-checked against the reported instrumentation revenue of leading suppliers [16][17][18][19]. Historical estimates for 2021–2024 were reconciled with capital expenditure data from energy, water, and chemical end users, while forecasts layer regulatory timelines and announced project pipelines onto baseline demand.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



