Flexible Filament 3D Printing Material Market (2026 - 2035)

Flexible Filament 3D Printing Material Market Size, Share and Research Report By Application (Automotive, Consumer Goods, Healthcare, Aerospace and Defense, and Others) And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) – Industry Forecast Till 2035
ID: MRFR/SEM/40835-HCR 111 Pages Aarti Dhapte, Aarti Dhapte Last Updated: October 05, 2026
Flexible Filament 3D Printing Material Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.55%
2025 Market SizeUSD 10.24 Billion
2035 Market SizeUSD 19.31 Billion
Key Players
Stratasys Ltd.
BASF Forward AM
3D Systems Corporation
Lubrizol
Evonik Industries
Arkema
Opportunities
  • Bio-Based and Recycled Elastomer Grades
  • Emerging-Market Distributed Manufacturing
  • Material-as-a-Service and Print-Profile Data

Flexible Filament 3D Printing Material Market Summary

The Flexible Filament 3D Printing Material Market was valued at USD 10.24 billion in 2025 and is projected to reach USD 10.91 billion in 2026, advancing to USD 19.31 billion by 2035 at a CAGR of 6.55% over 2026–2035. Two policy catalysts anchor that path. The U.S. AM Forward initiative, launched in 2022, secured commitments from large OEMs to buy additively manufactured parts from smaller domestic suppliers [8], while India's National Strategy for Additive Manufacturing targets a USD 1 billion GDP contribution from the sector [9]. Both programs widen the pool of production users who specify elastomeric printed parts rather than rigid mock-ups.

Underneath the headline numbers, the technology stack is shifting. Cast urethane, silicone molding, and soft-tooled rubber prototypes are giving way to printed TPU and TPE parts that engineers can iterate overnight, and Bowden-style extruders are being replaced by direct-drive toolheads that feed rubber-like 3D print materials reliably. The broader additive manufacturing industry grew 11.1% to roughly USD 20.0 billion in 2023 [2], and elastomers are capturing a rising share of that material spend as functional end-use parts overtake visual prototypes.

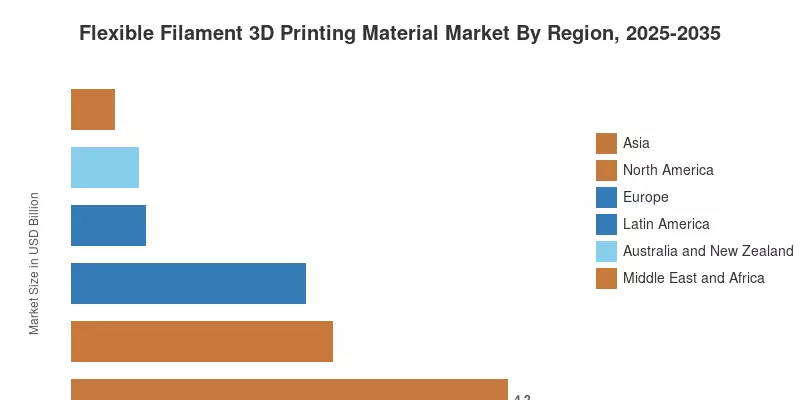
Regionally, Asia leads with a 41.0% share in 2025 and also posts the fastest regional CAGR at 7.4%, supported by China's dense printer manufacturing base and India's policy push. North America ranks second, driven by medical device qualification work and defense sustainment programs. Over the next decade, growth will hinge on how quickly suppliers convert hobbyist-grade chemistries into certified, traceable production materials.

Key Report Takeaways

• By Application

  • Automotive held the largest application share at 29.5% in 2025, as OEMs and Tier-1 suppliers print seals, grommets, and cable guides for fit-and-function validation.
  • Healthcare is the fastest-growing application, expanding at a 7.9% CAGR in demand for orthotic insoles, prosthetic liners, and patient-specific anatomical models.
  • Consumer Goods generated USD 2.66 billion within the Flexible Filament 3D Printing Material Market in 2025, led by footwear midsoles, wearables, and phone accessories.

• By Region

  • Asia commanded 41.0% of the Flexible Filament 3D Printing Material Market in 2025, anchored by China's printer and filament production clusters.
  • North America generated USD 2.51 billion in 2025 on the strength of medical, defense, and service-bureau demand.
  • Latin America is set to grow at a 6.9% CAGR as Brazilian automotive and footwear producers adopt in-house printing.

Market Size and Forecast (2021–2035)

Estimates for the Flexible Filament 3D Printing Material Market combine bottom-up tracking of filament and elastomeric feedstock shipments from leading suppliers with top-down validation against printer installed-base data, company filings, and industry association statistics[2][3]. Historical values were reconciled with reported revenues of listed material and system vendors, while forecast years apply demand-side modeling by application and region.
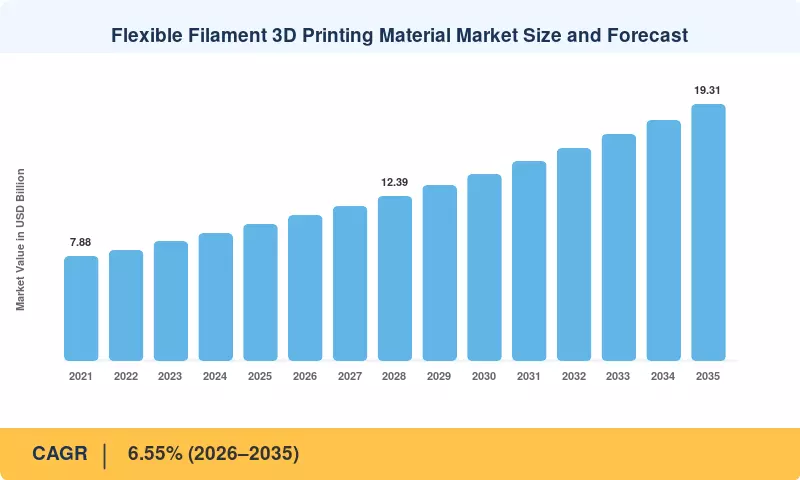
Flexible Filament 3D Printing Material Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Impact percentages below are directional estimates of each driver's contribution to growth in the Flexible Filament 3D Printing Material Market. They overlap and interact, so they should not be summed to reproduce the headline CAGR.

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Functional prototyping in industrial R&D +1.3% Global Short-term (≤2 yr)
Mass customization in footwear and sporting goods +1.1% North America, Europe, Asia Medium-term (2–4 yr)
Patient-specific medical devices +1.0% North America, Europe Medium-term (2–4 yr)
Automotive lightweighting, tooling, and spares +0.9% Asia, Europe Medium-term (2–4 yr)
Direct-drive desktop printer installed base +0.8% Global Short-term (≤2 yr)
National additive manufacturing policies +0.7% Asia, North America Long-term (≥4 yr)


Functional Prototyping in Industrial R&D

Engineering teams increasingly need prototypes that bend, compress, and seal like the final part, not just look like it. Flexible filaments let designers test bike grips, vibration dampers, and machine bellows under real loads before committing to tooling. The additive manufacturing industry expanded 11.1% in 2023 to about USD 20.0 billion [2], and prototyping remains the largest use case by user count, giving elastomeric grades a broad, recurring demand base.

Mass Customization in Footwear and Sporting Goods

Printed lattices from concept shoes are being incorporated into catalog items by sportswear companies. Printed lattice midsoles have been commercialized by adidas, which reported EUR 23.7 billion in revenue in 2024 [13]. Custom insoles, helmet liners, and protective padding are being introduced by competitors. Filament-based technologies provide a lower-capital path for smaller brands, and even a low single-digit share of midsole volume created additively amounts to thousands of tons of elastomer demand.


Patient-Specific Medical Devices

Hospitals and orthotics labs print insoles, prosthetic socket liners, and surgical planning models from flexible grades tuned to anatomical softness. The U.S. FDA stated that it had reviewed more than 100 marketed devices made on 3D printers when it issued its additive manufacturing guidance [10], which gave device makers a clearer regulatory pathway. Point-of-care printing lowers lead times from weeks to days, supporting premium pricing for biocompatibility-tested filaments.

Automotive Lightweighting, Tooling, and Spares

Global vehicle output reached roughly 92 million units in 2024 [6], and electric vehicle sales exceeded 17 million in the same year [5]. New EV platforms bring fresh wire-harness routings, battery-pack gaskets, and cabin trim that need rapid iteration. Plants also print soft-jaw fixtures and protective covers in-house, trimming tooling lead times and turning flexible filament into a routine maintenance consumable.

Direct-Drive Desktop Printer Installed Base

Low-Shore materials historically failed in Bowden extruders because the filament buckled before reaching the nozzle. Current-generation desktop printers ship with direct-drive or near-direct toolheads that handle 85A and softer grades [14]. Market Research Future estimates that more than 60% of desktop units shipped in 2025 can print soft elastomers without modification, expanding the addressable user base far beyond specialist workshops.

National Additive Manufacturing Policies

Additive manufacturing is being transformed from a laboratory tool into an industry competence through government initiatives. AM Forward connects U.S. primes with small suppliers [8], India strives for a USD 1 billion GDP contribution [9], and China's MIIT action plan targeted sector income above CNY 20 billion with annual growth surpassing 30% [12]. Training facilities and qualification efforts that integrate flexible materials into production supply chains are funded by these frameworks.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Process sensitivity of low-Shore grades −0.6% Global Short-term (≤2 yr)
Polyurethane feedstock price volatility −0.5% Global Medium-term (2–4 yr)
Limited material standards for regulated sectors −0.4% North America, Europe Long-term (≥4 yr)
Competition from resin and powder elastomers −0.4% North America, Europe, Asia Medium-term (2–4 yr)
End-of-life and recycling constraints −0.3% Europe Long-term (≥4 yr)


Process Sensitivity of Low-Shore Grades

Soft grades remain unforgiving. Shore 60A–85A filaments typically print at 20–30 mm/s, a fraction of rigid-material speeds, and are prone to stringing, under-extrusion, and feed jams [14]. Failed builds waste machine hours and discourage casual users, which caps adoption among small businesses that lack in-house process expertise.

Polyurethane Feedstock Price Volatility

TPU depends on isocyanates and polyols whose prices track petrochemical cycles. Chemical producers reported sharp volume and pricing swings through 2023–2024 [16][17], and Market Research Future estimates that base resin represents 45–55% of flexible filament production cost. Smaller spoolers without long-term supply contracts struggle to pass these swings through, squeezing margins and delaying capacity investment.

Limited Material Standards for Regulated Sectors

ISO/ASTM 52900 standardizes vocabulary [11], and ASTM D2240 covers durometer testing [18], but no widely adopted specification governs flexible filament properties as printed. Based on a review of supplier datasheets, fewer than one in five commercial flexible SKUs publish complete biocompatibility data. Aerospace and medical buyers therefore run lengthy internal qualifications, slowing conversion from prototype to certified part.

Competition from Resin and Powder Elastomers

Vat photopolymerization and powder bed fusion elastomers offer finer detail and more isotropic strength than extruded filament. Formlabs positioned its Form 4 as printing two to five times faster than its predecessor [19], narrowing the throughput gap for flexible resins. Where surface finish or lattice density is critical, such as premium midsoles, buyers increasingly choose these alternatives over filament.

End-of-Life and Recycling Constraints

It is difficult to recover printed elastomer components, especially when they are connected to hard polymers in multi-material systems. Only 14% of plastic packaging is collected for recycling worldwide [21], indicating the insufficiency of the infrastructure for polymer recovery. The EU Ecodesign for Sustainable Products Regulation [7], which will raise durability and recyclability criteria, may result in extra compliance costs for suppliers of conventional fossil-based materials.


Flexible Filament 3D Printing Material Market Opportunities

Suppliers that align product roadmaps with sustainability rules, emerging-market demand, and new commercial models stand to outgrow the Flexible Filament 3D Printing Material Market average over the forecast period.

Bio-Based and Recycled Elastomer Grades

Ecodesign requirements under Regulation (EU) 2024/1781 [7] and corporate reporting duties under the CSRD [25] push brands to document material footprints. Bio-based TPU using plant-derived polyols and post-industrial recycled grades can command price premiums of 15–25% where buyers need auditable carbon data. Early movers can lock in footwear and consumer electronics accounts before these grades commoditize.

Emerging-Market Distributed Manufacturing

India, ASEAN, and Brazil combine fast-growing automotive and footwear sectors with limited access to soft tooling. Localized filament compounding near these clusters cuts import duties and freight costs, and India's national strategy funds shared additive manufacturing facilities [9]. Suppliers that pair regional production with application training can capture demand that multinational distributors currently underserve.

Material-as-a-Service and Print-Profile Data

RFID-tagged spools and printer-integrated material systems allow suppliers to track consumption, automate reordering, and sell validated print profiles as a service. Consumption data from connected fleets also supports predictive inventory contracts for service bureaus and factories. This model shifts revenue from one-off spool sales toward recurring subscriptions with higher customer retention.

Point-of-Care Orthotics and Wearables

Clinics printing insoles and brace liners on site need consistent, biocompatibility-documented grades and simple validated workflows. The FDA's device guidance [10] gives a template for manufacturers seeking clearance. Suppliers offering pre-qualified materials bundled with scanning and design software can win long-term clinical contracts.

Multi-Material Rigid-Flexible Parts

Tool-changer and dual-nozzle printers now print rigid housings with integrated soft seals and grips in a single build [14][22]. This removes assembly steps for consumer products and industrial enclosures. Filament makers that engineer TPU grades with proven adhesion to PLA, PETG, and nylon can differentiate on bond strength rather than price.

Flexible Filament 3D Printing Material Market Future Outlook

Four structural themes will shape how the Flexible Filament 3D Printing Material Market evolves over the next decade.

AI-Assisted Print Parameter Optimization

In-situ sensors and machine-learning slicers will gradually adjust temperature, retraction, and speed for every soft grade automatically. This eliminates failed builds, directly addresses the process sensitivity constraint, and makes 60A–85A materials available to non-specialists. Within printer ecosystems, suppliers who supply validated material data into these systems will be selected by default.


Circular Materials and Sustainability Reporting

The CSRD [25] and Ecodesign regulation [7] will require brands to disclose product material footprints in detail. Bio-based polyols, mechanically recycled TPU, and take-back programs will shift from niche to procurement requirement in European consumer goods by the early 2030s. Suppliers with verified life-cycle data will win share even at higher prices.

Vehicle Electrification

The IEA reported more than 17 million electric car sales in 2024 and projects continued growth [5]. New battery enclosures, charging hardware, and thermal-management systems require gaskets, bumpers, and cable protectors that are prototyped and increasingly produced in flexible grades. Electrification thus renews automotive demand even as legacy powertrain parts decline.

Regionalized Supply Chains

Reshoring and nearshoring policies favor local production of spares and short-run parts. Printing flexible components close to the point of use reduces inventory and freight exposure, and national programs [8][9] fund the facilities to do it. Over time, digital part libraries will replace warehoused rubber spares for many low-volume items.

Regional Market Share Analysis

Region Key Metric (one per row) Primary Investment Themes
North America USD 2.51 Billion (2025) Medical device qualification, defense sustainment
Europe 22.0% share (2025) Automotive tooling, ecodesign-compliant grades
Asia 41.0% share (2025) Printer manufacturing, consumer goods, policy support
Australia and New Zealand 6.3% CAGR (2026–2035) Mining spares, clinical orthotics
Latin America 6.9% CAGR (2026–2035) Footwear and automotive localization
Middle East and Africa USD 0.41 Billion (2025) Industrial diversification programs
Total USD 10.24 Billion (2025) —

Regional demand across the Flexible Filament 3D Printing Material Market reflects the distribution of printer manufacturing, automotive production, and medical device clusters. Asia leads in volume and growth, while North America and Europe command higher average selling prices for certified grades.


North America

Country Metric (one per row) Key Driver
US 78.0% share of region Medical devices and defense programs
Canada 6.2% CAGR Aerospace maintenance and research labs
Mexico USD 0.25 Billion Automotive assembly fixtures

North American demand centers on regulated, high-value applications. Medical device makers qualify flexible grades for orthotics and surgical models under FDA guidance [10], while AM Forward commitments steer primes toward small suppliers that print seals and protective components [8]. Canada benefits from aerospace maintenance work, and Mexico's automotive corridor adopts printed fixtures for assembly lines serving U.S. OEMs.


Europe

Country Metric (one per row) Key Driver
Germany 26.0% share of region Automotive prototyping and tooling
UK USD 0.36 Billion Medical devices and motorsport
France 5.7% CAGR Aerospace and luxury goods
Italy 11.0% share of region Footwear and design industries
Spain USD 0.18 Billion Automotive supply chain
Nordic Countries 6.4% CAGR Sustainable consumer products
Russia 5.0% share of region Domestic industrial substitution
Rest of Europe USD 0.29 Billion Central European manufacturing

Germany anchors European consumption through automotive prototyping and industrial machinery, while the UK and France lead in medical and aerospace qualification work. Ecodesign rules [7] are accelerating interest in bio-based and recyclable grades, particularly among Nordic consumer brands. Russia remains a smaller, largely domestically supplied market.


Asia

Country Metric (one per row) Key Driver
China 47.0% share of region Printer and filament manufacturing clusters
India 9.1% CAGR National AM strategy and automotive growth
Japan USD 0.71 Billion Automotive and robotics components
South Korea 9.0% share of region Electronics and EV supply chain
ASEAN 8.3% CAGR Footwear and contract manufacturing
Rest of Asia USD 0.21 Billion Emerging industrial users

China dominates the Flexible Filament 3D Printing Material Market in Asia, hosting most of the world's desktop printer and filament production and building on the MIIT action plan's industrial targets [12]. India is the fastest-growing country as its national strategy funds shared facilities [9]. Japan and South Korea emphasize high-precision automotive and electronics applications, while ASEAN footwear hubs adopt printed midsoles and tooling.


Australia and New Zealand

Country Metric (one per row) Key Driver
Australia 82.0% share of region Mining spares and clinical orthotics
New Zealand 6.6% CAGR Medical and agritech applications

Australian mining operators print wear-resistant flexible spares on site to avoid long supply lead times at remote operations. Clinical orthotics providers in both countries use printed insoles and splints, supported by strong university research programs. New Zealand remains a small but steadily growing market concentrated in medical and agricultural uses.


Latin America

Country Metric (one per row) Key Driver
Brazil USD 0.27 Billion Automotive and footwear production
Argentina 6.5% CAGR Agricultural machinery and medical use
Rest of Latin America 30.0% share of region Education and small-business adoption

Brazil leads the region through its automotive and footwear industries, both of which use printed flexible parts for prototyping and tooling. Argentina's growth is tied to agricultural machinery and medical workshops. Currency volatility and import duties raise filament costs, creating openings for regional compounders.


Middle East and Africa

Country Metric (one per row) Key Driver
Saudi Arabia 24.0% share of region Industrial localization programs
UAE 8.0% CAGR Construction, healthcare, and research hubs
South Africa USD 0.07 Billion Automotive and mining spares
Egypt 7.1% CAGR Academic and medical adoption
Rest of Middle East and Africa 26.0% share of region Early-stage industrial users

Gulf diversification programs are funding additive manufacturing centers that print industrial spares and medical products locally. Saudi Arabia and the UAE lead adoption, while South Africa supports automotive and mining users. Egypt shows rising uptake in universities and medical workshops.


Flexible Filament 3D Printing Material Market By Region, 2025-2035

Flexible Filament 3D Printing Material Market Segmentation

The Flexible Filament 3D Printing Material Market is segmented by application into Automotive, Consumer Goods, Healthcare, Aerospace and Defense, and Others, with regional coverage addressed in Section 7.

By Application

Automotive leads the Flexible Filament 3D Printing Material Market by application, holding 29.5% in 2025 as OEMs print seals, grommets, and fixtures for validation and tooling. Consumer Goods follows closely, driven by footwear and wearables, while Healthcare is the fastest-growing segment at a 7.9% CAGR on orthotics and prosthetic liners. Aerospace and Defense relies on certified grades for ducting seals and protective covers, and Others spans education, robotics, and industrial maintenance.

Segment Metric (one per row) Primary Demand Driver
Automotive 29.5% share (2025) Prototyping, tooling, and EV components
Consumer Goods USD 2.66 Billion (2025) Footwear, wearables, and accessories
Healthcare 7.9% CAGR (2026–2035) Orthotics, prosthetics, and anatomical models
Aerospace and Defense 14.0% share (2025) Seals, gaskets, and sustainment spares
Others USD 1.13 Billion (2025) Education, robotics, and maintenance


Automotive: Design teams print soft-touch interior trim, hose couplings, and vibration dampers to verify fit before tooling. Plants also produce protective jaw covers and cable guides in-house, making TPU 3D printing filament a routine factory consumable.

Consumer Goods: Footwear midsoles and insoles are the largest use, followed by watch straps, phone cases, and grips. Customization and short product cycles favor printing over molding for low-volume variants.

Healthcare: Clinics and device makers print insoles, splints, and socket liners tuned to each patient. Growth depends on biocompatibility documentation and streamlined regulatory pathways [10].

Aerospace and Defense: Maintenance depots print seals and protective covers for aging fleets where original tooling no longer exists. Qualification requirements keep volumes modest but prices high.

Others: Schools, robotics developers, and industrial maintenance teams form a fragmented but steady demand base. Low-cost grades and simple print profiles dominate this segment.

Competitive Benchmarking

Concentration in the Flexible Filament 3D Printing Material Market is high at the certified-grade end and fragmented among desktop spoolers. Market Research Future estimates the top five suppliers account for roughly 50–57% of revenue, implying an HHI near 1,400–1,700, a moderately concentrated structure. Chemical majors control base elastomer supply, while specialist filament brands compete on printability, color range, and printer-ecosystem partnerships.

Company Est. Revenue Share Range Key Offerings for Flexible Filament 3D Printing Material Market Strategic Positioning
Stratasys Ltd. ~12–15% Elastomeric FDM and polyjet materials, ex-Covestro TPU portfolio Integrated systems-plus-materials leader
BASF Forward AM ~10–13% Ultrafuse TPU filaments, Ultrasint TPU powders Broad engineering-polymer portfolio
3D Systems Corporation ~8–11% Elastomeric resins and filaments Healthcare and industrial focus
Lubrizol ~7–10% Estane 3D TPU feedstock grades Upstream TPU resin supplier
Evonik Industries ~6–9% INFINAM elastomer materials Specialty chemicals and powders
Arkema ~5–8% N3xtDimension flexible resins, Pebax-based materials High-performance elastomers
Polymaker ~4–7% PolyFlex TPU filament range Desktop and prosumer volume brand
NinjaTek (Fenner Precision Polymers) ~3–6% NinjaFlex and Cheetah TPU filaments Specialist flexible-filament pioneer
eSUN ~3–5% eTPU and flexible filament lines Cost-competitive Asian producer
Formlabs ~3–5% Flexible 80A, Elastic 50A, Silicone 40A resins Resin-based elastomer alternative
Recreus Industries ~2–4% Filaflex ultra-soft filaments Low-Shore specialist


Recent News & Developments

Recent activity in the Flexible Filament 3D Printing Material Market spans consolidation, printer launches, and new sustainability rules.

  • Stratasys (April 2023): Completed its acquisition of Covestro's additive manufacturing materials business, adding TPU and elastomer formulations and strengthening its materials-led strategy [20].
  • European Commission (September 2023): Adopted Regulation (EU) 2023/2055 restricting intentionally added synthetic polymer microparticles, prompting polymer suppliers to review formulations and disclosures [23].
  • Formlabs (April 2024): Launched the Form 4 resin printer, raising throughput for flexible and elastic resins that compete with filament in detailed parts [19].
  • European Union (July 2024): The Ecodesign for Sustainable Products Regulation entered into force, setting a framework for durability and recyclability rules that will reach polymer products [7].
  • Prusa Research (October 2024): Announced the Core One enclosed printer with direct-drive extrusion suited to soft filaments, widening prosumer access to flexible grades [14].
  • Stratasys (December 2024): Announced a USD 120 million strategic investment from Fortissimo Capital, funding growth in materials and manufacturing solutions [24].
  • Bambu Lab (March 2025): Introduced the H2D dual-nozzle printer, supporting rigid-flexible multi-material builds on desktop hardware [22].

Flexible Filament 3D Printing Material Market Report Scope

Parameter Details
Market Scope Flexible Filament 3D Printing Material Market revenue by Application (Automotive, Consumer Goods, Healthcare, Aerospace and Defense, Others) and Geography (North America, Europe, Asia, Australia and New Zealand, Latin America, Middle East and Africa)
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.55% (2026–2035)
Market Size checkpoints USD 10.24 Billion (2025); USD 10.91 Billion (2026); USD 14.06 Billion (2030); USD 19.31 Billion (2035)
Fastest Growing Segments Healthcare (application); Asia (region)
Companies Profiled Stratasys, BASF Forward AM, 3D Systems, Lubrizol, Evonik, Arkema, Polymaker, NinjaTek, eSUN, Formlabs, Recreus Industries
Valuation Currency USD Billion

FAQs

Which Shore hardness grade suits first-time buyers entering the Flexible Filament 3D Printing Material Market?
Shore 95A grades are the practical entry point because they feed reliably on most stock extruders. Softer 85A and 60A grades need direct-drive toolheads and speeds of roughly 20–30 mm/s [14].
How should buyers store and dry flexible filaments before printing?
TPU absorbs moisture quickly, causing bubbling, stringing, and weak layer bonds. Sealed storage with desiccant, plus drying at about 50–60°C for several hours before use, restores print quality [14].
Are materials in the Flexible Filament 3D Printing Material Market suitable for skin-contact medical products?
Only grades with documented biocompatibility testing, such as ISO 10993 cytotoxicity and sensitization data, should be considered. Device makers must still validate the finished printed part, since processing can alter material behavior [10].
What separates TPE from TPU filament in practical use?
Across the Flexible Filament 3D Printing Material Market, TPU offers higher abrasion and oil resistance and prints more predictably. Broader TPE blends reach softer hardness levels but are harder to feed and less dimensionally stable [15].
How do procurement teams qualify a new flexible filament supplier?
Lot-level certificates of analysis covering hardness, diameter tolerance, and melt flow come first. A short pilot run on the production printer fleet then confirms consistency before volume contracts are signed [18].
What should investors watch in the Flexible Filament 3D Printing Material Market over the next five years?
Margin resilience matters most, as polyurethane feedstock costs swing with petrochemical cycles. Suppliers with proprietary formulations, validated printer profiles, and OEM qualifications typically defend pricing better than commodity spoolers [3].
Can flexible filaments be recycled after printing?
Single-material TPU scrap can be reground and re-extruded, though properties degrade with each cycle. Multi-material prints bonding TPU to rigid polymers are far harder to separate, limiting closed-loop recovery across the Flexible Filament 3D Printing Material Market today [21].
Author
Author Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Co-Author Co-Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















