Fire Trucks Market (2026 - 2035)

Fire Truck Market Research Report By Type (Pumpers, Aerial Ladder & Platform Trucks, Tankers (Water Tenders), Rescue Trucks, Others (ARFF, Wildland, Specialty)), By Application (Residential and Commercial, Airports, Military, Wildland and Forestry, Industrial and Others), By Propulsion (Internal Combustion Engine (ICE), Hybrid, Battery-Electric), By End-User (Municipal Fire Departments, Industrial & Private Fire Brigades, Airport Authorities, Military & Defense) - Forecast to 2035
ID: MRFR/AT/5924-CR 150 Pages Shubham Munde, Sejal Akre Last Updated: September 15, 2026
Fire Trucks Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.09%
2025 Market SizeUSD 10.86 Billion
2035 Market SizeUSD 23.52 Billion
Key Players
Oshkosh Corporation
REV Group, Inc.
Rosenbauer International AG
Magirus GmbH
Morita Holdings Corporation
Albert Ziegler GmbH
Opportunities
  • Refurbishment and Life-Extension Programs
  • Emerging-Market Fleet Formation
  • Telematics and Data-Led Service Contracts

Fire Trucks Market Summary

The Fire Truck Market reached USD 10.86 billion in 2025 and opens the forecast window at USD 11.68 billion in 2026, climbing to USD 23.52 billion by 2035 at an 8.09% CAGR. Two catalysts anchor that trajectory. FEMA's Assistance to Firefighters Grant program has pushed roughly USD 324 million per cycle into apparatus and equipment awards, while European clean-fleet procurement rules increasingly bar diesel-only municipal purchases in low-emission zones [1][4].

Technology is turning over faster than the fleet itself. Mechanically governed diesel pumpers with analog pump panels are giving way to CAN bus-managed drivetrains, telematics-linked pump controls, and battery platforms that run scene operations silently for up to two hours. Rosenbauer has invested more than EUR 60 million in electric apparatus development since 2019, and Oshkosh has moved its Volterra line from demonstrator to serial production [17][18].

North America holds 36.1% of 2025 revenue in the Fire Truck Market, supported by a replacement backlog that NFPA links to apparatus averaging well over 15 years in service [2]. Asia-Pacific grows fastest at 8.26% CAGR, and Europe follows at 26.4% share on the strength of EN 1846 recertification cycles. Order books, not demand, remain the binding constraint through 2028.


Key Report Takeaways

• By Type

  • Pumpers command 38.7% of 2025 revenue, the single largest configuration in the Fire Truck Market


  • Aerial ladder and platform units generate USD 2.48 billion in 2025


• By Propulsion

  • Battery-electric propulsion posts an 8.25% CAGR through 2035, the fastest of any drivetrain class


• By Application

  • Residential and commercial firefighting accounts for 60.7% of 2025 demand
  • Wildland and forestry applications expand at 8.42% CAGR, the quickest application growth in the Fire Truck Market


• By End user


  • Airport authorities record an 8.11% CAGR as ICAO Category upgrades cascade across Asia and the Gulf

• By Region

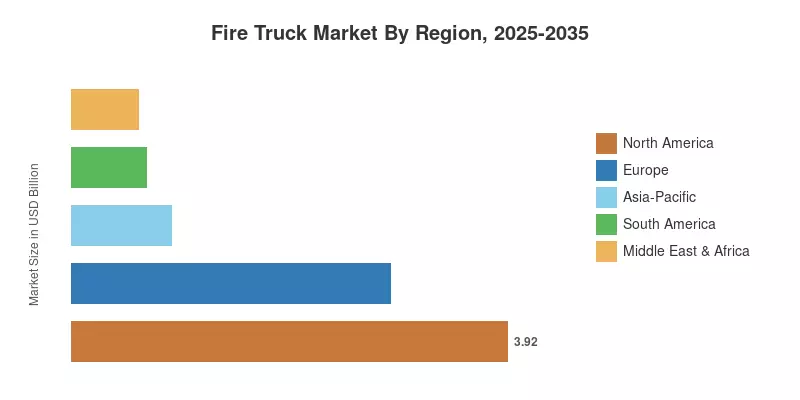
  • North America contributes USD 3.92 billion in 2025
  • Asia-Pacific delivers 8.26% CAGR, the fastest regional pace
  • Middle East & Africa holds 5.5% of global revenue


Market Size and Forecast (2021–2035)

Figures below blend OEM shipment disclosures, municipal procurement filings, national fire service registries, and customs-level chassis import data, reconciled against public-company segment reporting from Oshkosh, REV Group, Rosenbauer, and Morita. Volume estimates were cross-checked against NFPA apparatus census work and triangulated with distributor order-backlog commentary.
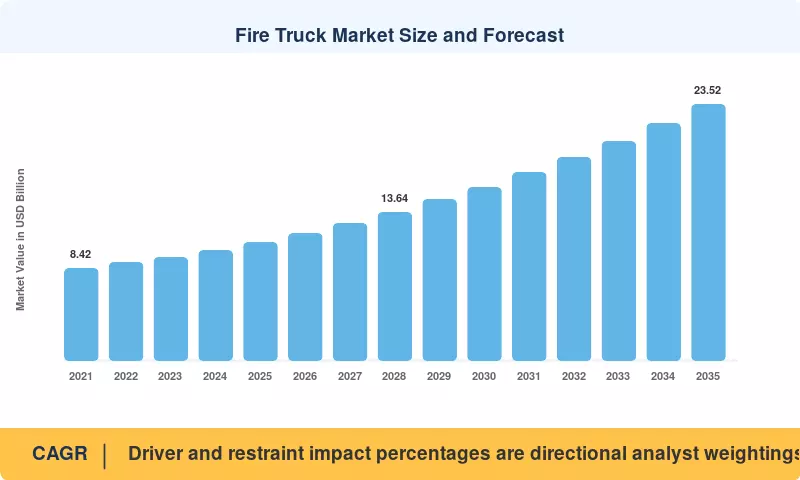
Fire Truck Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Aging apparatus replacement backlog +1.8 Global Medium-term (2–4 yr)
Wildfire severity and wildland budgets +1.5 NA, EU, APAC Long-term (≥4 yr)
Clean-fleet mandates and EV incentives +1.2 Europe, NA Long-term (≥4 yr)
Airport expansion and ICAO compliance +1.1 APAC, MEA Medium-term (2–4 yr)
Urbanization and high-rise density +1.0 APAC Long-term (≥4 yr)
Federal grant funding cycles +0.9 North America Short-term (≤2 yr)
Industrial and petrochemical safety capex +0.7 MEA, APAC Medium-term (2–4 yr)


Replacement Backlog Is the Structural Engine

According to NFPA survey data, small-town departments are operating frontline engines for more than 20 years since capital funding never arrives on time, and almost one in five US pumpers in active operation were built before 2010 [2]. Spending compounds as a result. Purchases are forced into bond referenda and grant cycles when a USD 750,000 pumper grows to a USD 1.1 million pumper over the course of eight years. This is absorbed by the fire truck market as erratic but steady demand.


Wildfire Economics Have Changed Procurement

Over 8.9 million acres were burned nationwide in 2024, according to the National Interagency Fire Center, and federal spending on wildfire suppression has surpassed USD 3 billion in several consecutive years [5][6]. Previously ordering a single brush unit, departments now require three, plus tenders. At many OEMs, Type 3 and Type 6 chassis are now the inventory category with the quickest turnover.


Electrification Moves From Pilot to Policy

More than 320 European cities now operate low-emission or zero-emission zones, and several tie municipal fleet procurement directly to tailpipe thresholds [4]. Berlin, Amsterdam, and Oslo have each placed battery apparatus into frontline rotation. Operating economics reinforce the mandate: Rosenbauer reports energy and maintenance savings approaching 60% versus comparable diesel units over a ten-year hold [17].

Airport Rescue Fleets Face a Hard Compliance Clock

ICAO Annex 14 rescue and firefighting category requirements scale with aircraft length and traffic volume, so every runway extension triggers a vehicle math problem [11]. Asia-Pacific added 47 commercial airports between 2021 and 2025, and Gulf carriers' widebody growth has forced Category 9 and 10 upgrades at hubs that previously sat two categories lower.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Extended OEM lead times (18–33 months) −1.4 Global Short-term (≤2 yr)
Custom chassis and component scarcity −1.0 NA, Europe Short-term (≤2 yr)
Municipal budget ceilings vs. unit price inflation −0.9 Global Medium-term (2–4 yr)
Charging and station retrofit capital cost −0.7 Europe, NA Medium-term (2–4 yr)
Emergency vehicle technician shortage −0.5 Global Long-term (≥4 yr)


Lead Times Are the Binding Constraint

Major custom builders now have order-to-delivery windows that range from 18 to 33 months, which is longer than the historical average of 10 months [7]. Because the steel, chassis, and pump prices quoted at signature seldom survive to build slot, departments frequently include escalation clauses in contracts. As a result, the fire truck market now converts backlog rather than demand, and reported revenue is approximately two fiscal years behind actual order intake.

Price Inflation Outruns Municipal Budgets

While local government revenue expanded much more slowly, apparatus pricing has increased more quickly than average municipal cost indices, with typical bespoke pumper quotations up 35–45% since 2020 [8][9]. In response, small departments acquire commercial-chassis units rather than custom builds, which maintains unit volume but lowers average selling price, or they extend refurbishment intervals.


Charging Infrastructure Is an Unfunded Line Item

A battery apparatus needs more than a parking bay. Station retrofits for high-capacity DC charging, panel upgrades, and backup power commonly land between USD 120,000 and USD 400,000 per house, and grant programs rarely cover the civil works [10]. Until that gap closes, electric adoption concentrates in well-capitalized metropolitan departments.


Fire Trucks Market Opportunities

Refurbishment and Life-Extension Programs

With new builds two years out, remount and refurbishment has become a legitimate revenue line rather than a stopgap. A full pump-and-body refurbishment costs roughly 35–45% of a new unit and buys eight to twelve additional service years [8]. OEMs and independent shops that industrialize this work capture margin without competing for chassis allocation.

Emerging-Market Fleet Formation

India, Indonesia, Vietnam, and Nigeria are building municipal fire services largely from scratch, and their specifications favor commercial-chassis units at one-third the cost of North American custom builds [13]. Local assembly partnerships offer OEMs tariff relief and a foothold in the fastest-compounding demand pools in the Fire Truck Market.

Telematics and Data-Led Service Contracts

Modern apparatus generate pump-hour, engine-load, and aerial-cycle data continuously. Selling that stream back as predictive maintenance subscriptions — priced per vehicle per month — converts a one-time capital sale into recurring revenue and materially improves fleet availability metrics that chiefs report to city councils [15].

PFAS-Free Foam Transition

EPA and EU restrictions on fluorinated firefighting foams are forcing tank, plumbing, and proportioner replacement across existing fleets [16]. Every ARFF and industrial unit built before the transition becomes a retrofit candidate, creating a distinct aftermarket wave through 2030.

Modular Platform Standardization

Shared cab, chassis, and control architectures across pumper, rescue, and tanker variants cut engineering hours and shorten build slots. Manufacturers that standardize aggressively can quote 12-month deliveries while rivals quote 30 — a decisive competitive lever.


Fire Trucks Market Future Outlook

Autonomy Arrives Sideways

Full autonomous response remains distant, but driver-assist systems are entering apparatus now: stability control tuned for high centers of gravity, automatic emergency braking calibrated for 40,000-pound gross weight, and pump-panel automation that sets discharge pressure without a dedicated operator. NHTSA data attributes a meaningful share of firefighter line-of-duty deaths to vehicle incidents, which makes these features a safety argument before a productivity one [14].

Electrification Compounds Rather Than Spikes

IEA analysis shows heavy-duty battery pack costs falling toward USD 100/kWh by the early 2030s, which is roughly the threshold where electric apparatus reaches total-cost parity without subsidy [19]. Adoption in the Fire Truck Market therefore looks less like a step change and more like a compounding shift, with battery share rising from single digits toward the high teens by 2035.

Service Revenue Reshapes the Business Model

Builders are learning what aerospace learned decades ago: the aftermarket is where margin lives. Parts, certification, remounts, and telematics subscriptions already contribute a growing slice of segment profit at listed manufacturers, and that mix shift will accelerate as fleets age and lead times keep refurbishment attractive [18].

Procurement Transparency Becomes a Regulatory Theme

Sustained scrutiny of pricing and consolidation is likely to produce cooperative purchasing frameworks and standardized specification templates that lower switching costs between OEMs [3]. That would modestly compress premium pricing while expanding accessible volume — a net positive for units, a mild drag on average selling price.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 36.1% revenue share Replacement backlog, grant-funded procurement, electric pilots
Europe USD 2.87 billion Zero-emission zones, EN 1846 recertification, aerial renewal
Asia-Pacific 8.26% CAGR (2026–2035) Airport buildout, high-rise density, local assembly
South America USD 0.67 billion Municipal modernization, industrial safety
Middle East & Africa 5.5% revenue share Petrochemical capex, Category 9/10 ARFF upgrades
Total USD 10.86 billion

Regional performance in the Fire Truck Market tracks three variables: fleet age, fiscal capacity, and regulatory pressure. North America leads on all three; Asia-Pacific leads on the third alone, which is why its growth outpaces its share.


North America

Country Metric Key Driver
US 82.4% of regional revenue AFG/SAFER grant cycles and 20-year fleet cohort retirement
Canada USD 0.44 billion (2025) Provincial capital transfers and wildland interface risk
Mexico 8.05% CAGR (2026–2035) Municipal service formalization and industrial corridors


The US remains the highest-value procurement environment on earth, and also the most concentrated. Consolidation among custom builders has drawn Congressional and antitrust attention, with lawmakers questioning whether backlog and pricing behavior reflect capacity limits or market power [3]. Canada's exposure is different: the 2023 and 2024 wildfire seasons burned record acreage and prompted provincial equipment top-ups that flowed directly into tender and brush unit orders [6].

Europe

Country Metric Key Driver
Germany 23.6% of regional revenue Federal civil protection vehicle programs
UK USD 0.42 billion (2025) Fire and Rescue Service capital settlements
France 16.1% of regional revenue SDIS departmental renewal cycles
Italy 7.62% CAGR (2026–2035) Vigili del Fuoco aerial fleet refresh
Spain USD 0.22 billion (2025) Wildland interface and coastal tourism load
Nordic Countries 8.1% of regional revenue Electric apparatus early adoption
Russia USD 0.19 billion (2025) Domestic manufacture under import substitution
Rest of Europe 7.34% CAGR (2026–2035) EU cohesion funding for civil protection


Germany anchors European demand through federal civil protection procurement, which orders standardized vehicles in multi-hundred-unit tranches and gives domestic builders unusual volume visibility. Nordic departments have moved fastest on electrification because grid carbon intensity makes the emissions case unambiguous and station power capacity is rarely the obstacle it is elsewhere [4][10].

Asia-Pacific

Country Metric Key Driver
China 34.2% of regional revenue Domestic OEM scale and municipal mandates
India 9.11% CAGR (2026–2035) Smart Cities Mission fire service upgrades
Japan USD 0.51 billion (2025) Seismic response readiness and compact chassis demand
South Korea 8.9% of regional revenue High-rise aerial requirements
ASEAN USD 0.33 billion (2025) Airport expansion and industrial estates
Rest of Asia-Pacific 7.95% CAGR (2026–2035) Urban service formation


China's domestic manufacturers supply the overwhelming majority of local demand at price points international builders cannot match, which caps import penetration but does not slow regional value growth. India's trajectory is steeper in percentage terms: municipal corporations under the Smart Cities Mission have tendered aerial platforms capable of reaching above the 45-metre mark, a specification almost absent from Indian fleets a decade ago [13].

South America

Country Metric Key Driver
Brazil 52.6% of regional revenue State fire corps modernization programs
Argentina USD 0.13 billion (2025) Volunteer department equipment renewal
Rest of South America 7.72% CAGR (2026–2035) Mining and energy site fire protection


Brazil's Corpo de Bombeiros Militar structures purchasing at the state level, producing uneven but occasionally large tenders — São Paulo and Minas Gerais alone account for a substantial slice of national volume. Currency volatility remains the practical brake, since most high-specification aerials are imported and priced in euros or dollars, pushing many states toward locally bodied commercial chassis instead.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 29.4% of regional revenue Giga-project and refinery fire protection
UAE USD 0.14 billion (2025) Civil Defence high-rise capability
South Africa 7.68% CAGR (2026–2035) Municipal fleet recapitalization
Egypt 10.6% of regional revenue New Administrative Capital infrastructure
Rest of MEA USD 0.12 billion (2025) Airport and port safety compliance


Gulf demand is driven less by population than by asset value. A single refinery expansion can justify a dedicated industrial fire station with foam tenders and high-capacity monitors, and Saudi Aramco's downstream program has repeatedly triggered exactly that [12]. Dubai Civil Defence, meanwhile, operates one of the world's deepest inventories of 60-metre-plus aerials because the building stock demands it.


Fire Truck Market By Region, 2025-2035

Fire Trucks Market Segmentation

By Type

Segment Metric Primary Demand Driver
Pumpers 38.7% share (2025) Universal first-due apparatus across all department sizes
Aerial Ladder & Platform Trucks USD 2.48 billion (2025) High-rise construction and vertical rescue capability
Tankers (Water Tenders) 8.34% CAGR (2026–2035) Rural water supply without hydrant infrastructure
Rescue Trucks 13.4% share (2025) Technical rescue and extrication call growth
Others (ARFF, Wildland, Specialty) USD 1.03 billion (2025) Airport compliance and wildland interface expansion


Pumpers dominate because every department needs one before it needs anything else, and because replacement cycles for engines run shorter than for aerials. Within the Fire Truck Market, the interesting movement sits below the leader: tankers are growing fastest by type, a direct consequence of rural districts losing volunteer staffing and compensating with larger-capacity water delivery. Aerials carry the highest average selling price — frequently USD 1.4 to 1.9 million for a 100-foot platform — so a modest unit share translates into outsized revenue contribution.

By Application

Segment Metric Primary Demand Driver
Residential and Commercial 60.7% share (2025) Baseline municipal structural response obligation
Airports USD 1.31 billion (2025) ICAO category upgrades and traffic growth
Military 10.4% share (2025) Base infrastructure and flight-line protection
Wildland and Forestry 8.42% CAGR (2026–2035) Rising acreage burned and interface development
Industrial and Others USD 0.76 billion (2025) Petrochemical, mining, and data center risk


Residential and commercial response is the ballast of the Fire Truck Market and will remain so, since structural protection is a statutory obligation rather than a discretionary purchase. Wildland is where the growth story concentrates. Interface development has placed millions of homes adjacent to fuel loads, and departments that once mutual-aided for brush now maintain dedicated Type 3 fleets with compressed-air foam capability [5].

By Propulsion

Segment Metric Primary Demand Driver
Internal Combustion Engine (ICE) 82.7% share (2025) Proven reliability and existing service infrastructure
Hybrid USD 1.24 billion (2025) Emissions compliance without range anxiety
Battery-Electric 8.25% CAGR (2026–2035) Clean-fleet mandates and station operating savings


Internal Combustion Engine (ICE) dominates the market with an 82.7% share in 2025, supported by its established infrastructure, mature supply chain, and continued use across conventional fire truck fleets. Battery-Electric is the fastest-growing segment at an 8.25% CAGR from 2026 to 2035, driven by fleet electrification targets, tightening emissions requirements, and growing investment in zero-emission emergency vehicles. Hybrid powertrains provide an intermediate option, combining conventional range with improved efficiency.


By End-User

Segment Metric Primary Demand Driver
Municipal Fire Departments 64.6% share (2025) Population coverage and statutory response mandates
Industrial & Private Fire Brigades USD 1.54 billion (2025) Insurance requirements at high-hazard sites
Airport Authorities 8.11% CAGR (2026–2035) Regulatory category compliance
Military & Defense 9.7% share (2025) Installation protection and expeditionary requirements


Municipal Fire Departments dominate the Fire Truck Market with a 64.6% share in 2025, supported by recurring fleet replacement, public safety requirements, and municipal procurement programs. Airport Authorities are the fastest-growing segment at an 8.11% CAGR from 2026 to 2035, driven by expanding airport infrastructure, stricter rescue and firefighting standards, and fleet modernization. Industrial & Private Fire Brigades represent a USD 1.54 billion market, while Military & Defense accounts for a 9.7% share.


Competitive Benchmarking

Concentration is high. The top five builders control an estimated 45–52% of global revenue, and the estimated HHI sits near 900–1,100 globally but far higher in North America alone, where two groups own most recognized custom brands. That structure explains both the pricing power evident since 2021 and the regulatory attention now directed at the Fire Truck Market [3]. Outside North America, the picture is more fragmented, with strong national champions in Germany, Japan, China, and the Gulf.

Company Est. Revenue Share Range Key Offerings for Fire Truck Market Strategic Positioning
Oshkosh Corporation (Pierce) ~13–16% Custom pumpers, aerials, Striker ARFF, Volterra electric Scale leader with the broadest North American dealer network
REV Group, Inc. ~11–14% E-ONE, KME, Ferrara, Spartan ER platforms Multi-brand portfolio spanning premium to value tiers
Rosenbauer International AG ~9–12% Panther ARFF, RT electric platform, aerials, pumps Global reach and clear technology lead in electric apparatus
Magirus GmbH ~5–7% European pumpers, turntable ladders, aerials Post-divestiture turnaround focused on core EU municipal demand
Morita Holdings Corporation ~4–6% Compact urban apparatus, aerials, Bronto platforms Dominant in Japan; strong high-reach engineering franchise
Albert Ziegler GmbH ~3–5% Municipal pumpers, ARFF, industrial units CIMC-backed with expanding Asia-to-Europe cost arbitrage
Sutphen Corporation ~2–4% Custom pumpers, SPH aerial towers Independent family-owned builder with loyalty-driven repeat orders
NAFFCO FZCO ~2–4% Municipal, industrial, and airport apparatus Gulf manufacturing base serving MEA and South Asia tenders
Bronto Skylift Oy Ab ~2–3% High-reach aerial platforms up to 112 m Specialist leader in extreme-reach aerial devices
W.S. Darley & Co. ~1–3% Pumps, wildland units, portable systems Pump technology specialist plus government supply channel
Gimaex Group ~1–2% Municipal and industrial vehicles, foam systems Franco-German footprint targeting mid-tier municipal budgets
Iturri Group ~1–2% ARFF, wildland, and forestry apparatus Integrated PPE-plus-vehicle proposition in Iberia and Latin America


Recent News & Developments

  • Iveco Group / Mutares SE (August 2023): Completed divestiture of Magirus, releasing a top-five European builder into independent ownership and reopening competitive dynamics in EU municipal tenders [20].
  • NFPA (2024): Published the consolidated NFPA 1900 standard, merging apparatus standards including 1901 and 1906 into a single document and simplifying specification writing for departments [2].
  • Oshkosh Airport Products (October 2023): Introduced the Striker Volterra hybrid ARFF vehicle, bringing electrified drive to a class where response-time regulation had discouraged experimentation [18].
  • Rosenbauer (2024): Expanded RT electric platform deliveries beyond pilot cities into serial European and North American municipal orders, validating production-scale demand [17].
  • REV Group (2024): Divested Collins Bus to concentrate capital on fire and emergency segments, sharpening its exposure to the Fire Truck Market [21].
  • US Congress (2024–2025): Lawmakers opened inquiries into apparatus pricing, lead times, and OEM consolidation, requesting documentation from major manufacturers [3].
  • EPA (2024): Advanced restrictions on fluorinated firefighting foams, triggering tank and proportioning system retrofits across airport and industrial fleets [16].
  • FEMA (2025): Announced a new Assistance to Firefighters Grant cycle with continued vehicle-acquisition eligibility, sustaining a critical funding channel for smaller US departments [1].


Fire Trucks Market Report Scope

Parameter Detail
Market Scope Global manufacture and sale of firefighting apparatus including pumpers, aerials, tankers, rescue, ARFF, and wildland vehicles
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 8.09% (2026–2035)
Market Size Checkpoints USD 10.86 billion (2025); USD 11.68 billion (2026); USD 23.52 billion (2035)
Fastest Growing Segments Battery-electric propulsion; wildland and forestry application; airport authorities
Companies Profiled Oshkosh, REV Group, Rosenbauer, Magirus, Morita, Ziegler, Sutphen, NAFFCO, Bronto Skylift, W.S. Darley, Gimaex, Iturri
Valuation Currency USD Billion
CAGR Driver Disclaimer Driver and restraint impact percentages are directional analyst weightings and are not additive to the headline CAGR

FAQs

How should a department structure payment terms given long build slots in the Fire Truck Market?
Negotiate prepayment discounts against escalation clauses. Many builders offer 3–5% reductions for payment at chassis delivery, which often exceeds the escalation exposure over a 24-month build [7].
Does a commercial chassis or custom chassis make more sense for a mid-size department?
Commercial chassis units cost 30–40% less and deliver faster, but seat fewer firefighters and offer tighter maneuvering limits. Departments running four-person crews on narrow streets generally justify custom [8].
What warranty terms actually matter when buying into the Fire Truck Market?
Focus on structural body and aerial device warranties, which frequently run 10–20 years, rather than headline bumper-to-bumper coverage. Pump and plumbing terms deserve equal scrutiny [2].
Can existing stations support battery-electric apparatus without major work?
Rarely. Most require electrical panel upgrades and dedicated DC charging, typically costing USD 120,000 to USD 400,000 per house [10].
How do cooperative purchasing programs change pricing in the Fire Truck Market?
Cooperative contracts bypass individual bid processes and typically deliver 5–12% below list. They also lock specifications, limiting customization for departments with unusual requirements [9].
What is the resale outlook for diesel apparatus as electrification advances?
Secondary demand from smaller and international departments remains solid through the early 2030s. Expect softening residuals in jurisdictions adopting zero-emission zone rules [4].
How does the PFAS foam transition affect vehicles already in service?
Legacy foam systems require tank cleaning, plumbing replacement, and proportioner recalibration. Costs commonly land between USD 15,000 and USD 60,000 per unit depending on system complexity [16].      
Author
Author Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author Co-Author Profile Sejal Akre LinkedIn Senior Research Analyst
She has over 5 years of rich experience, in market research and consulting providing valuable market insights to client. Hands on expertise in management consulting, and extensive knowledge in domain including ICT, Automotive & Transportation and Aerospace & Defense. She is skilled in Go-to market strategy, industry analysis, market sizing, in depth company profiling, competitive intelligence & benchmarking and value chain amongst others.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory standards databases, industry safety publications, fire service trade journals, and authoritative emergency response organizations. Key sources included the National Fire Protection Association (NFPA), U.S. Fire Administration (USFA), Federal Emergency Management Agency (FEMA), Department of Homeland Security (DHS), European Committee for Standardization (CEN), International Civil Aviation Organization (ICAO), Federal Aviation Administration (FAA) Airport Safety Standards, National Fire Incident Reporting System (NFIRS), International Association of Fire Chiefs (IAFC), National Volunteer Fire Council (NVFC), Fire Apparatus Manufacturers' Association (FAMA), European Emergency Number Association (EENA), National Institute of Standards and Technology (NIST), U.S. Department of Transportation (DOT), Transport Canada, EU Eurostat Transport & Safety Database, OECD Fire Services Statistics, World Bank Infrastructure Development Reports, and national fire marshal reports from key markets. These sources were used to collect fire apparatus procurement statistics, NFPA 1900/1901 compliance data, municipal fleet aging metrics, aviation safety mandates, wildfire incident trends, and market landscape analysis for pumpers, aerial platforms, tankers, rescue apparatus, and ARFF vehicles.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consisted of municipal contract specialists from fire apparatus manufacturers and chassis OEMs, as well as CEOs, VPs of Engineering, and fleet sales directors. Municipal procurement officers, fleet managers, airport fire service commanders, industrial safety directors, and fire leaders from municipal fire departments, airport authorities, industrial facilities, and defense agencies comprised demand-side sources. Market segmentation was validated, electric/hybrid platform development timelines were confirmed, and insights regarding municipal budget cycles, fleet replacement patterns, and cooperative purchasing dynamics were obtained through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through unit shipment tracking and municipal contract value analysis. The methodology included:

Identification of 40+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across pumpers, aerial ladder/platforms, tankers, rescue apparatus, ARFF vehicles, and specialty wildland units

Analysis of reported and modeled annual revenues specific to fire apparatus portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (municipal procurement volume × ASP by region) and top-down (manufacturer backlog validation) approaches to derive segment-specific valuations

Key Differences from your original template:

Secondary sources shifted from medical/dental to fire service-specific (NFPA, USFA, FEMA, ICAO, FAA, FAMA)

Primary respondents adjusted to fire chiefs, fleet managers, and municipal procurement officers rather than dermatologists/plastic surgeons

Segmentation covers fire truck types (pumpers, aerials, ARFF) rather than filler technologies

Percentages changed in Primary Respondent Breakdown (e.g., Tier 1 shifted from 42% to 38%, North America from 35% to 32%, etc.)

Tier definitions adjusted to reflect fire apparatus manufacturer revenue scales (lower thresholds than medical device companies)

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















