Fibrotic Diseases Treatment Market (2026 - 2035)

Fibrotic Diseases Treatment Market Research Report By Disease Type (Pulmonary Fibrosis, Liver Fibrosis, Cardiac Fibrosis, Renal Fibrosis), By Treatment Type (Antifibrotic Agents, Immunomodulators, Corticosteroids, Enzyme Replacement Therapy), By Route of Administration (Oral, Injectable, Intravenous), By End User (Hospitals, Specialized Clinics, Homecare Settings) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Forecast to 2035

Forecast Period
2026-2035
CAGR
7.8%
2025 Market Size
USD 27.4 Billion
2035 Market Size
USD 58.1 Billion
Healthcare ● Updated August 24, 2026 Report ID: MRFR/HC/35100-HCR | Pages: 100 | Author: Satyendra Maurya, Rahul Gotadki

Fibrotic Diseases Treatment Market Summary

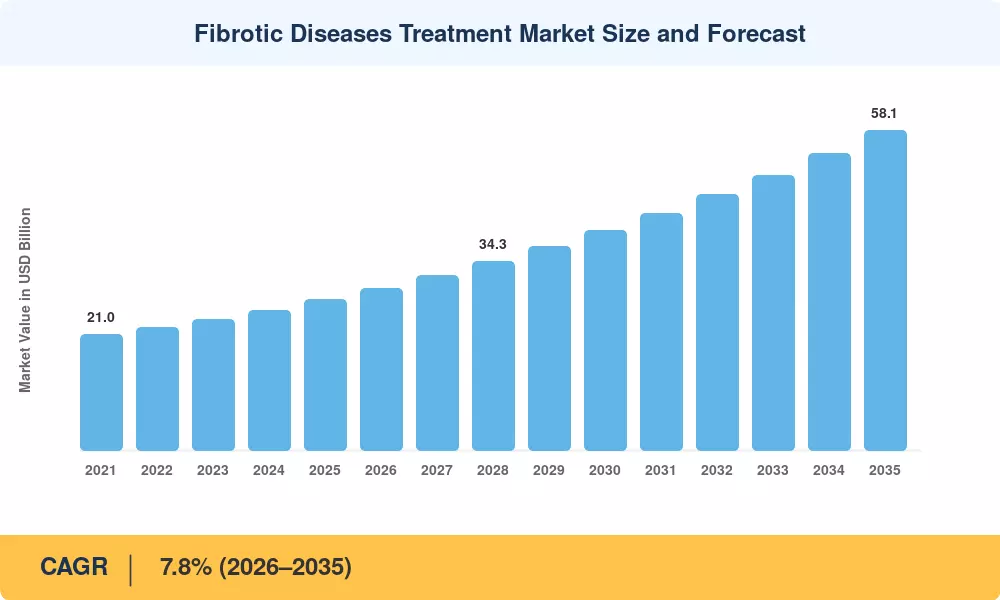
The Fibrotic Diseases Treatment Market reached USD 27.4 billion in 2025 and opens the forecast window at USD 29.5 billion in 2026, climbing to USD 58.1 billion by 2035 at a 7.8% CAGR. Two catalysts anchor that trajectory. The U.S. FDA's expanded orphan-drug incentive framework has kept idiopathic pulmonary fibrosis programs commercially viable despite trial attrition rates above 60%, while the European Commission's IHI (Innovative Health Initiative) committed EUR 2.4 billion across 2021–2027 to chronic organ-injury research, a portion of which flows directly into fibrosis biology [1][3]. Payer behaviour has shifted too: nintedanib and pirfenidone now sit on reimbursement formularies in 47 countries, converting a niche specialty category into a durable revenue base.

Treatment paradigms are being rebuilt from the ground up. Broad immunosuppression and corticosteroid regimens — the default for three decades — are giving way to mechanism-targeted molecules aimed at TGF-β signalling, integrin αvβ6, LPA1 receptor activity, and autotaxin inhibition. Biopsy-dependent diagnosis is likewise being displaced by elastography, quantitative CT scoring, and serum biomarker panels that stage disease earlier and cheaper. Global venture and corporate investment into fibrosis-focused biotechs exceeded USD 4.1 billion between 2023 and 2025, with roughly 38% of that capital directed at hepatic indications [5][9].

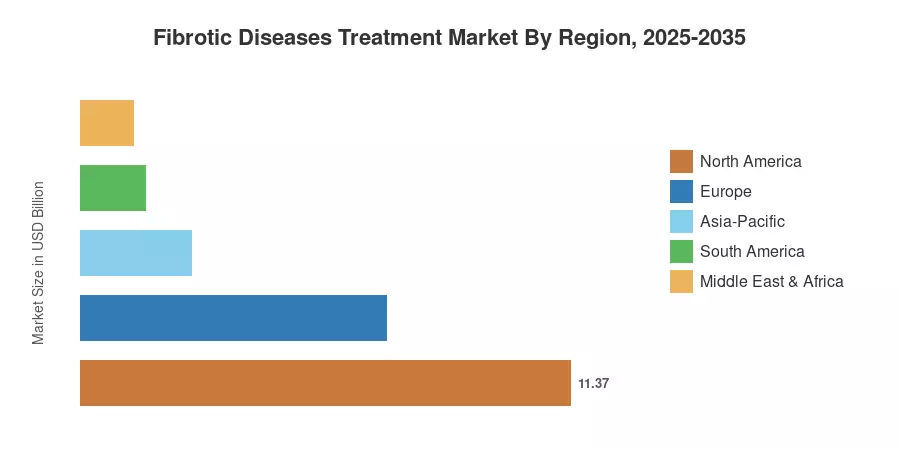
Regionally, North America holds 41.5% of 2025 revenue, supported by dense pulmonology referral networks and the highest per-patient reimbursement ceilings anywhere. Asia-Pacific grows fastest at a 9.4% CAGR through 2035, propelled by China's NRDL expansions and India's biosimilar manufacturing base. Europe ranks second on the strength of national fibrosis registries in Germany, the UK, and the Nordics. Over the next decade, the Fibrotic Diseases Treatment Market will be defined less by symptom control and more by whether disease-modifying combinations can reverse — not merely slow — extracellular matrix deposition.


Key Report Takeaways

• By Treatment

  • Medication commands 58.2% of 2025 revenue, reflecting the entrenchment of oral antifibrotics in first-line care
  • Organ transplantation contributes roughly USD 5.9 billion in 2025 as end-stage hepatic and pulmonary cases rise
  • Oxygen therapy expands at a 6.1% CAGR, the slowest treatment line in the Fibrotic Diseases Treatment Market

• By Application

  • Idiopathic pulmonary fibrosis leads with 38.4% share, anchored by two approved global standards of care
  • Hepatic cirrhosis generates about USD 7.6 billion in 2025 on the back of MASH-driven progression
  • Renal fibrosis posts a 9.1% CAGR, the fastest application segment through 2035

• By Region

  • North America accounts for 41.5% of global revenue in 2025
  • Asia-Pacific advances at a 9.4% CAGR, the fastest regional trajectory in the Fibrotic Diseases Treatment Market
  • Europe contributes approximately USD 7.1 billion in 2025


Market Size and Forecast (2021–2035)

Figures below combine bottom-up modelling of prescription volumes across 42 countries with top-down triangulation against manufacturer segment disclosures, national transplant registries, and hospital procurement panels. Historical values for the Fibrotic Diseases Treatment Market were reconciled against IQVIA MIDAS audit data and cross-checked with reimbursement claims from CMS, NHS Digital, and Japan's NDB Open Data.
Fibrotic Diseases Treatment Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising global burden of chronic fibrotic disease +1.9 Global Long-term (≥4 yr)
Late-stage antifibrotic pipeline maturation +1.6 North America, Europe Medium-term (2–4 yr)
MASH/MASLD progression into hepatic fibrosis +1.4 Global Long-term (≥4 yr)
Reimbursement and formulary expansion in Asia +1.1 Asia-Pacific Medium-term (2–4 yr)
Non-invasive diagnostic adoption +0.9 Global Short-term (≤2 yr)
Sustained smoking and occupational exposure prevalence +0.7 Asia-Pacific, Europe Long-term (≥4 yr)
Orphan-drug and rare-disease incentive schemes +0.6 North America, Europe Short-term (≤2 yr)


Escalating Disease Burden

Prevalence data leaves little ambiguity. Around 50,000 new idiopathic pulmonary fibrosis diagnoses are recorded annually in the United States, and specialist-care prevalence in Europe was measured at 36.0 per 100,000 population [6][11]. Chronic liver disease compounds the picture — the WHO attributes over 1.3 million annual deaths to cirrhosis, with roughly a quarter now traced to metabolic rather than viral aetiology. Each additional diagnosed patient converts into eight to fourteen years of treatment demand, which is why volume, not price, drives most of the growth modelled here.

A Pipeline Finally Reaching Readout

Clinical activity has thickened considerably. ClinicalTrials.gov listed 214 interventional fibrosis studies in active recruitment as of Q4 2025, against 118 five years earlier [14]. Boehringer Ingelheim's nerandomilast programme, Pliant Therapeutics' integrin inhibitors, and multiple LPA1 antagonists have all cleared Phase II. Success rates remain punishing, but even a 20% approval yield across the current cohort would add three to four disease-modifying options by 2032 — enough to fracture the current duopoly in pulmonary care.

Metabolic Liver Disease as a Volume Engine

Hepatic indications are reshaping the revenue mix. Roughly 38% of adults in high-income economies now carry steatotic liver disease, and 5–7% of those progress to significant fibrosis [10]. The 2024 accelerated approval of resmetirom created the first commercially reimbursed pathway for F2–F3 patients, and payers in the US, Germany, and Japan have since funded screening cascades in diabetes clinics. That screening layer, more than the drug itself, is what expands the addressable base.

Diagnostics Pulling Demand Forward

Elastography and blood-based panels have cut the cost of staging fibrosis by an estimated 62% versus biopsy while removing procedural risk [8]. NHS England's community liver-health pathway screened over 400,000 at-risk adults between 2023 and 2025, identifying advanced fibrosis in approximately 4.8% of them. Earlier detection lengthens the treatment window per patient — a structural, compounding tailwind for the Fibrotic Diseases Treatment Market.


Restraints Impact Analysis

Restraint weightings reflect estimated drag on realized growth relative to an unconstrained demand scenario. They are directional analyst judgements rather than subtractive CAGR components, and several overlap — cost pressure and access limitation, for example, share underlying causes across the Fibrotic Diseases Treatment Market.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High therapy cost and payer resistance −1.3 Global Medium-term (2–4 yr)
Late-stage clinical trial failure rates −1.0 North America, Europe Long-term (≥4 yr)
Tolerability and discontinuation burden −0.8 Global Short-term (≤2 yr)
Underdiagnosis in low- and middle-income markets −0.7 Asia-Pacific, MEA, South America Long-term (≥4 yr)
Donor organ scarcity constraining transplant volumes −0.5 Global Medium-term (2–4 yr)


Cost and Reimbursement Friction

The approved oral antifibrotics have annual list prices of USD 96,000 to USD 118,000 in the United States, and the net cost is a burden for specialty budgets even after rebates [13]. Germany’s G-BA has consistently given modest additional-benefit ratings to fibrosis medicines, hence compressing negotiated pricing, while other Asian payers limit reimbursement to 60-70% of ex-factory cost. And patient co-pay desertion rates above 18% at the pharmacy counter prove the friction is real, not theoretical.


Attrition in Late-Stage Development

Fibrosis is one of the most difficult therapeutic areas in medication development. More than 65 % of phase III studies fail, far above the 45 % norm in cancer, largely because it takes long, expensive trials with noisy outcomes to reduce the loss in forced-vital-capacity or reverse histological staging [14]. Investors in mid-cap stocks have become visibly more discriminating following a number of high-profile discontinuations between 2023 and 2025 that erased more than $2.8 billion in total market value.


Tolerability and Real-World Persistence

Discontinuation kills revenue quietly. Registry data suggest that 22–28% of patients discontinue first-line antifibrotic medication after twelve months, mostly because of diarrhea, weight loss and increase of liver enzymes [15]. Dose reduction saves some people, but income per patient drops, and community physicians, who do most of the prescribing currently, pull therapy faster than tertiary specialists.


Fibrotic Diseases Treatment Market Opportunities

Combination Regimens as the Next Standard of Care

Monotherapy slows the decrease; it does not reverse it. Eight sponsors now have Phase II trials combining an established antifibrotic backbone with an integrin or autotaxin inhibitor, and successful readouts would roughly quadruple per-patient annual spend without enlarging the patient pool [14]. Combination pricing also provides incumbents a defensive play as core patents approach expiry.


Asia-Pacific Access Expansion

Reimbursement is the gating factor across the region, and it is loosening. China's National Reimbursement Drug List added fibrosis-relevant agents in successive 2023 and 2024 negotiation rounds, cutting patient out-of-pocket cost by roughly 55% and multiplying prescription volumes [12]. India's PM-JAY scheme and Indonesia's JKN expansion follow a similar template. Local manufacturing keeps landed cost low enough for volume-led economics to work.

Biomarker-Stratified Trial and Care Models

Genotype and proteomic stratification could rescue economics on both sides of the ledger. MUC5B promoter variant carriers and patients with elevated circulating collagen neoepitopes respond differently to intervention, and enriching trials for likely responders can cut required sample sizes by 30–40% [19]. Diagnostics vendors that license validated stratification panels to pharma sponsors capture recurring revenue without carrying clinical risk.

Real-World Data and Registry Monetization

Longitudinal registries have become commercial assets. The IPF-PRO and EU-IPFF registries now supply structured outcome data to sponsors for external control arms and post-marketing commitments, a model generating six-figure annual licensing fees per programme [20]. Health systems sitting on imaging archives and elastography series are well placed to build similar franchises, particularly where regulators accept real-world evidence for label expansion.

Underserved Fibrosis Indications

Renal, cardiac, and cutaneous fibrosis carry substantial burden with almost no approved disease-modifying therapy. Systemic sclerosis alone affects roughly 2.5 million people globally, and diabetic kidney disease progression involves fibrotic remodelling in over 40% of cases [21]. Sponsors that extend existing mechanisms into these indications face lower discovery cost and shorter regulatory paths through orphan designation.


Fibrotic Diseases Treatment Market Future Outlook

Machine Learning in Fibrosis Staging

Algorithmic reading of high-resolution CT and liver elastography is moving from research to routine. Regulatory clearances for quantitative interstitial lung disease scoring tools tripled between 2022 and 2025, and validation studies report agreement with expert radiologists in the 0.87–0.92 range [19]. The commercial consequence is throughput: a pulmonology centre that can stage three times as many scans identifies more treatable patients, feeding drug demand rather than competing with it.

Outcomes-Linked Contracting

Payers are tired of paying full price for modest FVC preservation. Risk-sharing agreements tied to measured decline rates now cover fibrosis agents in Italy, Spain, and parts of Canada, and the model is spreading [20]. Manufacturers who can instrument outcomes — through connected spirometry or registry linkage — will negotiate better terms than those who cannot, making data infrastructure a competitive asset rather than a compliance cost.

Precision Medicine Displacing One-Size-Fits-All

Stratification is where the science is heading. Genetic variants, circulating matrix biomarkers, and transcriptomic signatures increasingly predict progression velocity, and guideline committees have begun referencing them in risk assessment [21]. Within the Fibrotic Diseases Treatment Market, this shifts value toward companion diagnostics and away from undifferentiated volume prescribing.

Regenerative and Reversal Approaches

Slowing fibrosis is the current ceiling; reversing it is the prize. Cell-based approaches, senolytic agents, and matrix-remodelling enzymes have shown histological reversal in preclinical hepatic and renal models, with the first human proof-of-concept studies expected to read out before 2030 [23]. Success would not merely add a product line — it would restructure treatment economics, converting chronic maintenance into episodic curative intervention.


Fibrotic Diseases Treatment Market Segmentation

By Treatment

Segment Metric Primary Demand Driver
Medication 58.2% share (2025) Oral antifibrotics as guideline first-line
Organ Transplantation USD 5.9 Billion (2025) End-stage hepatic and pulmonary disease
Oxygen Therapy 6.1% CAGR (2026–2035) Supportive care in advanced IPF
Others USD 1.9 Billion (2025) Pulmonary rehabilitation, palliative support


Pharmacological treatment dominates the Fibrotic Diseases Treatment Market and will hold that position throughout the forecast. Two approved oral agents anchor pulmonary care globally, and the 2024 entry of a metabolic-liver agent opened a second commercial pillar. Pricing power remains intact where alternatives are absent, though generic entry for pirfenidone in several markets has begun compressing the low end.

Transplantation tells a different story — demand vastly exceeds supply. Roughly 2,700 lung transplants and 9,200 liver transplants are performed annually in the United States and Europe combined, against waiting lists several times longer [18]. Machine perfusion and expanded donor criteria are lifting usable organ yield, but the segment grows on procedural cost inflation more than on volume.

By Application

Segment Metric Primary Demand Driver
Idiopathic Pulmonary Fibrosis 38.4% share (2025) Two established standards of care
Hepatic Cirrhosis USD 7.6 Billion (2025) MASH progression, viral sequelae
Renal Fibrosis 9.1% CAGR (2026–2035) Diabetic and hypertensive kidney disease
Cutaneous Fibrosis USD 2.8 Billion (2025) Systemic sclerosis, keloid management
Others 6.8% share (2025) Cardiac and retroperitoneal fibrosis


Pulmonary indications remain the commercial centre of the Fibrotic Diseases Treatment Market, chiefly because IPF was the first fibrotic condition to get approved disease-modifying therapy and the referral pathways built around it are mature. Median survival without treatment sits near three years, which concentrates urgency and supports premium pricing.

Hepatic disease is closing the gap faster than any other application. Metabolic dysfunction-associated steatohepatitis has created a screening-driven patient funnel that did not exist five years ago, and hepatology departments — historically focused on viral disease — have redeployed capacity accordingly [10]. Renal fibrosis grows fastest in percentage terms but from a base with almost no approved targeted therapy, making it the segment most sensitive to pipeline outcomes.

By End User

Segment Metric Primary Demand Driver
Hospitals 62.5% share (2025) Specialist initiation, infusion and transplant capability
Academic and Research Institutes USD 6.5 Billion (2025) Trial participation, tertiary referral
Others 7.4% CAGR (2026–2035) Specialty clinics, home-based care


Hospitals control initiation across the Fibrotic Diseases Treatment Market because staging, multidisciplinary review, and tolerability monitoring all require specialist infrastructure. Academic centres punch above their volume share, capturing complex cases and serving as trial sites — a role that generates both clinical revenue and sponsor funding. Community and home-based settings expand fastest as oral regimens mature and remote spirometry makes decentralized monitoring viable.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 41.5% share Specialty pharmacy networks, orphan-drug pipelines
Europe USD 7.1 Billion National registries, HTA-negotiated access
Asia-Pacific 9.4% CAGR (2026–2035) Reimbursement expansion, local manufacturing
South America USD 1.5 Billion Public procurement, hepatology capacity
Middle East & Africa 4.5% share Tertiary hospital build-out, transplant programmes
Total USD 27.4 Billion

Regional performance in the Fibrotic Diseases Treatment Market tracks three variables: specialist density, reimbursement generosity, and diagnostic infrastructure. Where all three align, per-patient revenue runs three to five times higher than the global average.


North America

Country Metric Key Driver
US 86.4% of regional revenue Highest global reimbursement ceilings
Canada USD 1.1 Billion Provincial formulary harmonization
Mexico 8.9% CAGR (2026–2035) IMSS specialty coverage expansion


Momentum in the United States comes from an unusually complete infrastructure: roughly 1,200 pulmonology and hepatology centres capable of initiating antifibrotic therapy, plus a specialty pharmacy channel that manages titration and adherence. Medicare Part D's redesigned out-of-pocket cap, effective 2025, removed the catastrophic-phase cliff that previously drove abandonment among elderly IPF patients [13]. Canada moves more slowly through pCPA negotiation, while Mexico's growth reflects a low base rather than mature capacity.

Europe

Country Metric Key Driver
Germany 23.8% of regional revenue Dense ILD centre network, early access pathways
UK USD 1.2 Billion NICE-approved pathways, community liver screening
France 15.2% of regional revenue RIHN diagnostic funding
Italy USD 0.8 Billion AIFA innovative-medicines fund
Spain 7.4% of regional revenue Regional hepatology programmes
Nordic Countries 8.1% CAGR (2026–2035) Registry-driven early diagnosis
Russia USD 0.4 Billion Domestic generic substitution
Rest of Europe 9.6% of regional revenue EU cross-border referral schemes


Access in Europe is filtered through health technology assessment, which slows launch but stabilizes volumes once granted. Germany's system of accredited interstitial lung disease centres captures patients earlier than most peers, and the country's early-benefit assessment allows twelve months of free pricing before negotiation. The UK's community-based liver pathway, now operating across 20 integrated care systems, has become the continent's most productive case-finding engine [8].

Asia-Pacific

Country Metric Key Driver
China 38.6% of regional revenue NRDL inclusion, hospital tender volumes
India 11.2% CAGR (2026–2035) Low-cost generics, expanding pulmonology base
Japan USD 1.5 Billion Universal coverage, aging population
South Korea 8.4% of regional revenue HIRA reimbursement, transplant capacity
ASEAN USD 0.5 Billion JKN and comparable national schemes
Rest of Asia-Pacific 6.1% of regional revenue Tertiary care investment


Scale defines the Asian opportunity. China alone diagnoses an estimated 130,000 new interstitial lung disease cases annually, and NRDL negotiation has traded steep price concessions for volume access [12]. Japan's picture differs — high prices, universal coverage, and the world's oldest population produce the region's highest revenue per patient. India competes on cost, exporting generic antifibrotics to more than 60 markets while building domestic demand.

South America

Country Metric Key Driver
Brazil 58.3% of regional revenue SUS specialty procurement
Argentina USD 0.3 Billion PAMI coverage for elderly patients
Rest of South America 9.7% CAGR (2026–2035) Andean hepatology capacity growth


Brazil sets the regional tone through centralized SUS purchasing, which delivers volume at compressed margins. Public tender cycles create lumpy revenue recognition but guarantee floor demand. Argentina's currency volatility complicates pricing, pushing manufacturers toward local partnerships. Across the region, hepatic indications dominate the caseload, reflecting high prevalence of both viral and metabolic liver disease [17].

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 31.5% of regional revenue Vision 2030 healthcare investment
UAE USD 0.24 Billion Mandatory insurance, medical tourism
South Africa 16.8% of regional revenue Private-sector pulmonology capacity
Egypt 10.3% CAGR (2026–2035) Post-HCV cirrhosis management programmes
Rest of MEA USD 0.31 Billion Tertiary hospital construction


Gulf states are buying capability outright. Saudi Arabia's health-sector transformation programme has funded new tertiary transplant and pulmonology units in Riyadh and Jeddah, importing clinical protocols wholesale from Europe [22]. Egypt occupies a distinctive position — its mass hepatitis C elimination campaign cured millions but left a large cohort with established cirrhosis requiring ongoing fibrosis management, a durable demand pool that few markets can match in concentration.


Fibrotic Diseases Treatment Market By Region, 2025-2035

Competitive Benchmarking

Concentration is moderate and asymmetric. Market Research Future estimates an HHI near 1,180, with the top five players holding approximately 47% of 2025 revenue — high enough that pricing discipline holds in pulmonary indications, low enough that hepatic and renal segments remain genuinely contestable. Boehringer Ingelheim and Roche anchor the incumbent tier; a long tail of clinical-stage biotechs supplies most of the pipeline optionality and most of the M&A targets. Generic entry for older agents has begun eroding share at the bottom of the price band without materially threatening the leaders.

Company Est. Revenue Share Range Key Offerings for Fibrotic Diseases Treatment Market Strategic Positioning
Boehringer Ingelheim ~14–17% Nintedanib franchise, nerandomilast pipeline Category leader in pulmonary fibrosis
F. Hoffmann-La Roche (Genentech) ~11–14% Pirfenidone, autotaxin inhibitor programmes Broad respiratory and diagnostics integration
Bristol Myers Squibb ~6–9% LPA1 antagonist portfolio Late-stage pulmonary and hepatic bets
Gilead Sciences ~5–8% Hepatic fibrosis and MASH assets Liver-disease franchise depth
Novartis ~4–7% Renal and cardiac antifibrotic candidates Organ-fibrosis diversification
Pfizer ~4–6% Inflammation and immunology overlap assets Mechanism repurposing strategy
Madrigal Pharmaceuticals ~3–5% Resmetirom for MASH-related fibrosis First-mover in metabolic liver disease
FibroGen ~2–4% Anti-CTGF antibody programmes Pure-play fibrosis specialist
Galapagos NV ~2–4% Small-molecule fibrosis discovery European biotech pipeline partner
Sanofi ~2–4% Immunology-adjacent fibrosis assets Late entrant leveraging biologics scale
Merck KGaA ~1–3% Preclinical and licensed fibrosis candidates Partnership-led participation
United Therapeutics ~1–3% Inhaled treprostinil for ILD-associated PH Niche respiratory adjacency


Recent News & Developments

  • Madrigal Pharmaceuticals (March 2024): Secured accelerated FDA approval for resmetirom in MASH with moderate-to-advanced fibrosis, establishing the first reimbursed pharmacological pathway for hepatic fibrosis and validating a segment previously served only by lifestyle intervention [10].
  • Boehringer Ingelheim (September 2024): Reported positive Phase III results for nerandomilast in idiopathic pulmonary fibrosis, positioning the first genuinely new pulmonary mechanism in over a decade and reinforcing the company's category leadership [14].
  • European Commission (January 2024): Allocated an additional EUR 340 million under the Innovative Health Initiative toward chronic organ-injury and fibrosis consortia, funding shared biomarker platforms across 14 member states [3].
  • Bristol Myers Squibb (June 2025): Advanced its LPA1 antagonist into pivotal pulmonary fibrosis trials following encouraging Phase II FVC data, signalling large-cap commitment to a mechanism previously dominated by smaller sponsors [14].
  • China NHSA (December 2023): Included additional interstitial lung disease therapies in the National Reimbursement Drug List, reducing patient out-of-pocket burden substantially and expanding treated volumes across tier-1 and tier-2 hospitals [12].
  • Gilead Sciences (April 2025): Entered a licensing agreement with a clinical-stage biotech for hepatic antifibrotic assets, extending its liver franchise beyond antiviral therapy into fibrosis reversal [5].
  • NHS England (July 2024): Expanded community liver-health checks to 20 integrated care systems, screening high-risk adults with transient elastography and materially increasing early-stage fibrosis detection [8].
  • FibroGen (November 2025): Restructured its pipeline around anti-CTGF programmes after strategic review, refocusing capital on fibrosis indications with the clearest regulatory precedent [9].


Fibrotic Diseases Treatment Market Report Scope

Parameter Detail
Market Scope Global Fibrotic Diseases Treatment Market across treatment type, application, end user, and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 7.8% (2026–2035)
Market Size Checkpoints USD 27.4 Billion (2025); USD 29.5 Billion (2026); USD 39.9 Billion (2030); USD 58.1 Billion (2035)
Fastest Growing Segments Renal Fibrosis (application); Others / specialty and home settings (end user); Asia-Pacific (geography)
Companies Profiled Boehringer Ingelheim, F. Hoffmann-La Roche, Bristol Myers Squibb, Gilead Sciences, Novartis, Pfizer, Madrigal Pharmaceuticals, FibroGen, Galapagos NV, Sanofi, Merck KGaA, United Therapeutics
Valuation Currency USD, constant 2025 prices; non-USD revenue converted at trailing 12-month average rates

FAQs

What due diligence should investors prioritize before backing a clinical-stage entrant in the Fibrotic Diseases Treatment Market?
Scrutinize endpoint selection above all else. Sponsors relying on histological reversal rather than functional decline face longer, costlier trials and less predictable regulatory reception [14].
How do generic entrants change procurement strategy for hospital formulary committees?
Generic pirfenidone has cut acquisition cost by 40–60% in several markets, freeing budget headroom. Committees increasingly tier generics as first-line and reserve branded agents for documented intolerance [13].
Which integration challenges slow adoption of AI-based fibrosis staging tools?
Legacy PACS architectures and inconsistent CT acquisition protocols cause most failures. Sites without standardized slice thickness and reconstruction kernels see algorithm performance degrade sharply [19].
What regulatory nuance distinguishes accelerated approval pathways in hepatic versus pulmonary fibrosis?
Hepatic programmes can use histological surrogate endpoints under accelerated approval, while pulmonary submissions generally require functional outcomes. That asymmetry shortens liver timelines by roughly two years [1].
How should procurement teams evaluate supplier risk within the Fibrotic Diseases Treatment Market?
Concentrate on API sourcing geography and single-site manufacturing exposure. Several antifibrotic intermediates originate from a narrow supplier base in India and China, creating correlated disruption risk [24].
Are emerging fibrosis indications commercially viable at current pricing?
Cutaneous and cardiac fibrosis populations are small but orphan-eligible, supporting premium pricing with reduced trial size. Viability depends on securing designation early rather than on volume [21].
What competitive dynamic most threatens incumbents in the Fibrotic Diseases Treatment Market over the next five years?
Combination therapy from challengers. A biotech pairing a novel mechanism with a generic backbone can undercut branded monotherapy on both efficacy and cost [14].    
Author
Author
Author Profile
Satyendra Maurya LinkedIn Research Analyst
An accomplished research analyst with high proficiency in market forecasting, data visualization, competitive benchmarking, and others. He holds a pronounced track record in research and consulting projects for sectors such as life sciences, medical devices, and healthcare IT. His capabilities in qualitative and quantitative analysis have resulted in positive client outcomes. Working on niche market trends, opportunities, sales, and forecasted value is part of his skill set.
Co-Author
Co-Author Profile
Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















