Europe Warehouse Robotics Market (2025 - 2035)

Europe Warehouse Robotics Market Size, Share and Research Report By Type (Industrial Robots, Sortation Systems, Conveyors, Palletizers, Mobile Robots, Other Types), By Function (Storage, Packaging, Trans-Shipments, Other Functions), By End-user Application (Food and Beverage, Automotive, Retail and E-Commerce, Electrical and Electronics, Pharmaceuticals, Other End-user Applications), By Component (Hardware, Software, Services) and By Country (Germany, United Kingdom, France, Netherlands, Italy, Spain, Nordic Countries, Rest of Europe) - Industry Forecast to 2035.
ID: MRFR/SEM/11007-HCR 128 Pages Ankit Gupta, Shubham Munde Last Updated: September 15, 2026
Europe Warehouse Robotics Market
Market Size
Forecast Period2025-2035
CAGR (2025-2035)16.6%
2025 Market SizeUSD 3.15 Billion
2026 Market SizeUSD 3.67 Billion
2035 Market SizeUSD 14.63 Billion
Key Players
KION Group
Vanderlande
SSI Schäfer
Daifuku
Swisslog
Knapp AG
Opportunities
  • Urban Micro-Fulfilment in Dense City Cores
  • Subscription and Usage-Based Business Models
  • Cold-Chain and Pharmaceutical Automation

Europe Warehouse Robotics Market Summary

The Europe Warehouse Robotics Market was valued at USD 3.15 billion in 2025 and is projected to reach USD 3.67 billion in 2026 before climbing to USD 14.63 billion by 2035, expanding at a 16.6% CAGR across the forecast window. Two catalysts anchor that trajectory. The EU Energy Efficiency Directive recast (EU/2023/1791) obliges large logistics operators to run periodic energy audits and act on cost-effective findings, which pushes fixed conveyor estates toward lower-draw electric alternatives [1]. Alongside it, the EUR 43 billion Connecting Europe Facility allocation for transport corridors through 2027 is financing the distribution nodes that automation vendors sell into [2].

Legacy intralogistics estates are being displaced rather than upgraded. Fixed roller conveyors, static rack-and-pick aisles, and PLC-bound sorters — assets with ten-to-fifteen-year depreciation schedules — are giving way to goods-to-person cube storage, self-navigating fleets, and orchestration software that reallocates tasks in real time. Deployment economics explain the shift: a modular fleet reaches productive throughput in eight to twelve weeks against twelve to eighteen months for a fixed sorter, and European venture funding into intralogistics robotics exceeded USD 1.9 billion between 2023 and 2025 [3].

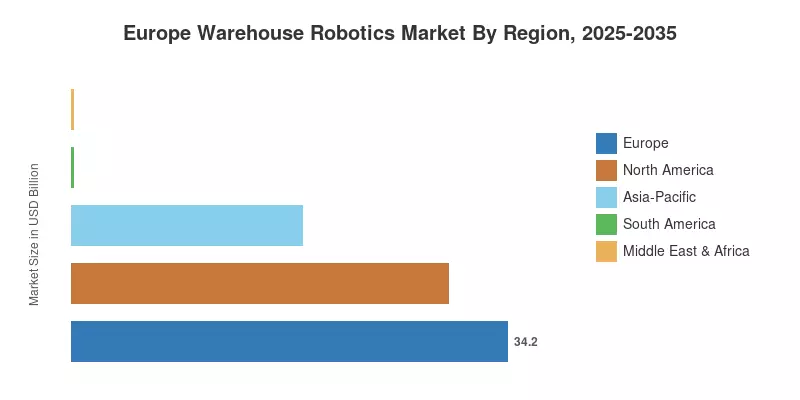
Regionally, Europe holds 34.2% of the global installed opportunity in 2025, supported by dense parcel networks and the highest warehouse labour costs outside North America. Asia-Pacific is the fastest-growing comparator at 18.1% CAGR, while North America ranks second at 29.6% share on the strength of hyperscale fulfilment capex. Through 2035, competitive advantage in the Europe Warehouse Robotics Market will migrate from mechanical throughput toward software that governs heterogeneous fleets.

Key Report Takeaways

The bullets below summarise where value concentrates and where it is compounding fastest across the Europe Warehouse Robotics Market.

• By Type

  • Mobile Robots held a 36.7% share of the Europe Warehouse Robotics Market in 2025, the largest single type position.
  • Sortation Systems recorded USD 0.67 billion in 2025 revenue, concentrated in parcel hubs clearing above 50,000 units per day.
  • Palletizers are expanding at a 14.2% CAGR as robotic case erectors replace manual end-of-line stations.

• By Function

  • Storage commanded a 49.5% share in 2025, reflecting the installed base of automated storage and retrieval estates.
  • Trans-Shipments post the fastest functional growth at 17.6% CAGR to 2035.
  • Packaging generated USD 0.72 billion in 2025, led by German and Dutch fast-moving consumer goods sites.

• By End-user Application

  • Retail and E-Commerce captured a 41.2% share of the Europe Warehouse Robotics Market in 2025.
  • Pharmaceuticals is the fastest-scaling vertical at 18.4% CAGR, driven by temperature-integrity and traceability mandates.
  • Automotive applications reached USD 0.46 billion in 2025 through line-side replenishment deployments.

• By Component

  • Hardware accounted for 66.6% of 2025 spending across the Europe Warehouse Robotics Market.
  • Software revenues are compounding at 18.1% CAGR as orchestration layers become the control point.
  • Services delivered USD 0.49 billion in 2025, with margin compression from bundled subscription contracts.

• By Country

  • Germany led with 33.8% share of the 2025 base.
  • Spain records the quickest national growth at 17.7% CAGR.
  • The Netherlands contributed USD 0.27 billion in 2025 from its port-linked distribution cluster.

• By Region

  • Europe holds 34.2% of the global opportunity in 2025.
  • Asia-Pacific grows fastest at 18.1% CAGR through 2035.
  • Middle East & Africa reached USD 0.12 billion in 2025 on Gulf logistics-city programmes.


Market Size and Forecast (2021–2035)

Estimates combine bottom-up vendor revenue reconciliation, installed-base modelling of European distribution centres above 10,000 square metres, and top-down validation against Eurostat warehousing gross value added and national robotics association shipment data. Historical years are anchored to audited vendor filings and customs-level import records for industrial robot units. Forecast years apply demand elasticity to parcel volume growth published by national postal regulators, adjusted for capex deferral risk observed during the 2023–2024 interest rate cycle. Every figure below is expressed in USD Billion at constant 2025 exchange rates.
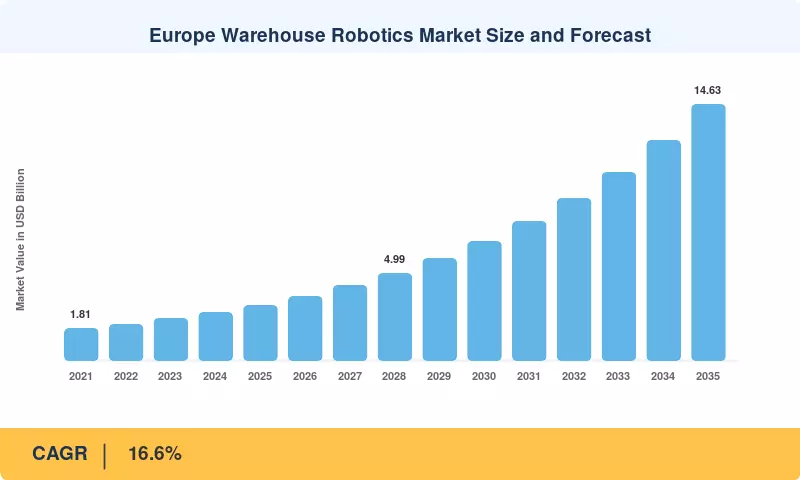
Europe Warehouse Robotics Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
E-commerce order volume and same-day delivery pressure 3.4 Germany, UK, France Short-term (≤2 yr)
Structural warehouse labour shortage and wage inflation 3.1 Pan-Europe Short-term (≤2 yr)
Robots-as-a-Service and OPEX-based procurement 2.4 UK, Netherlands, Spain Medium-term (2–4 yr)
AI-driven fleet orchestration and vision picking 2.8 Pan-Europe Long-term (≥4 yr)
EU energy efficiency and industrial decarbonisation policy 2.2 EU-27 Medium-term (2–4 yr)
VDA 5050 interoperability standardisation 1.9 Germany, Nordic Countries Medium-term (2–4 yr)
Nearshoring and regional distribution network rebuild 1.6 Iberia, Central and Eastern Europe Long-term (≥4 yr)


E-Commerce Order Volume and Same-Day Delivery Pressure

The same-day and next-day tiers absorbed the majority of the incremental expansion, with European package volumes reaching 16.4 billion items in 2024, a 9.1% increase over the previous year [9]. When pick-to-dispatch windows are compressed below ninety minutes in order to meet certain cut-offs, manual picking is unable to maintain optimal performance. As a result, operators prioritize funding goods-to-person cells, where throughput per square meter increases three to four times. Service-level penalties of 2-4% of order value are now frequently included in retail contracts, strengthening the business rationale.


Structural Warehouse Labour Shortage and Wage Inflation

German logistics wages exceeded EUR 18.40 per hour in 2024, while vacancy rates in European transport and storage jobs were 3.2%, nearly twice as high as in 2015 [15]. During peak season, agency premiums increase by an additional 30 to 45%. In high-wage markets, automation payback models that formerly assumed six-year horizons now clear internal hurdle rates in less than 36 months. Board-level approval is now mostly triggered by labor scarcity rather than throughput goals.


Robots-as-a-Service and OPEX-Based Procurement

Subscription contracts shifted roughly 22% of European mobile robot deployments off the balance sheet in 2025, converting seven-figure capital requests into monthly per-unit fees typically ranging from EUR 1,600 to EUR 2,900 [7]. That structure opens the buyer pool to third-party logistics providers operating on short customer contracts, who previously could not underwrite fixed assets against two-year commitments. Vendors accept lower first-year revenue in exchange for recurring margin and fleet telemetry rights.

AI-Driven Fleet Orchestration and Vision Picking

Orchestration platforms applying reinforcement learning to path planning and task allocation have demonstrated 12–19% throughput gains on unchanged hardware in benchmarked European sites [12]. Vision-guided picking has independently pushed mixed-SKU grasp success above 96% for non-deformable items. Software therefore delivers capacity without additional capital, which is why orchestration attach rates rise faster than unit shipments and why enterprise software vendors are embedding robotics control natively into warehouse management suites.

EU Energy Efficiency and Industrial Decarbonisation Policy

Under the recast Energy Efficiency Directive, enterprises consuming more than 85 TJ annually must implement energy management systems, with audits mandatory above 10 TJ [1]. Continuously running conveyor loops are among the most visible remediation targets, drawing power irrespective of order flow. Battery-electric mobile fleets consume energy proportionally to demand, cutting intralogistics electricity draw by 25–40% in documented conversions and turning compliance spending into a throughput upgrade.

VDA 5050 Interoperability Standardisation

Adoption of the VDA 5050 communication interface allows fleets from different suppliers to run under a single master control layer, removing the vendor lock-in that stalled multi-phase rollouts [8]. Sites can now add capacity from a second supplier without replacing the control stack, shortening procurement cycles by an estimated four to six months. German and Nordic operators lead adoption, and standardisation is measurably increasing the software share of total contract value.

Nearshoring and Regional Distribution Network Rebuild

Reshoring announcements covering European manufacturing added an estimated 41 million square metres of planned warehouse capacity between 2023 and 2025, weighted toward Iberia, Poland, Czechia, and Romania [13]. Greenfield sites carry no legacy conveyor sunk cost, so automation is designed in from day one at penetration rates roughly double brownfield retrofits. Lower construction costs in these markets also free budget for equipment within fixed project envelopes.

Restraints Impact Analysis

Restraint impacts are directional drag estimates derived from deal-slippage tracking and procurement interviews. They quantify relative friction rather than a subtractable percentage, and they are already embedded in the net forecast for the Europe Warehouse Robotics Market rather than applied on top of it.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High upfront capital intensity and long payback −2.3 Italy, Central and Eastern Europe Short-term (≤2 yr)
Shortage of robotics integration and maintenance technicians −1.8 Pan-Europe Medium-term (2–4 yr)
Legacy WMS and ERP integration complexity −1.5 Germany, France Short-term (≤2 yr)
Machinery Regulation and CE safety certification burden −1.2 EU-27 Medium-term (2–4 yr)
Component supply chain and battery lead times −1.0 Pan-Europe Short-term (≤2 yr)


High Upfront Capital Intensity and Long Payback

Before integration, large sortation installations cost more than EUR 5 million, and lead times are close to a year [5]. In the face of three-year customer contracts, mid-sized Italian and Central European operators with single-digit EBITDA margins are unable to absorb that expenditure. Deal slippage of two to three quarters persisted until 2025, and financing costs exacerbated the issue when euro-area policy rates remained at 3.5%.


Shortage of Robotics Integration and Maintenance Technicians

In comparison to the anticipated 2028 need, Europe is expected to lack 148,000 qualified automation maintenance technicians [16]. Same-shift intervention is necessary for fleet uptime, and facilities lacking resident competence report availability that is three to five percentage points below contracted service requirements. Although vendor training academies are growing, rollout velocity is more constrained by the nine- to twelve-month certification schedule than by equipment supply.


Legacy WMS and ERP Integration Complexity

Roughly 44% of European distribution centres still run warehouse management systems more than a decade old, many with customised code that resists real-time task exchange [12]. Middleware development to bridge those systems typically adds EUR 250,000 to EUR 800,000 and four months to project timelines. Integration risk, not robot performance, is the most frequently cited reason pilots fail to convert into multi-site programmes.

Machinery Regulation and CE Safety Certification Burden

Regulation (EU) 2023/1230 applies from January 2027 and introduces obligations for machinery with self-evolving behaviour, including documentation of autonomous decision logic [17]. Suppliers must re-certify existing platforms and revalidate human-robot collaborative zones. Compliance work is estimated to add 4–7% to product development budgets and is delaying some product launches into the second half of the decade.

Component Supply Chain and Battery Lead Times

Lithium iron phosphate cell allocation and industrial-grade lidar remain the binding constraints on European fleet assembly, with quoted lead times of eighteen to twenty-six weeks during 2024–2025 peaks [11]. Suppliers dependent on single-source sensor vendors have deferred deliveries by a quarter or more. Dual-sourcing programmes are progressing, but qualification of alternate sensor stacks requires full re-validation of navigation safety cases.

Europe Warehouse Robotics Market Opportunities

Opportunity is concentrating where physical constraints, regulatory deadlines, and unmet geographic demand intersect within the Europe Warehouse Robotics Market.

Urban Micro-Fulfilment in Dense City Cores

Vertical density is the only practical route to sub-two-hour delivery from inside the ring road due to European city center rentals of EUR 180–320 per square meter per year [9]. 1,500 square meter units are transformed into functional fulfillment nodes by cube-storage systems that achieve four times the SKU density of shelving. The first adopters are grocery and pharmacy companies in Paris, Milan, and Amsterdam. With reproducible engineering, each node represents an equipment opportunity worth EUR 1.2–2.5 million.


Subscription and Usage-Based Business Models

The peak-capacity conundrum that discourages fixed-asset acquisitions is eliminated by converting equipment sales into per-pick or per-unit-hour pricing, which synchronizes vendor revenue with customer seasonality [7]. Recurring margin is two to three times the gross profit on hardware sales for providers who may redeploy fleets across clients and underwrite residual value. Through asset-backed vehicles, financial partners are joining the market, which will significantly increase the number of addressable buyers.


Cold-Chain and Pharmaceutical Automation

EU Good Distribution Practice guidelines require continuous temperature monitoring and full batch traceability, obligations that manual handling satisfies only at high labour cost [10]. Automated systems operating in 2–8 °C zones deliver documented accuracy above 99.9% while reducing worker exposure to cold environments. Pharmaceutical distribution therefore supports premium pricing and the highest vertical growth rate in the forecast.

Iberia and Central Eastern Europe Capacity Gap

Automation penetration in Poland, Czechia, Romania, Spain, and Portugal sits at roughly 40% of German levels, despite these markets absorbing a disproportionate share of new construction [13]. Rising local wages are closing the arbitrage that historically justified manual operations. Vendors establishing regional service footprints ahead of demand will capture the fastest national growth rates in the Europe Warehouse Robotics Market over the coming decade.

Fleet Telemetry Data Monetisation

Every deployed unit generates continuous data on path efficiency, battery degradation, congestion points, and pick accuracy. Aggregated across a vendor's installed base, that telemetry supports predictive maintenance products, benchmarking subscriptions, and layout consultancy priced independently of hardware [12]. Early providers report attach rates near 30% on analytics modules, and the data asset compounds in value as fleets scale, creating durable switching costs.

Europe Warehouse Robotics Market Future Outlook

Embodied AI and Autonomous Decision Layers

Learned control policies are replacing rule-based navigation and grasp planning, allowing fleets to handle SKU mixes that previously required human intervention. Benchmarks show mixed-item grasp reliability improving roughly eight percentage points annually since 2022, and full parity with human picking on deformable goods is plausible before 2032 [14]. The consequence is economic rather than technical: once exception handling falls below 2% of picks, resident staffing requirements drop sharply, and the addressable task envelope widens across the Europe Warehouse Robotics Market.

Platform Economics and Orchestration Margins

Control software is becoming the durable competitive moat as hardware differentiation narrows. Vendors bundling orchestration, analytics, and simulation report gross margins near 70% against 28–35% on mechanical equipment, and enterprise software incumbents are embedding robotics control directly into supply-chain suites [12]. Expect consolidation in which mechanical specialists acquire software capability or accept commoditisation, with contract value shifting steadily toward recurring licences through 2035.

Energy Efficiency and Fleet Electrification

Industrial electricity consumption in EU logistics facilities is projected to fall roughly 18% per unit of throughput by 2035 as demand-proportional equipment displaces continuously running conveyance [19]. Battery chemistry improvements and opportunity charging are removing the duty-cycle penalty that once favoured fixed systems. Energy performance is now appearing explicitly in tender scoring, which advantages suppliers publishing verified kilowatt-hour-per-pick metrics.

CSRD Reporting and Workforce Transition

The Corporate Sustainability Reporting Directive requires disclosure on workforce composition, health and safety incidents, and energy intensity, all of which automation directly affects [20]. Musculoskeletal injury reductions of 30–50% in automated zones translate into reportable improvements and lower insurance loading. Operators will increasingly justify projects on combined financial and disclosure grounds, while reskilling obligations create parallel demand for maintenance technician training programmes.

Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
Europe 34.2% share Labour substitution, energy compliance, multi-vendor orchestration
North America 29.6% share Hyperscale fulfilment capex, parcel sortation replacement
Asia-Pacific 18.1% CAGR (2026–2035) Domestic e-commerce scale, low-cost robot manufacturing
South America USD 0.16 Billion Cold-chain modernisation, agricultural export logistics
Middle East & Africa USD 0.12 Billion Logistics-city megaprojects, transit hub automation
Total 100.0% —

The table positions the Europe Warehouse Robotics Market against comparator regions of the wider global opportunity, using one disclosed metric per row.


North America

Country Share of Region (2025) Key Driver
US 74.1% Hyperscale retailer fulfilment network expansion
Canada 14.2% Cross-border parcel consolidation hubs
Mexico 11.7% Nearshoring-driven manufacturing logistics build-out


North American demand remains anchored to a small number of very large buyers whose annual automation budgets exceed those of entire European national markets. Federal advanced manufacturing tax provisions and state-level capital allowances shorten payback further, encouraging replacement of first-generation sortation assets installed in the late 2010s. Mexican volumes are rising quickly as manufacturers relocate capacity, though installations skew toward conveyance and palletising rather than autonomous fleets.

Europe

Country CAGR (2026–2035) Key Driver
Germany 15.8% High labour cost base and standards leadership
UK 16.9% Grocery e-commerce penetration above 11%
France 16.2% Retailer cross-dock conversion programmes
Italy 15.4% Fashion and third-party logistics modernisation
Spain 17.7% New distribution capacity with greenfield economics
Nordic Countries 16.5% Energy cost sensitivity and early technology adoption
Russia 11.2% Constrained equipment access under export controls
Rest of Europe 17.0% Central and Eastern European capacity additions


Germany anchors the Europe Warehouse Robotics Market through a combination of the region's highest logistics wage base, a dense automotive supply network requiring line-side replenishment, and its role in authoring the interoperability standards other markets adopt [8]. British demand is disproportionately grocery-led, with online penetration sustaining automated picking investment through consumer softness. Spain and the Central European economies grow fastest because new construction avoids retrofit penalties, while Russian demand has decoupled from the regional trend under equipment export restrictions.

Asia-Pacific

Country CAGR (2026–2035) Key Driver
China 19.4% Domestic robot manufacturing scale and price competition
India 21.2% National warehousing formalisation and grade-A capacity
Japan 15.1% Acute demographic labour contraction
South Korea 17.8% Dense urban same-day delivery networks
ASEAN 19.9% Cross-border e-commerce platform expansion
Rest of Asia-Pacific 16.7% Port-adjacent distribution modernisation


Asia-Pacific outpaces every other region because domestic manufacturing has driven mobile robot unit prices roughly 30–40% below European equivalents, expanding the set of economically viable use cases. Indian growth reflects a structural shift from fragmented godowns to institutional-grade facilities following goods and services tax harmonisation. Japanese demand is demographically compelled rather than volume-driven, with the working-age population contracting steadily through the forecast period [18].

South America

Country Share of Region (2025) Key Driver
Brazil 54.6% Retail e-commerce growth in São Paulo corridor
Argentina 18.3% Agricultural export handling automation
Rest of South America 27.1% Chilean and Colombian retail distribution upgrades


South American adoption concentrates in a handful of metropolitan distribution corridors where order density justifies fixed investment. Currency volatility complicates dollar-denominated equipment procurement, pushing buyers toward leasing structures and locally assembled conveyance. Cold-chain applications serving food export markets show the strongest near-term economics, since spoilage reduction produces measurable returns independent of labour arbitrage.

Middle East & Africa

Country Share of Region (2025) Key Driver
Saudi Arabia 31.2% National logistics strategy and transit hub ambitions
UAE 27.5% Re-export distribution and free-zone fulfilment
South Africa 18.4% Retail chain distribution centre consolidation
Egypt 10.6% Suez-adjacent industrial zone development
Rest of MEA 12.3% Selective grocery and pharmaceutical projects


Gulf demand is policy-manufactured, with sovereign logistics programmes specifying automation levels in tender documents rather than leaving them to operator discretion. Projects consequently skew large and technologically ambitious, often incorporating fully automated storage from commissioning. Sub-Saharan adoption remains limited by power reliability and service network depth, though South African grocery chains have begun deploying palletising and case-handling systems at consolidated regional centres.

Europe Warehouse Robotics Market By Region, 2025-2035

Europe Warehouse Robotics Market Segmentation

Segment metrics below follow the report taxonomy, with a single disclosed metric per row across the Europe Warehouse Robotics Market.

By Type

Segment Share (2025) Primary Demand Driver
Mobile Robots 36.7% Reconfigurable capacity matching volatile order profiles
Sortation Systems 21.4% Parcel hubs exceeding 50,000 units per day
Industrial Robots 19.8% Mixed-SKU handling and intralogistics cobot deployment
Conveyors 12.6% Legacy installed base and high-volume fixed flows
Palletizers 6.9% End-of-line labour substitution in beverages and consumer goods
Other Types 2.6% Vertical lift modules and specialised handling equipment


Mobile Robots lead the Europe Warehouse Robotics Market on 36.7% share and also grow fastest at 17.3% CAGR, because installation measured in weeks lets operators match capacity to seasonal peaks without permanent structural commitment. Sortation Systems retain a strong second position where parcel density justifies seven-figure fixed assets, but multi-year lead times confine them to mega-sites. Industrial Robots are migrating from production halls into picking zones as collaborative models reach commercially relevant pick rates.

By Function

Segment Share (2025) Primary Demand Driver
Storage 49.5% Installed automated storage and retrieval base
Packaging 22.8% Robotic case erection payback under three years
Trans-Shipments 19.1% Cross-dock flows targeting sub-24-hour inventory clearance
Other Functions 8.6% Returns processing, kitting, and value-added services


Storage dominates the Europe Warehouse Robotics Market on 49.5% share, reflecting a decade of investment in density-optimised retrieval systems. Trans-Shipments grow fastest at 17.6% CAGR as retailers eliminate static holding areas entirely, with documented facility footprint reductions approaching 40% on converted sites. Packaging automation is advancing quickest in high-wage markets, while returns and kitting remain labour-intensive pending broader vision-guided handling maturity.

By End-user Application

Segment Share (2025) Primary Demand Driver
Retail and E-Commerce 41.2% Same-day delivery commitments and order volume growth
Food and Beverage 17.3% Multi-temperature handling and modular micro-fulfilment
Automotive 14.6% Line-side replenishment and work-in-process reduction
Electrical and Electronics 11.9% Vertical lift systems maximising constrained floor space
Pharmaceuticals 9.4% Temperature integrity and batch traceability obligations
Other End-user Applications 5.6% Apparel, industrial distribution, and third-party logistics


Retail and E-Commerce anchors the Europe Warehouse Robotics Market with 41.2% share, sustained by fleet-scale deployments that only automated operations can support economically. Pharmaceuticals grow fastest at 18.4% CAGR despite smaller absolute spend, because regulated cold-chain accuracy requirements justify deeper automation per facility. Automotive buyers focus narrowly on inventory reduction, reporting work-in-process cuts near 30%, while Food and Beverage contends with multi-temperature complexity favouring modular architectures.

By Component

Segment Share (2025) Primary Demand Driver
Hardware 66.6% Robot units, sorters, racking, and sensing systems
Software 17.9% Fleet orchestration, path planning, predictive maintenance
Services 15.5% Integration, commissioning, and maintenance contracts


Hardware retains 66.6% of Europe Warehouse Robotics Market spending, though its share erodes annually as control layers absorb value. Software expands fastest at 18.1% CAGR, because orchestration determines realised throughput from any given fleet and increasingly governs equipment from multiple suppliers under one interface. Services revenue grows in absolute terms while facing margin compression, as subscription contracts fold maintenance into monthly fees rather than billing it separately.

By Country

Segment CAGR (2026–2035) Primary Demand Driver
Germany 15.8% Highest regional labour costs and standards leadership
United Kingdom 16.9% Grocery e-commerce and dark store fulfilment
France 16.2% Retailer cross-dock conversion at national scale
Netherlands 17.1% Port-linked European distribution centre cluster
Italy 15.4% Fashion and third-party logistics modernisation
Spain 17.7% Greenfield capacity with automation designed in
Nordic Countries 16.5% Energy cost sensitivity and early adoption culture
Rest of Europe 17.3% Central and Eastern European distribution build-out


Germany holds 33.8% share of the Europe Warehouse Robotics Market, a position built on wage economics and its role in defining fleet interoperability standards. Spain records the fastest national growth at 17.7% CAGR, since new-build facilities carry no retrofit penalty and local wage inflation has closed the historic manual-labour advantage. Dutch demand punches above the country's size through port-adjacent European distribution centres serving multiple national markets from single automated sites.

Competitive Benchmarking

Concentration is moderate. The top five suppliers control an estimated 40–46% of regional revenue, and the calculated Herfindahl-Hirschman Index sits between 620 and 740 — comfortably below thresholds indicating dominance. Legacy integrators retain scale advantages in fixed systems and long-cycle projects, while venture-backed mobile robot specialists have taken share rapidly in the modular segment, where switching costs are lower and sales cycles shorter. Interoperability standards are further eroding incumbency by allowing operators to blend suppliers within a single site, so competitive intensity across the Europe Warehouse Robotics Market is rising rather than consolidating.

Company Est. Revenue Share Range Key Offerings for Europe Warehouse Robotics Market Strategic Positioning
KION Group (Dematic) ~11–14% Automated storage, sortation, mobile fleets, control software Broadest European portfolio; scale integrator with financing depth
Vanderlande ~8–11% Parcel sortation, airport and warehouse handling systems Parcel and airport specialist backed by Toyota Industries
SSI Schäfer ~7–10% Storage systems, shuttles, software, racking Family-owned full-service provider with strong DACH base
Daifuku ~6–9% Automated storage and retrieval, conveyance, controls Japanese incumbent expanding European service footprint
Swisslog (KUKA) ~5–8% Cube storage, healthcare automation, robotics integration Differentiated in pharmaceutical and hospital logistics
Knapp AG ~5–7% Shuttle systems, pocket sorters, pick-to-light, software Austrian specialist strong in fashion and healthcare
AutoStore ~4–7% Cube storage grids, port systems, controller software Density-led architecture with wide partner integrator network
BEUMER Group ~4–6% High-speed sorters, palletising, conveying Engineering-led supplier for very high throughput sites
Exotec ~3–5% Three-dimensional mobile storage robots, orchestration Fast-scaling French challenger with retail anchor accounts
TGW Logistics ~3–5% Shuttle storage, picking systems, integration services Austrian integrator focused on fashion and grocery
ABB ~3–5% Industrial and collaborative robots, controls, training Component and cobot supplier with regional service scale
Geek+ ~2–4% Mobile fleets, goods-to-person systems, fleet software Volume mobile robot supplier competing on deployment speed


Recent News & Developments

  • KION Group (March 2024): Announced an expanded partnership to integrate third-party mobile fleets under its control software, signalling that incumbents now compete on orchestration rather than exclusive hardware supply.
  • European Commission (June 2023): Adopted the recast Energy Efficiency Directive, introducing mandatory energy management systems for large consumers and placing continuously running conveyance under compliance scrutiny [1].
  • Exotec (September 2024): Opened an expanded European manufacturing and service facility to shorten deployment lead times, addressing the installation-speed criterion that increasingly decides mid-market tenders [3].
  • AutoStore (February 2025): Launched a higher-throughput port system targeting pharmaceutical and healthcare distribution, extending cube storage into temperature-controlled applications [10].
  • ABB (November 2023): Commissioned a Madrid training centre committed to certifying approximately 500 technicians annually, directly addressing the maintenance skills shortage constraining fleet uptime [16].
  • Vanderlande (May 2025): Secured a multi-site parcel sortation programme with a pan-European carrier, replacing first-generation sorters approaching the end of depreciable life [11].
  • VDA (January 2024): Published an updated 5050 interface specification broadening supported vehicle classes, accelerating multi-vendor fleet deployments across German and Nordic sites [8].
  • Swisslog (August 2025): Completed a large automated bin-storage installation for a national health service supply network, demonstrating regulated cold-chain accuracy at scale [10].

Europe Warehouse Robotics Market Report Scope

Parameter Detail
Market Scope Europe Warehouse Robotics Market, covering robotic and automated handling equipment, control software, and associated services deployed in warehousing and distribution facilities
Study Period 2021–2035
Historical Period 2021–2024
Base Year 2025
Forecast Period 2026–2035
CAGR (2026–2035) 16.6%
Market Size (2025) USD 3.15 Billion
Market Size (2026) USD 3.67 Billion
Market Size (2035) USD 14.63 Billion
Segmentation Covered By Type; By Function; By End-user Application; By Component; By Country
Fastest Growing Segments Mobile Robots (Type); Trans-Shipments (Function); Pharmaceuticals (End-user Application); Software (Component); Spain (Country)
Companies Profiled KION Group (Dematic), Vanderlande, SSI Schäfer, Daifuku, Swisslog (KUKA), Knapp AG, AutoStore, BEUMER Group, Exotec, TGW Logistics, ABB, Geek+
Valuation Currency USD Billion, constant 2025 exchange rates

FAQs

What procurement structure should a mid-sized operator use to enter the European Warehouse Robotics Market?
Subscription contracts suit operators with customer agreements shorter than five years, since they avoid residual-value risk. Outright purchase remains cheaper over a ten-year horizon where volumes are predictable [7].
How should buyers evaluate vendor lock-in before signing?
Require VDA 5050 conformance and a documented API for task assignment in the tender. Without both, adding a second supplier later typically means replacing the control layer entirely [8].
What integration mistakes most often derail Europe Warehouse Robotics Market projects?
Underestimating middleware work between legacy warehouse management systems and fleet controllers. Budget four months and up to EUR 800,000 for bridging older estates [12].
Do collaborative robots or dedicated mobile fleets deliver better returns in mixed-SKU zones?
Collaborative arms win where picking is stationary, and item geometry varies. Mobile fleets win where travel distance dominates cycle time, which describes most European distribution floors [14].
What upcoming regulation should Europe Warehouse Robotics Market buyers plan for?
Regulation (EU) 2023/1230 applies from January 2027 and covers machinery with self-evolving behaviour. Confirm suppliers have a re-certification roadmap before committing to multi-year rollouts [17].
How do maintenance staffing requirements change after deployment?
Sites typically need one certified technician per twenty-five to forty units on shift. Certification takes nine to twelve months, so recruitment must begin well before commissioning [16].
Which emerging use case is least understood by Europe Warehouse Robotics Market buyers?
Returns processing. Vision-guided handling is approaching viability for non-deformable items, and early adopters are securing capacity ahead of the 2028 cost inflection [14].
Author
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.
Co-Author Co-Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















