Europe Sustainable Packaging Market (2026 - 2035)

Europe Sustainable Packaging Market Research Report Information By Material (Paper and Board (Cartonboard, Molded Fibre, and More), Plastic (PE, PP, PET, and More), Glass, and Metal (Cans, Caps and Closures, Tubes, and More)), By Packaging Format (Rigid, Flexible, and Semi-Rigid), and By End-User Industry (Food, Beverage, Pharmaceutical and Healthcare, Personal Care and Cosmetics, Household Care, and Other End-User Industries) – Forecast Till 2035
ID: MRFR/PCM/11157-HCR 111 Pages Snehal Singh Last Updated: August 24, 2026
Europe Sustainable Packaging Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.35%
2025 Market SizeUSD 163.41 Billion
2035 Market SizeUSD 249.39 Billion
Key Players
Amcor plc
Smurfit Westrock
Tetra Pak
Mondi plc
Ardagh Group
Ball Corporation
Opportunities
  • Reusable Transit Systems for Grocery Retail
  • CEE Conversion Capacity as an Emerging Play
  • Return Infrastructure Monetisation

Europe Sustainable Packaging Market Summary

The Europe Sustainable Packaging Market was valued at USD 163.41 Billion in 2025 and is projected to open the forecast window at USD 170.00 Billion in 2026 before reaching USD 249.39 Billion by 2035, expanding at a 4.35% CAGR. Two catalysts anchor that trajectory. The EU Packaging and Packaging Waste Regulation (PPWR) sets binding recyclability and reuse thresholds that bite from 2030, and converters across the bloc have already committed capital ahead of the deadline [1]. Retailer-side reformulation pledges do the rest, pulling demand forward into the European Sustainable Packaging Market well before compliance dates arrive.

Substitution, not volume growth, is doing the heavy lifting. Multi-layer laminates and unrecyclable rigid formats are giving way to fiber-based trays, single-polymer PET structures, and lightweighted aluminium — a shift the European Commission's circular economy programming has backed with more than EUR 10 billion in Horizon Europe and Innovation Fund allocations touching materials and process decarbonisation [2]. Digital printing shortens design-to-shelf cycles, letting brand owners test formats without committing to long plate runs.

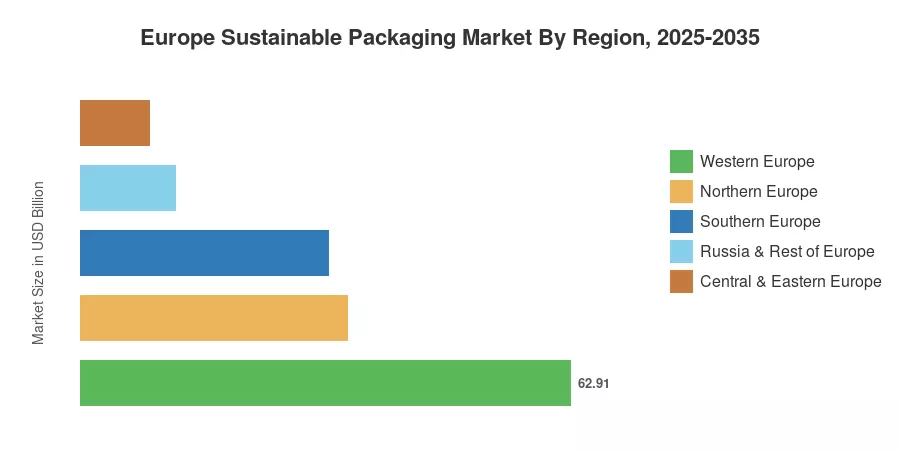
Regionally, Western Europe holds 38.5% of the Europe Sustainable Packaging Market, carried by Germany's converter density and France's anti-waste law. Central & Eastern Europe grows fastest at a 5.4% CAGR as Polish and Romanian capacity absorbs Western fill-and-pack outsourcing. Northern Europe ranks second at USD 34.32 billion, where deposit infrastructure keeps high-grade recyclate circulating. The next decade rewards whoever controls feedstock quality.


Key Report Takeaways

• By Material

  • Paper and board held 37.7% of the Europe Sustainable Packaging Market in 2025, the single largest material position
  • Plastic accounted for USD 55.89 billion in 2025, concentrated in mono-PET and PP recyclate streams
  • Glass is advancing at a 3.6% CAGR, the slowest of the four material families

• By Packaging Format

  • Rigid formats are forecast to grow at a 6.0% CAGR between 2026 and 2035, the fastest format in the Europe Sustainable Packaging Market
  • Flexible formats generated USD 67.82 billion in 2025
  • Semi-rigid formats represented 14.5% of 2025 revenue

• By Region

  • Western Europe commanded a 38.5% share in 2025
  • Central & Eastern Europe posts a 5.4% CAGR through 2035
  • Poland alone is tracking a 5.51% CAGR, the strongest single-country rate in the Europe Sustainable Packaging Market


Market Size and Forecast (2021–2035)

Figures below blend converter-level shipment data, Eurostat packaging waste reporting, listed-company segment disclosures, and primary interviews with brand-owner packaging leads across nine countries. Historical values are reconciled against national producer-responsibility filings; forecast values for the Europe Sustainable Packaging Market apply a bottom-up material-substitution model layered onto end-user consumption baselines.
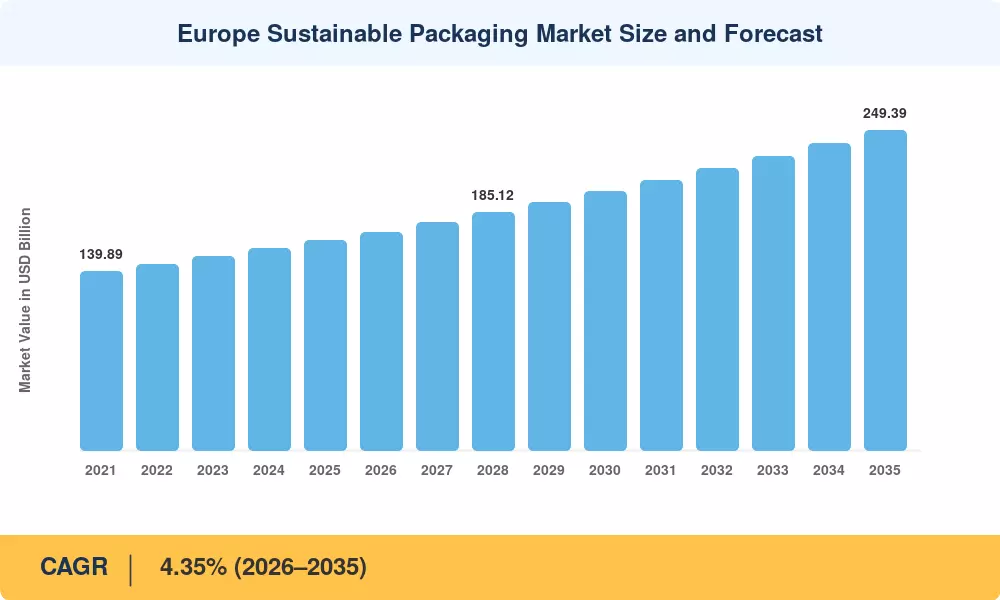
Europe Sustainable Packaging Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
PPWR compliance cycle ~1.05 pp EU-27 Medium-term (2–4 yr)
Brand-owner closed-loop commitments ~0.80 pp Western & Northern Europe Medium-term (2–4 yr)
E-commerce fulfilment growth ~0.65 pp Pan-Europe Short-term (≤2 yr)
Fiber substitution economics ~0.55 pp Nordics, Germany, Poland Long-term (≥4 yr)
Deposit-return infrastructure rollout ~0.45 pp Germany, Nordics, CEE Medium-term (2–4 yr)
Digital printing and SKU fragmentation ~0.30 pp Western Europe Short-term (≤2 yr)
Pharmaceutical barrier upgrades ~0.25 pp Switzerland, Ireland, Germany Long-term (≥4 yr)


Regulatory Compliance as a Capital Trigger

PPWR obliges every packaging unit placed on the EU market to be recyclable by 2030 under design-for-recycling criteria, with reuse targets rising to 40% for transport packaging by 2030 [1]. That converts a voluntary sustainability agenda into a balance-sheet item. Converters serving multinational FMCG accounts report requalification of roughly 60% of their active SKU portfolios, and the European Environment Agency documents packaging waste generation at 190 kg per capita annually — the number regulators are explicitly targeting [8].

Feedstock Economics and Recyclate Contracting

Brand owners have discovered that securing recycled content is now a procurement discipline rather than a marketing exercise. Food-grade rPET traded at a persistent premium to virgin resin through 2024 and 2025, with Plastics Europe reporting European mechanical recycling capacity utilisation above 80% and structurally short of demand [10]. Long-term offtake agreements — five to seven years, volume-firm, quality-indexed — have become standard, and converters without them face margin exposure they cannot hedge.

E-Commerce and Format Rationalisation

Online grocery and general merchandise fulfilment reshaped secondary packaging demand faster than any regulation. Eurostat records e-commerce penetration above 70% of internet users in the EU, with parcel volumes concentrating in Germany, France, and the UK [7]. Right-sizing algorithms cut corrugated consumption per shipment while raising unit counts, producing a net-positive but format-shifted demand signal that favours fiber converters with variable-dimension capability.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Energy price volatility for converters ~-0.70 pp Germany, Italy, CEE Short-term (≤2 yr)
Recyclate supply shortfall and premium ~-0.55 pp EU-27 Medium-term (2–4 yr)
Fragmented national producer-responsibility fees ~-0.40 pp Pan-Europe Medium-term (2–4 yr)
Capital intensity of line conversion ~-0.35 pp Southern Europe, CEE Long-term (≥4 yr)
Food-contact approval lag for novel materials ~-0.25 pp EU-27 Long-term (≥4 yr)


Energy Exposure in Glass and Board

Melting furnaces and paper machines sit at the wrong end of Europe's energy cost curve. Industrial electricity prices in the EU averaged roughly EUR 0.19 per kWh for medium-sized consumers in 2024, materially above US benchmarks [6]. Glass producers responded by idling capacity in Italy and Spain rather than passing full cost through, which suppressed volumes precisely when lightweight glass demand was recovering.

Fee Fragmentation Across 27 Systems

An identical SKU may be subject to significantly different eco-modulated fees in Berlin, Madrid, and Warsaw because producer-responsibility programs are still managed nationally. Wide variations in fee design and modulation criteria among European schemes have been reported by the OECD [11]. Thus, country-specific artwork and declaration protocols are maintained by compliance teams, and the administrative burden discourages smaller brand owners from launching their products throughout Europe.


Europe Sustainable Packaging Market Opportunities

Reusable Transit Systems for Grocery Retail

PPWR reuse quotas create a service market, not just a product market. Retailers running pooled crate systems already report loop counts above 40 rotations per asset, and the economics turn positive once tracking costs fall below EUR 0.05 per movement. Pool operators with existing depot networks are best placed to capture it.

CEE Conversion Capacity as an Emerging Play

Poland, Romania, and Czechia offer converter labour costs roughly 45% below German levels alongside EU-27 regulatory alignment. That combination is pulling fill-and-pack work eastward and creating greenfield opportunities in corrugated and thermoformed lines. Central & Eastern Europe's 5.4% CAGR reflects that migration more than domestic consumption growth.

Return Infrastructure Monetisation

Deposit return schemes generate high-purity feedstock and, incidentally, a data asset. Operators in Germany and the Nordics process billions of containers annually, and the resulting material-flow telemetry has commercial value to brand owners modelling recyclability compliance. Selling verified capture data alongside baled material is an emerging revenue line.

Barrier Coatings for Fiber Substitution

Plastic trays and pouches can be replaced with bio-based and dispersion-coated barrier layers. The largest single replacement pool in the European Sustainable Packaging Market will be opened to suppliers that can verify grease and moisture performance under EU food-contact regulations while maintaining repulpability.


Compliance-as-a-Service Platforms

Fee calculation, artwork declaration, and design-for-recycling scoring are being productised. Subscription platforms priced per SKU per market are replacing consultancy retainers, and the addressable base runs to hundreds of thousands of active European SKUs.


Europe Sustainable Packaging Market Future Outlook

Machine Learning on the Converting Line

On new corrugated and flexo lines, vision-based flaw detection and predictive maintenance are transitioning from pilot to standard specification. When material is 60–70% of converted cost, early adopters claim scrap reduction in the 15–20% range, which is more significant than it may seem. Industrial digitalization is associated with quantifiable improvements in manufacturing process efficiency, according to the International Energy Agency [17].


Platform Economics in Circular Systems

Reuse and return systems behave like networks: value rises non-linearly with participating retailers. Expect consolidation into three or four pan-European pooling platforms by 2032, with asset-light operators licensing crate and cup standards rather than owning fleets. The Ellen MacArthur Foundation's reuse economics work frames the tipping point around shared standardisation [4].

Decarbonisation of Material Production

The two most significant decarbonization levers are electric melting for glass and low-carbon aluminum remelt. Through the 2030s, IRENA anticipates further cost reductions in renewable industrial heat and electrical pathways, improving glass and metal's relative position against polymer approaches [18]. By 2030, converters who sign power purchase agreements today will appear prophetic.


Disclosure Becomes a Commercial Input

The Corporate Sustainability Reporting Directive pulls packaging-level material data into audited financial reporting for thousands of European companies [19]. Once packaging footprints sit in the annual report, procurement decisions face board scrutiny — and suppliers who can furnish verified, line-item material declarations win share on data quality alone.


Regional Market Share Analysis

Region Metric (2025 unless noted) Primary Investment Themes
Western Europe 38.5% share Line conversion, digital printing, reuse pilots
Northern Europe USD 34.32 Billion Deposit infrastructure, fiber barrier R&D
Southern Europe 19.5% share Glass lightweighting, agri-food formats
Central & Eastern Europe 5.4% CAGR (2026–2035) Greenfield corrugated, contract conversion
Russia & Rest of Europe USD 12.26 Billion Domestic substitution, import replacement
Total USD 163.41 Billion

Geographic performance in the Europe Sustainable Packaging Market splits along regulatory maturity and converter density rather than population. Western Europe sets the technical standard; Central & Eastern Europe captures the volume migration; Northern Europe leads on circularity infrastructure. The table below shows one calibrated metric per region.


Western Europe

Country Metric Key Driver
Germany 34.5% of region Converter density, VerpackG enforcement
France USD 13.28 Billion AGEC anti-waste law obligations
Benelux 4.2% CAGR Port-linked logistics packaging
Austria & Switzerland 9.8% of region Pharmaceutical barrier demand


Germany remains the technical centre of gravity. VerpackG registration data covers hundreds of thousands of obligated producers, and eco-modulated fees have already repriced problem formats out of the market [11]. France's AGEC law moved faster than EU-level rules on plastic bans and reuse targets, forcing early reformulation among domestic food brands and giving French converters a head start on fiber tray qualification.

Northern Europe

Country Metric Key Driver
United Kingdom 51.4% of region Plastic Packaging Tax, retailer pledges
Nordic Countries USD 11.05 Billion High collection rates, board integration
Ireland 4.9% CAGR Pharmaceutical and dairy export packaging
Baltic States 4.6% of region Contract manufacturing growth


The United Kingdom's Plastic Packaging Tax and ambitious retailer pledges anchored its dominance at 51.4% of the northern region, while Nordic countries leveraged high collection rates and advanced board integration to reach a market valuation of USD 11.05 billion. At the same time, Ireland achieved a robust 4.9% CAGR driven by specialized pharmaceutical and dairy export packaging, and the Baltic States captured 4.6% of the region through expanding contract manufacturing capabilities.

Southern Europe

Country Metric Key Driver
Italy 44.2% of region CONAI consortium system, food processing
Spain USD 9.87 Billion Royal Decree 1055/2022 obligations
Portugal 4.4% CAGR Wine and agri-food exports
Greece 6.1% of region Tourism-linked foodservice demand


Italy's CONAI consortium pioneered eco-modulated contributions years before EU harmonisation, and its tiered fee bands remain a reference model for other member states [11]. Spain layered a national plastics tax onto its 2022 packaging decree, which accelerated glass and board substitution in beverages, though energy costs blunted the response among smaller Andalusian and Catalan converters.

Central & Eastern Europe

Country Metric Key Driver
Poland 5.51% CAGR Contract conversion inflows, deposit rollout
Czechia USD 2.71 Billion Automotive and FMCG co-packing
Hungary 9.4% of region State-run concession scheme
Romania 5.2% CAGR Beverage container return system scale-up


Poland is where Western European brand owners are placing new conversion volume, drawn by wage differentials and EU regulatory equivalence. Romania's container return system, launched in late 2023, moved from zero to national coverage in under two years and now processes billions of units annually — a demonstration that CEE infrastructure can scale faster than incumbents assumed [9].

Russia & Rest of Europe

Country Metric Key Driver
Russia 58.3% of region Domestic substitution post-sanctions
Türkiye USD 3.14 Billion Export converter base, EU proximity
Rest of Europe 3.4% CAGR Balkan food processing, Ukraine reconstruction


Sanctions severed most Western equipment and additive supply into Russia, pushing converters toward domestic resin and simpler formats — a de-sophistication trend that caps growth. Türkiye plays the opposite role, exporting flexible and corrugated output into EU-27 buyers while operating outside EU fee structures, which gives its converters a cost advantage that PPWR border-adjacent rules may eventually narrow.


Europe Sustainable Packaging Market By Region, 2025-2035

Europe Sustainable Packaging Market Segmentation

By Material

Material choice is the primary axis of competition in the Europe Sustainable Packaging Market because it determines both compliance exposure and cost volatility.

Segment Metric Primary Demand Driver
Paper and Board (Cartonboard, Molded Fibre, and More) 37.7% share (2025) Plastic substitution in food service and e-commerce
Plastic (PE, PP, PET, and More) USD 55.89 Billion (2025) Mono-polymer redesign, rPET offtake
Glass 3.6% CAGR (2026–2035) Premium beverage, refill formats
Metal (Cans, Caps and Closures, Tubes, and More) USD 19.12 Billion (2025) Beverage can substitution, high recycling yield


Paper and board's lead is structural rather than cyclical. Fibre carries the strongest consumer recyclability perception in Europe and the highest actual collection rates, so brand owners substituting away from laminates default to board unless barrier requirements block it. Plastic's position is more nuanced: absolute tonnage is flat to declining, but value per tonne is rising as mono-material PET and PP command recyclate premiums and specification complexity.

By Packaging Format

Format economics in the European Sustainable Packaging Market are diverging sharply as reuse mandates favour durable structures over single-trip ones.

Segment Metric Primary Demand Driver
Rigid 6.0% CAGR (2026–2035) Reuse quotas, deposit-return compatibility
Flexible USD 67.82 Billion (2025) Weight efficiency, mono-layer redesign
Semi-Rigid 14.5% share (2025) Ready-meal trays, fibre thermoforms


Rigid formats win the decade because refillable and returnable systems require structures that survive 30-plus cycles, and only rigid geometries qualify. Flexibles retain the largest installed value base and remain unbeatable on material efficiency per unit of product protected, but their recyclability story depends entirely on whether single-polymer laminates achieve reliable sortation at European MRFs — an unresolved technical question with billions in revenue attached.

By End-User Industry

Demand concentration across end markets shapes how quickly the European Sustainable Packaging Market absorbs new material technology.

Segment Metric Primary Demand Driver
Food 35.9% share (2025) Shelf-life requirements, retailer mandates
Beverage USD 44.77 Billion (2025) Container return systems, can substitution
Pharmaceutical and Healthcare 5.4% CAGR (2026–2035) Serialisation, cold-chain barrier needs
Personal Care and Cosmetics 10.6% share (2025) Refill formats, premium fibre tubes
Household Care 4.1% CAGR (2026–2035) Concentrate dosing, refill pouches
Other End-User Industries USD 10.13 Billion (2025) Industrial and electronics protection


Food sets the pace because it combines the largest volume with the hardest technical constraint — any material change must preserve shelf life or the substitution fails commercially regardless of its environmental merit. Beverage moves fastest on measurable circularity because deposit systems give it a closed loop nobody else has, letting brands make verifiable claims that food and personal care simply cannot match today.


Competitive Benchmarking

Concentration is moderate. The estimated HHI sits near 620, with the top five participants controlling roughly 32–37% of the Europe Sustainable Packaging Market — a fragmented structure by industrial standards, sustained by regional converter networks, freight economics that limit shipping radius, and customer preference for dual sourcing. Consolidation continues at the mid-market tier, where sub-scale converters lack the capital to fund line conversion.

Company Est. Revenue Share Range Key Offerings for Europe Sustainable Packaging Market Strategic Positioning
Amcor plc ~7–10% Mono-material flexibles, recycle-ready laminates Global scale, materials science depth
Smurfit Westrock ~6–9% Corrugated, bag-in-box, fibre-based e-commerce Integrated fibre from mill to converter
Tetra Pak (Tetra Laval) ~5–8% Aseptic cartons, fibre-based barrier caps Aseptic incumbency in dairy and juice
Mondi plc ~4–7% Kraft paper, functional barrier papers Paper-first substitution specialist
Ardagh Group ~4–6% Glass containers, aluminium beverage cans Dual-substrate beverage focus
Ball Corporation ~3–6% Aluminium beverage cans, closures Can substitution beneficiary
Berry Global ~3–5% Rigid containers, recycled resin formats Broad rigid portfolio, scale purchasing
Huhtamaki Oyj ~3–5% Moulded fibre trays, foodservice packaging Fibre foodservice leadership
Sealed Air ~2–4% Protective and vacuum packaging systems Equipment-plus-material model
Stora Enso ~2–4% Cartonboard, formed fibre, wood-based barriers Forest-integrated supply security
SIG Group ~2–4% Aseptic carton systems, filling equipment Carton systems challenger
Crown Holdings ~2–4% Food and beverage cans, aerosol containers Metal packaging specialist


Recent News & Developments

  • European Parliament and Council (January 2025): Formal adoption of the Packaging and Packaging Waste Regulation concluded, setting recyclability, reuse, and minimum recyclate thresholds that reshape design specifications across the European Sustainable Packaging Market [1]


  • Amcor (March 2024): Commissioned expanded recycle-ready flexible film capacity in continental Europe targeting pet food and confectionery converters [21]
  • Huhtamaki (September 2024): Announced moulded fibre line investment in Germany aimed at replacing plastic ready-meal trays for retail private label [22]


  • Mondi (February 2025): Completed acquisition of Western European flexible packaging assets, expanding kraft paper conversion footprint [24]
  • European Commission (June 2024): Innovation Fund allocation confirmed for low-carbon glass and paper production projects across four member states [2]


Europe Sustainable Packaging Market Report Scope

Parameter Detail
Market Scope Sustainable and circular-design packaging across Europe, spanning material, packaging format, end-user industry, and country
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 4.35% (2026–2035)
Market Size Checkpoints USD 163.41 Billion (2025); USD 170.00 Billion (2026); USD 249.39 Billion (2035)
Fastest Growing Segments Rigid formats (6.0% CAGR); Pharmaceutical and Healthcare (5.4% CAGR); Central & Eastern Europe (5.4% CAGR)
Companies Profiled Amcor, Smurfit Westrock, Tetra Pak, Mondi, Ardagh, Ball, Berry Global, Huhtamaki, Sealed Air, Stora Enso, SIG Group, Crown Holdings
Valuation Currency USD Billion

FAQs

How should procurement teams structure supplier contracts in the Europe Sustainable Packaging Market?
Index recyclate pricing to a published benchmark rather than fixing it, and tie volume commitments to compliance milestones instead of calendar years. Build in requalification cost-sharing clauses so material changes do not become unilateral supplier expense [10].
What matters most in due diligence on a European converter acquisition target?
Check line convertibility before checking EBITDA. A converter whose assets cannot run fibre substrates or mono-polymer films faces mandatory recapitalisation, and that liability rarely appears in the quality-of-earnings report [13].
Which certification schemes carry real commercial weight with European retailers?
FSC and PEFC chain-of-custody remain non-negotiable for fibre. For recyclability claims, retailers increasingly require third-party design-for-recycling assessment rather than self-declaration, which shifts audit cost onto suppliers [8].
How does reusable transit packaging compare with single-trip formats in the Europe Sustainable Packaging Market?
Reusable systems break even between 20 and 30 rotations depending on reverse-logistics distance. Below roughly 300 kilometres, pooled crates win decisively; beyond that, transport emissions and cost erode the advantage [4].
What integration problems arise when converting a filling line to fibre-based formats?
Fibre trays behave differently under vacuum and heat-seal conditions, so sealing heads and vision systems usually need replacement, not adjustment. Budget six to ten weeks of qualification downtime per line [5].
Is contract conversion or owned capacity the better entry route into the European Sustainable Packaging Market?
Contract conversion suits entrants below roughly 15,000 tonnes annual volume, preserving flexibility while regulation settles. Owned capacity makes sense only with anchor-customer commitments covering 60% of nameplate output [13].
How are packaging data platforms generating revenue beyond compliance reporting?
Material-flow telemetry from return systems is being sold to brand owners for recyclability modelling and to investors for disclosure verification. Subscription pricing per SKU per market has become the prevailing commercial structure [19].    
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















