Europe Solar Inverter Market (2026 - 2035)

Europe Solar Inverter Market Research Report By Type (Central Inverter, Micro Inverter, String Inverter), By System Type (On-Grid, Off-Grid), By Application (Residential, Commercial, Utilities), By Phase (Single-Phase, Three-Phase) - Forecast to 2035
ID: MRFR/EnP/46855-HCR 200 Pages Snehal Singh Last Updated: October 01, 2026
Europe Solar Inverter Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.43%
2025 Market SizeUSD 3.19 Billion
2035 Market SizeUSD 5.85 Billion
Key Players
Huawei Technologies Co., Ltd.
SMA Solar Technology AG
Sungrow Power Supply Co., Ltd.
SolarEdge Technologies Inc.
Fronius International GmbH
Power Electronics España S.L.
Opportunities
  • Grid-Forming and Grid-Support Retrofits
  • Emerging Markets in Central, Eastern, and Southeastern Europe
  • Energy Management Software and Flexibility Services

Europe Solar Inverter Market Summary

The Europe Solar Inverter Market was valued at USD 3.19 billion in 2025 and is projected to reach USD 3.34 billion in 2026, climbing to USD 5.85 billion by 2035 at a CAGR of 6.43% over 2026–2035. Two policy anchors underpin that trajectory: the REPowerEU plan, which targets close to 600 GW of AC solar capacity by 2030 [1], and 65.5 GW of new EU installations in 2024 that kept inverter demand high even through a destocking year [3].

Technology is shifting quickly. Standalone string and central units designed for simple feed-in are giving way to hybrid, battery-ready platforms with grid-forming firmware, remote diagnostics, and module-level optimization. Grid operators are pushing the change: the European Commission estimates that EUR 584 billion of grid investment is needed this decade [6], and new connection rules increasingly require inverters to support voltage and frequency rather than simply export power.

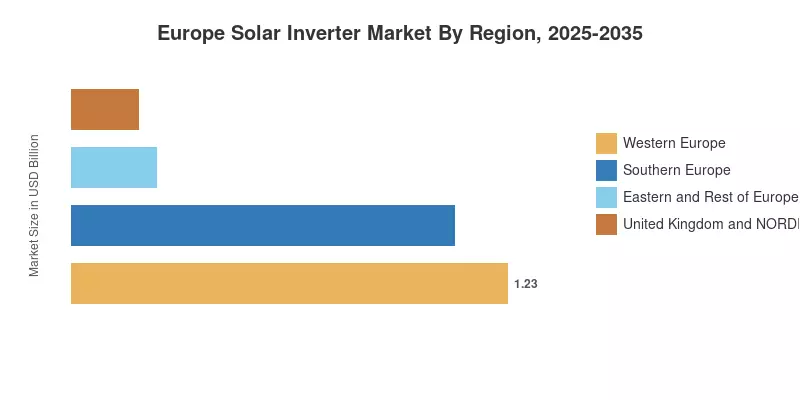
Regionally, Western Europe leads with a 38.5% share, anchored by Germany's rooftop and storage boom. Eastern and the Rest of Europe is the fastest-growing cluster at a 7.6% CAGR as Poland, Romania, and Greece scale auctions, while Southern Europe ranks second on Iberian utility pipelines and Italian rooftop demand. Over the forecast period, grid-code compliance and storage integration, rather than raw capacity additions, will decide which suppliers gain share in the Europe Solar Inverter Market.

Key Report Takeaways

• By Inverter Type

  • Central Inverters captured a 45.2% revenue share in 2025, the largest of any inverter type in the Europe Solar Inverter Market
  • Microinverters are projected to expand at a 7.8% CAGR through 2035, supported by plug-in balcony PV and rooftop safety codes

• By Phase

  • Three-Phase equipment accounted for a 68.5% share in 2025 on the strength of C&I and utility demand.
  • Single-Phase devices are set for a 6.9% CAGR as residential hybrid adoption rises.

• By Connection Type

  • On-Grid products held an 86.4% share of 2025 sales
  • Off-Grid solutions are the fastest-growing connection type at an 8.3% CAGR

• By Application

  • Utility-Scale projects represented a 55.0% share in 2025
  • Commercial and Industrial installations generated USD 0.94 billion in 2025
  • Residential is the fastest-growing application in the Europe Solar Inverter Market, at a 7.3% CAGR

• By Region

  • Western Europe led with a 38.5% share in 2025
  • Southern Europe generated USD 1.08 billion in 2025
  • Eastern and Rest of Europe is forecast to grow at a 7.6% CAGR, the fastest regional rate

Market Size and Forecast (2021–2035)

Historical sizing of the Europe Solar Inverter Market combines shipment data from manufacturer filings, national installation registries such as Germany's Marktstammdatenregister, and industry association statistics [3][17], converted to revenue using regional average selling prices. Forecast values apply scenario-weighted capacity additions and inverter price curves, cross-checked against IEA and IRENA outlooks [4][16].
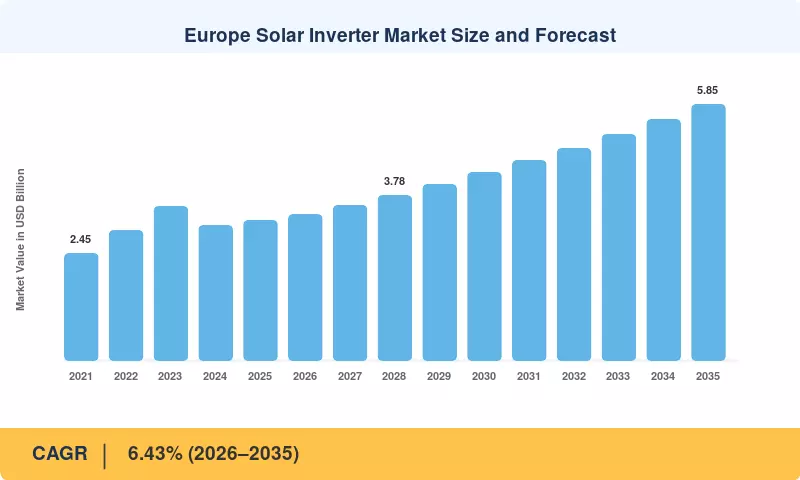
Europe Solar Inverter Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
REPowerEU and national solar capacity targets ~+1.4% EU-wide; strongest in Germany, Spain, Italy Long-term (≥4 yr)
Residential storage attachment and hybrid inverter demand ~+1.1% Germany, Italy, Netherlands, Austria Medium-term (2–4 yr)
Faster permitting under emergency and RED III rules ~+0.8% EU-27 Short-term (≤2 yr)
Grid-code tightening and grid-forming requirements ~+0.7% Spain, Portugal, Germany, UK Medium-term (2–4 yr)
Replacement of first-generation feed-in tariff fleets ~+0.9% Germany, Italy, Czech Republic, Belgium Long-term (≥4 yr)
EPBD solar-ready building mandates ~+0.6% EU-27 Long-term (≥4 yr)


REPowerEU and National Solar Capacity Targets

Brussels set the direction in 2022: the EU Solar Energy Strategy targets over 320 GW of AC capacity by 2025 and almost 600 GW by 2030 [2], roughly doubling the fleet installed at the end of 2024. National plans translate that ambition into procurement. Germany's EEG 2023 legislates 215 GW by 2030 [14], and Spain's updated PNIEC raises its 2030 solar goal to 76 GW. Each gigawatt added requires fresh inverter capacity, giving the European Solar Inverter Market a volume floor that outlasts short-term price cycles.

Residential Storage Attachment and Hybrid Inverter Demand

Household economics now favor self-consumption over export. With retail tariffs across much of Western Europe still well above pre-2021 levels and feed-in rates falling, roughly three in four new German home PV systems ship with a battery [3]. Germany's zero-rate VAT on systems up to 30 kW, in force since January 2023, lowered upfront costs further. Hybrid inverters capture that value because one device manages the array, the battery, and often an EV charger, lifting average selling prices per household.

Faster Permitting Under Emergency and RED III Rules

Council Regulation (EU) 2022/2577 capped permitting for rooftop solar at three months and exempted many installations from environmental assessment [5]. RED III, adopted in 2023, made the shift permanent by requiring renewables acceleration areas alongside a binding 42.5% renewable share by 2030 [7]. Shorter queues convert pipeline into installed capacity sooner, pulling inverter orders forward, especially for commercial rooftops that previously waited a year or more for approval.

Grid-Code Tightening and Grid-Forming Requirements

Inverter-based generation now dominates midday supply in several markets, and system operators are responding. The EU Network Code on Requirements for Generators [11] is under revision to add grid-forming capabilities, and Germany's VDE-AR-N 4105 already mandates reactive-power control for low-voltage systems [13]. The 28 April 2025 Iberian blackout, which saw roughly 15 GW of generation disconnect within seconds, intensified scrutiny of voltage-control performance [12]. Compliant products command price premiums and accelerate retirement of older fleets.

Replacement of First-Generation Feed-In Tariff Fleets

Europe's first solar wave arrived between 2009 and 2013, when Germany added about 7 GW a year and Italy installed more than 9 GW in 2011 alone. Inverters typically last 10–15 years, roughly half the service life of modules [16], so that installed base is entering its replacement window. For the Europe Solar Inverter Market, repowering creates recurring demand that is less sensitive to new-build subsidies, and owners often upgrade to hybrid units during the swap.

EPBD Solar-Ready Building Mandates

The recast Energy Performance of Buildings Directive requires solar installations on new public and non-residential buildings above 250 m² from end-2026, on existing large public and non-residential buildings in phases from 2027, and on new residential buildings from end-2029 [8]. These mandates convert discretionary purchases into compliance spending and favor three-phase string and hybrid units sized for commercial roofs, adding a predictable demand layer through the 2030s.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Price erosion from Asian manufacturing overcapacity ~-0.9% EU-wide Short-term (≤2 yr)
Grid congestion, curtailment, and negative prices ~-0.8% Germany, Netherlands, Spain Medium-term (2–4 yr)
Cybersecurity and remote-access restrictions ~-0.5% Lithuania, EU-wide Medium-term (2–4 yr)
Phase-out of net metering and feed-in support ~-0.6% Netherlands, Belgium, Italy Short-term (≤2 yr)
Shortage of certified installers and electricians ~-0.4% EU-wide Medium-term (2–4 yr)


Price Erosion from Asian Manufacturing Overcapacity

Chinese inverter capacity expanded far faster than European demand in 2023, leaving distributors holding months of excess stock. The correction hit incumbents hard: SolarEdge's revenue fell from about USD 3.0 billion in 2023 to roughly USD 0.9 billion in 2024 [18], and SMA reported sharply lower sales [17]. Falling average selling prices compress revenue growth in the Europe Solar Inverter Market even when unit shipments rise.

Grid Congestion, Curtailment, and Negative Prices

On sunny days, solar output now meets midday demand. In 2024, Germany saw 457 hours of negative wholesale prices [15], and new EEG regulations prohibit paying new plants during those times. In the majority of the Netherlands' provinces, grid operators keep waiting lists for commercial connections. Inverter orders are delayed because curtailment risk increases the payback period for merchant and C&I projects.


Cybersecurity and Remote-Access Restrictions

Since inverters are networked equipment, governments are beginning to view them as essential infrastructure. In November 2024, Lithuania prohibited suppliers from high-risk countries from remotely accessing installations larger than 100 kW [22], and the Cyber Resilience Act mandates vulnerability reporting and secure-by-design [10]. Procurement reviews stall tenders, and compliance increases the cost of firmware, testing, and certification.

s

Phase-Out of Net Metering and Feed-In Support

Net-metering phase-outs weaken the export case for residential systems. The Netherlands will end its salderingsregeling on 1 January 2027 [23], removing a scheme that let households offset exported power one-for-one. A similar transition in Belgium's Flanders region depressed installations after 2021. Buyers pause during these transitions, though demand partly shifts toward hybrid systems with storage.

Shortage of Certified Installers and Electricians

Installation capacity, not hardware, is the bottleneck in several markets. SolarPower Europe estimates the EU solar workforce must roughly double by 2030 to meet targets [3], and electrician shortages are acute in Germany and the Nordics. Longer installation lead times cap how fast residential and C&I inverter demand can convert, particularly for complex hybrid retrofits.

Europe Solar Inverter Market Opportunities

Grid-Forming and Grid-Support Retrofits

System operators need inverters that stabilize the grid rather than follow it. After the April 2025 Iberian blackout [12], ENTSO-E and Spanish authorities placed voltage-control performance at the center of their review, and the pending revision of generator connection rules adds grid-forming requirements [11]. Suppliers that deliver virtual-synchronous firmware, retrofit kits, and co-located battery inverters for existing utility plants can capture premium margins in a niche where compliance, not price, drives selection.

Emerging Markets in Central, Eastern, and Southeastern Europe

With the help of cohesion financing and the EU Modernization Fund, Poland, Romania, Bulgaria, Hungary, and Greece currently install several gigawatts annually [3]. Projects require strong grid-support features and frequently storage since local distribution networks are weaker. The fastest-growing segment of the European solar inverter market is open to vendors who establish local service facilities and channel relationships early on.

the

Energy Management Software and Flexibility Services

A stream of generation, consumption, and battery data is produced by each hybrid inverter. Section 14a of Germany's Energy Industry Act permits grid operators to dim controlled devices in exchange for reduced network fees, and the country mandated that power suppliers provide dynamic rates starting in 2025 [6]. Manufacturers can generate recurring revenue beyond hardware by monetizing this data through grid-service revenue sharing, virtual power plant aggregation, and subscription energy-management apps.


Plug-In Balcony Solar

Germany's Solarpaket I raised the plug-in PV limit to 800 VA of inverter output and simplified registration [14], turning balcony kits into a mass retail product. Apartment dwellers, long excluded from rooftop solar, are the target buyers. Microinverter makers with certified plug-and-play units and retail partnerships are best placed, and comparable rules are spreading to Austria and other neighbors.

EU-Manufactured Supply Under NZIA Resilience Criteria

The Net-Zero Industry Act requires member states to apply non-price criteria, including resilience and cybersecurity, to at least 30% of renewable auction volumes [9]. It also sets a 40% benchmark for domestic manufacturing of net-zero technologies by 2030. European inverter makers and non-EU suppliers that localize assembly and data hosting stand to win auction-linked demand.

Europe Solar Inverter Market Future Outlook

Software-Defined Inverters and AI-Driven Operations

Inverters are evolving into platforms for software. Grid-code features, battery compatibility, and tariff optimization are now added by over-the-air software after installation, and fleet operators utilize machine-learning models on inverter data to anticipate faults before they result in downtime. The installed base generating this data will continue to grow since the IEA projects that solar PV will provide roughly 80% of the expansion in global renewable capacity through 2030 [4]. Strong analytics will generate service income for vendors over the course of an asset's ten-year lifespan.


Hybridization and the Flexibility Economy

Inverters from export devices are transformed into flexible assets through storage. Storage is one of the fastest-growing sectors in global energy transition investment, which reached around USD 2.1 trillion in 2024 [21]. Hybrid and battery inverters will increasingly be offered in packages that take part in virtual power plants and balancing markets in the European solar inverter market, moving competitiveness toward energy-management capability.


Electrification of Heat and Transport

Heat pumps and EVs raise household electricity demand and make on-site generation more valuable. The RED III target of 42.5% renewables by 2030 [7] depends on electrified end uses, and IRENA data show solar PV remains among the lowest-cost new generation sources [16]. Inverters that coordinate PV, batteries, heat pumps, and bidirectional chargers will become the household energy hub.

Cybersecurity, Sovereignty, and Sustainability Reporting

Procurement criteria are widening beyond price and efficiency. The Cyber Resilience Act [10] and NZIA resilience criteria [9] will make data-hosting location, firmware transparency, and supply-chain origin formal scoring factors. Corporate buyers subject to sustainability disclosure rules also want embodied-carbon data and repairability commitments. Suppliers with European manufacturing, verified security practices, and product carbon footprints will be better positioned in public and corporate tenders.

Regional Market Share Analysis

Region Key Metric (one per row) Primary Investment Themes
Western Europe 38.5% share (2025) Residential hybrids, storage retrofits, repowering
Southern Europe USD 1.08 Billion (2025) Utility-scale PPAs, Italian rooftop and C&I self-consumption
United Kingdom and NORDIC Countries 6.1% CAGR (2026–2035) C&I rooftops, heat-pump-driven self-consumption
Eastern and Rest of Europe 7.6% CAGR (2026–2035) Auction-led utility builds, EU cohesion funding
Total USD 3.19 Billion (2025) —

Europe's regional demand splits along two lines: mature rooftop-and-storage markets in the northwest and utility-driven markets in the south and east. The table below summarizes each cluster of the Europe Solar Inverter Market, with one headline metric per region.


Western Europe

Country Key Metric (one per row) Key Driver
Germany 58.0% share of region (2025) Battery attachment, tenant electricity, plug-in PV
France USD 295 Million (2025) Rooftop self-consumption and commercial tenders
Netherlands 5.2% CAGR (2026–2035) C&I rooftops and battery retrofits after net-metering exit


Germany dominates the cluster. The country added about 16 GW of PV in 2024, and Solarpaket I eased rules for rooftop, tenant-electricity, and plug-in systems [14]. France is scaling rooftop deployment under its multi-year energy plan, while the Netherlands, one of Europe's most saturated rooftop markets per capita, faces a residential pause ahead of the 2027 net-metering exit [23]. Hybrid attachment and replacement of pre-2013 inverters sustain value even where new-build volumes flatten.

Southern Europe

Country Key Metric (one per row) Key Driver
Spain 54.0% share of region (2025) Utility PPAs and storage retrofits at existing plants
Italy 6.9% CAGR (2026–2035) Residential rooftops and C&I self-consumption


Spain holds the larger share on the strength of its utility pipeline and a PNIEC target of 76 GW of solar by 2030. Price cannibalization and curtailment are pushing Spanish developers to add storage, which creates demand for battery inverters at operating plants. Italy's growth is broader-based: residential rooftops, C&I self-consumption, and a PNIEC goal of nearly 80 GW of solar by 2030 all feed inverter demand .

United Kingdom and NORDIC Countries

Country Key Metric (one per row) Key Driver
United Kingdom USD 205 Million (2025) C&I rooftops and Contracts for Difference solar rounds
NORDIC Countries 6.6% CAGR (2026–2035) Residential solar-plus-storage in Sweden and Denmark


The United Kingdom accounts for the larger share, driven by C&I rooftops and utility projects contracted through Contracts for Difference rounds, with the government targeting 45–47 GW of solar by 2030. Across the NORDIC Countries, Sweden and Denmark lead; modest irradiance is offset by high prices in southern bidding zones and strong heat-pump adoption, which raises the value of on-site generation.

Eastern and Rest of Europe

Country Key Metric (one per row) Key Driver
Russia 3.1% CAGR (2026–2035) Localized assembly under sanctions-constrained supply
Rest of Europe 84.0% share of region (2025) Auctions in Poland, Greece, Romania, and Portugal


The rest of Europe, led by Poland, Greece, Romania, Portugal, and Bulgaria, drives the cluster's momentum. Poland passed roughly 20 GW of cumulative PV by 2024 [3], and Greece and Romania run regular auctions backed by EU Recovery and Modernisation Fund money. Russia's market remains small and largely isolated, with sanctions limiting access to Western and many Asian suppliers and favoring domestic assemblers.

Europe Solar Inverter Market By Region, 2025-2035

Europe Solar Inverter Market Segmentation

By Inverter Type

Segment Key Metric (one per row) Primary Demand Driver
Central Inverters 45.2% share (2025) Utility plants in Spain and Portugal seeking the lowest balance-of-system cost
String Inverters 37.5% share (2025) C&I rooftops and complex-terrain sites needing multiple MPPTs
Microinverters 7.8% CAGR (2026–2035) Module-level optimization and plug-in balcony PV
Hybrid/Battery-Ready Inverters USD 226 Million (2025) Residential storage attachment and backup power


Inverter architecture in the Europe Solar Inverter Market still tilts toward Central Inverters, which win utility tenders where 1–5 MW blocks minimize cabling and civil costs. String Inverters close the gap on commercial roofs and uneven terrain that reward finer MPPT control. Microinverters grow fastest because rapid-shutdown rules and balcony PV favor module-level electronics, while Hybrid/Battery-Ready Inverters ride storage attachment. Grid-forming mandates will pressure legacy central designs lacking virtual-synchronous firmware.

By Phase

Segment Key Metric (one per row) Primary Demand Driver
Single-Phase 6.9% CAGR (2026–2035) Residential systems below 10 kW and hybrid home storage
Three-Phase 68.5% share (2025) C&I and utility arrays requiring balanced load flow


Phase selection across the Europe Solar Inverter Market follows system size. Three-Phase equipment dominates because factories, warehouses, and utility plants require balanced output, and modular 20–100 kW units let owners scale without oversizing. Single-Phase devices grow faster on the back of residential installations, where hybrid models with battery ports and backup capability increase household lock-in. National codes such as VDE-AR-N 4105 [13] require frequent firmware updates that smaller suppliers can struggle to deliver.

By Connection Type

Segment Key Metric (one per row) Primary Demand Driver
On-Grid 86.4% share (2025) Mature networks and export-oriented PPA models
Off-Grid 8.3% CAGR (2026–2035) Island communities replacing diesel generation


Connection preferences in the Europe Solar Inverter Market reflect dense, reliable networks, so On-Grid products dominate sales. Off-Grid solutions grow faster as Greek and Italian islands replace diesel generators and remote agricultural sites add solar-plus-storage. Hybrid units blur the line: grid-tied inverter systems with islanding capability let households ride through outages and maximize self-consumption as net metering fades, expanding demand in both modes.

By Application

Segment Key Metric (one per row) Primary Demand Driver
Residential 7.3% CAGR (2026–2035) High retail tariffs, faster permitting, battery and EV charger attachment
Commercial and Industrial USD 0.94 Billion (2025) Demand-charge management and corporate ESG targets
Utility-Scale 55.0% share (2025) Iberian PPAs and Greek and Polish auction schedules


Application demand in the Europe Solar Inverter Market is anchored by Utility-Scale plants, which favor high-capacity three-phase blocks to minimize levelized cost. Residential grows fastest as retail tariffs stay high and Council Regulation 2022/2577 shortens permitting [5], with single-phase hybrids lifting battery and EV charger attach rates. Commercial and Industrial rooftops expand more slowly because lower business tariffs stretch paybacks, though dynamic tariffs that reward peak shaving keep the segment relevant.

Competitive Benchmarking

The Europe Solar Inverter Market is moderately concentrated. Market Research Future estimates an HHI of roughly 1,100–1,300, with the top five suppliers holding about 55–60% of 2025 revenue. Chinese manufacturers lead on volume and price in utility and residential segments, while European incumbents defend share through grid-code expertise, service networks, and trusted-vendor positioning. Competition increasingly turns on software, storage integration, and cybersecurity credentials rather than on solar power electronics hardware alone.

Company Est. Revenue Share Range Key Offerings for Europe Solar Inverter Market Strategic Positioning
Huawei Technologies Co., Ltd. ~15–19% SUN2000 string and residential hybrid inverters, LUNA2000 storage, FusionSolar monitoring Volume leader across segments; faces rising cybersecurity scrutiny.
SMA Solar Technology AG ~10–13% Sunny Central, Sunny Tripower, Sunny Boy, SMA Energy System Home European incumbent with grid-code depth; restructuring for margin
Sungrow Power Supply Co., Ltd. ~10–13% 1+X modular central inverters, string inverters, PowerTitan storage Utility and storage integration strength
SolarEdge Technologies Inc. ~5–8% Power optimizers, Home Hub hybrid, commercial three-phase inverters Premium residential and C&I; rebuilding after 2024 destocking
Fronius International GmbH ~5–7% Symo, Tauro, Primo GEN24 hybrid Austrian manufacturing and installer loyalty
Power Electronics España S.L. ~4–7% FreeSun central inverters, battery power conversion systems Iberian utility-scale specialist
Enphase Energy, Inc. ~3–5% IQ8 microinverters, IQ Battery 5P Microinverter leader in rooftop and balcony PV
GoodWe Technologies Co., Ltd. ~3–5% ET and EH hybrid series, SMT three-phase Price-competitive hybrid supplier
Ginlong Technologies (Solis) ~2–4% Residential and C&I string inverters, S6 hybrid Value-oriented string supplier
Ingeteam S.A. ~2–4% Ingecon Sun central and string inverters Spanish utility and hybrid plant specialist
KOSTAL Solar Electric GmbH ~1–3% PLENTICORE plus hybrid, PIKO CI German residential and C&I, European-made
Victron Energy B.V. ~1–3% MultiPlus and Quattro inverter-chargers Off-grid and island-system leader


Recent News & Developments

  • European Commission (November 2023): Published the EU Action Plan for Grids, estimating EUR 584 billion of grid investment needed by 2030; tighter connection standards raise demand for grid-supportive inverters [6]
  • SolarEdge Technologies (January 2024): Announced a workforce reduction of about 16% after European distributor destocking cut orders, illustrating the depth of the channel correction [18]
  • German Bundestag (April 2024): Passed Solarpaket I, raising the plug-in PV limit to 800 VA and simplifying rooftop and tenant-electricity rules, which widens the microinverter addressable base [14]
  • Council of the EU (May 2024): Gave final approval to the Net-Zero Industry Act, introducing resilience criteria for renewable auctions that favor localized inverter supply [9]
  • SMA Solar Technology (November 2024): Launched a restructuring program including up to 1,100 job cuts globally, signaling capacity discipline across the Europe Solar Inverter Market [17]
  • Seimas of Lithuania (November 2024): Restricted remote access to renewable installations above 100 kW by suppliers from designated high-risk countries, setting an early national precedent [22]
  • European Union (December 2024): The Cyber Resilience Act entered into force, setting secure-by-design and vulnerability-reporting obligations for connected products including inverters [10]
  • ENTSO-E (April 2025): Convened an expert panel after the 28 April blackout in Spain and Portugal, raising the priority of voltage control and grid-forming inverter capability [12]

Europe Solar Inverter Market Report Scope

Parameter Details
Market Scope Revenue from central, string, micro, and hybrid/battery-ready solar inverters sold in the Europe Solar Inverter Market, segmented by inverter type, phase, connection type, application, and region.
Study Period 2021–2035 (Historical: 2021–2024; Base Year: 2025; Forecast: 2026–2035)
CAGR 6.43% (2026–2035)
Market Size checkpoints USD 3.19 Billion (2025); USD 3.34 Billion (2026); USD 4.56 Billion (2031); USD 5.85 Billion (2035)
Fastest Growing Segments Off-Grid (8.3% CAGR); Microinverters (7.8% CAGR); Residential (7.3% CAGR); Single-Phase (6.9% CAGR)
Companies Profiled Huawei, SMA Solar Technology, Sungrow, SolarEdge, Fronius, Power Electronics, Enphase Energy, GoodWe, Ginlong (Solis), Ingeteam, KOSTAL, Victron Energy
Valuation Currency USD (constant 2025 exchange rates)

FAQs

List of Tables
Table 1: Europe Solar Inverter Market Summary Table Table 2: Europe Solar Inverter Market Size and Forecast, 2021–2035 Table 3: Driver Impact Analysis Table 4: Restraints Impact Analysis Table 5: Regional Market Share Summary Table 6: North America Country-Level Analysis Table 7: Europe Country-Level Analysis Table 8: Asia-Pacific Country-Level Analysis Table 9: South America Country-Level Analysis Table 10: Middle East & Africa Country-Level Analysis Table 11: Europe Solar Inverter Market Segmentation by Inverter Type Table 12: Europe Solar Inverter Market Segmentation by Phase Table 13: Europe Solar Inverter Market Segmentation by Connection Type Table 14: Europe Solar Inverter Market Segmentation by Application Table 15: Competitive Benchmarking Matrix Table 16: Report Scope and Methodology Table 17: Detailed Sources and Citations
List of Figures
Figure 1: Europe Solar Inverter Market Size Trend, 2021–2035 Figure 2: Europe Solar Inverter Market Year-over-Year Growth Outlook Figure 3: Regional Revenue Share Analysis Figure 4: Driver and Restraint Impact Matrix Figure 5: Competitive Landscape Snapshot Figure 6: Segment Share by Inverter Type Figure 7: Segment Share by Phase Figure 8: Segment Share by Connection Type Figure 9: Segment Share by Application
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















