Data Center RFID Market (2026 - 2035)

Data Center RFID Market Size, Share and Research Report By Component (Hardware (Tags, Readers, Antennas), Software, Middleware), By Tag Type (Passive, Active), By Data Center Type (Colocation, Enterprise, Edge), By Application (Asset Tracking and Inventory, Workflow Automation) and By Regional (North America, Europe, South America, South Africa, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
ID: MRFR/ICT/6653-HCR 111 Pages Apoorva Priyadarshi, Aarti Dhapte Last Updated: August 24, 2026
Data Center RFID Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)13.5%
2025 Market SizeUSD 2.50 Billion
2035 Market SizeUSD 8.88 Billion
Key Players
Zebra Technologies
Impinj
Avery Dennison
HID Global
Honeywell
Alien Technology
Opportunities
  • AI-Powered Predictive Asset Lifecycle Management
  • Sustainability and Carbon Footprint Tracking
  • Emerging Market Data Center Build-Out

Data Center RFID Market Summary

The Data Center RFID Market reached an estimated USD 2.50 Billion in 2025 and is projected to grow from USD 2.84 Billion in 2026 to USD 8.88 Billion by 2035, registering a CAGR of 13.5% during the forecast period (2026–2035). This acceleration reflects a broader mandate across hyperscale and enterprise operators to digitize physical infrastructure management. Government-backed data sovereignty programs — including the EU Digital Decade initiative targeting 10,000 climate-neutral edge nodes by 2030 [1] — are compelling operators to deploy granular tracking systems that RFID uniquely enables. The Data Center RFID Market is entering a phase where operational visibility is no longer optional but a compliance and efficiency requirement.

Embedded RFID architectures that integrate passive and active devices with middleware analytics platforms are replacing legacy barcode and spreadsheet-based inventory methods. It is estimated that the global data center expenditure exceeded USD 350 billion in 2024 [2], and a significant portion of this budget is being allocated to infrastructure intelligence. Manual audits are unsustainable for operators who oversee tens of thousands of server containers, cables, and power distribution units. A single hyperscale facility may contain more than 100,000 tagged assets. By automating the asset lifecycle from procurement to decommissioning, the Data Center RFID Market directly addresses this pain point.

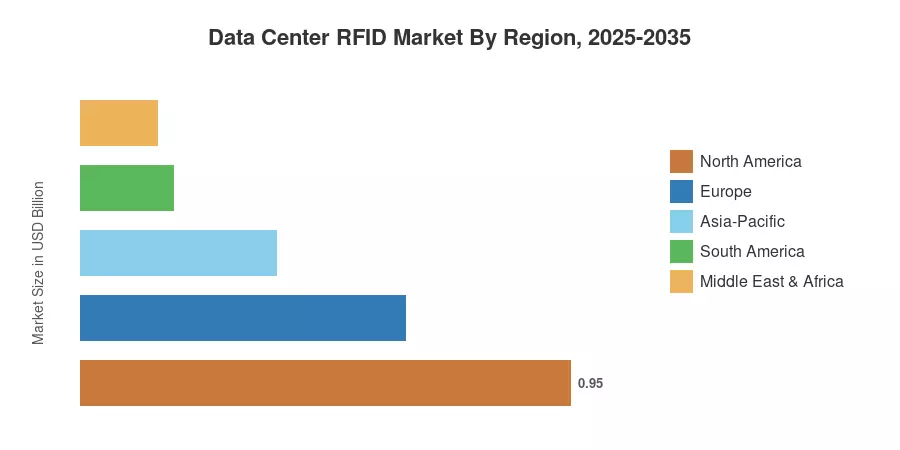
The Data Center RFID Market is primarily dominated by North America, which accounts for approximately 38% of global revenue. This market is characterized by hyperscale deployments in Virginia, Texas, and Oregon [3]. The Asia-Pacific region is the fastest-growing, with an anticipated CAGR of 15.2%. This growth is being driven by the rapid expansion of colocation in India, Japan, and Southeast Asia. Europe is the second-largest region, with an estimated 25% of the market. This is primarily due to GDPR-adjacent audit requirements and sustainability reporting mandates. The Data Center RFID Market is expected to experience structural demand through 2035 as multi-tenant facilities and periphery computing continue to expand.


Key Report Takeaways

• By Component

  • Hardware (tags, readers, antennas) holds roughly 52% of the Data Center RFID Market, driven by large-volume passive tag deployments across hyperscale campuses.
  • Software and middleware segments are expanding at a combined CAGR exceeding 14.8%, as operators prioritize analytics-driven asset intelligence over simple read-write functionality.

• By Tag Type

  • Passive tags dominate approximately 67% of the Data Center RFID Market, owing to lower per-unit cost and suitability for high-density rack environments.


• By Data Center Type

  • Colocation facilities account for the single largest data center type segment at around 41% share, reflecting multi-tenant demand for auditable asset visibility.

• By Region

  • North America leads the Data Center RFID Market with an estimated 38% revenue share, underpinned by the US hyperscale corridor.
  • Asia-Pacific is the fastest-growing region at 15.2% CAGR, with China and India driving capacity build-outs.


Market Size and Forecast (2021–2035)

Market Research Future's sizing methodology integrates primary interviews with data center operators and RFID vendors, validated against public financial disclosures, industry association data from the RAIN RFID Alliance, and third-party infrastructure trackers. Historical figures (2021–2024) are actuals; the base year (2025) is estimated; forecast values (2026–2035) are projected at a 13.5% CAGR with minor annual variation reflecting anticipated adoption curves.
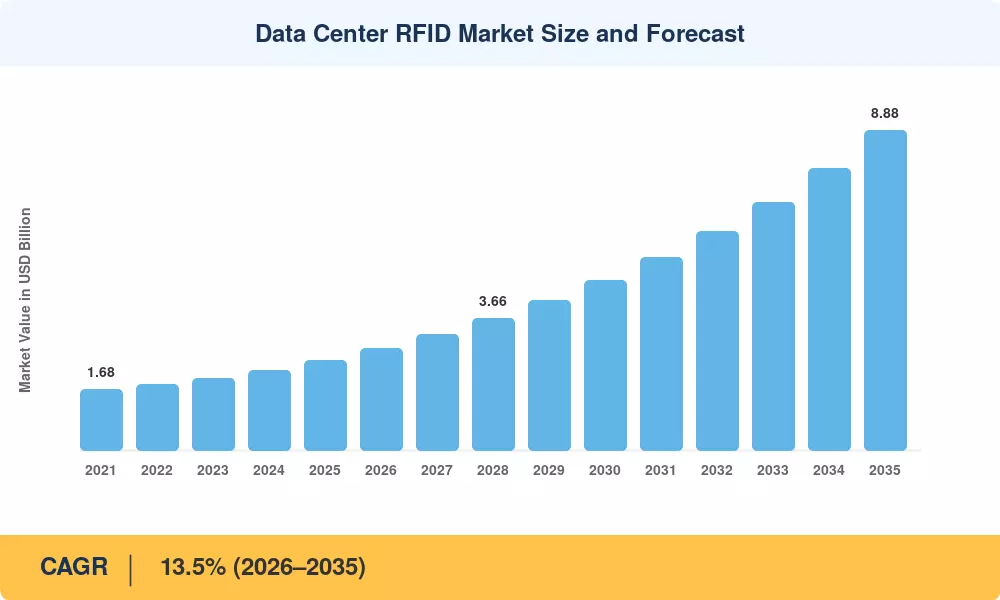
Data Center RFID Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Hyperscale data center expansion 22% Global Short-term (≤2 yr)
Regulatory compliance and audit mandates 18% North America, Europe Medium-term (2–4 yr)
Passive RFID tag cost reduction 16% Global Short-term (≤2 yr)
Edge and micro-data center proliferation 15% Asia-Pacific, Europe Medium-term (2–4 yr)
Digital twin and AI integration 12% North America Long-term (≥4 yr)
Sustainability and carbon tracking requirements 10% Europe, Asia-Pacific Long-term (≥4 yr)
Multi-tenant colocation growth 7% Global Short-term (≤2 yr)


Hyperscale Data Center Expansion

The total capacity of global hyperscale operators surpassed 1,000 campuses worldwide between 2022 and 2024, as a result of the addition of over 120 new facilities [2]. Tens of thousands of assets that are individually trackable are present in each facility, including servers, switches, PDUs, cabling, and spare inventory. Manual tracking is operationally unfeasible at this scale. A growing number of these constructs incorporate RFID-based infrastructure management into the commissioning workflow, and Amazon Web Services, Microsoft Azure, and Google Cloud have collectively disclosed over USD 140 billion in combined capital expenditure plans through 2026 [3]. This expansion cycle directly benefits the Data Center RFID Market.


Regulatory Compliance and Audit Mandates

In the financial services and healthcare data environments, SOC 2 Type II and ISO 27001 certifications now necessitate demonstrable chain-of-custody documentation for IT assets [4]. The 2024 cybersecurity disclosure rules of the Securities and Exchange Commission (SEC) have increased the expectations for physical asset integrity reporting, which has prompted US-based operators to adopt automated audit solutions. European regulators have mirrored this transition through the Digital Operational Resilience Act (DORA), which requires financial entities to establish ICT asset registers by January 2025 [10]. These compliance frameworks establish a regulatory floor for the Data Center RFID Market, which protects demand from fluctuations in cyclical IT spending.


Passive RFID Tag Cost Reduction

The average cost of a passive UHF RFID inlay dropped below USD 0.05 per unit in volume orders during 2024, a 40% decline from 2019 levels [5]. This price trajectory — driven by larger silicon wafer production runs and antenna manufacturing efficiencies — makes tagging every individual cable and accessory economically viable for the first time. The RAIN RFID Alliance reported over 40 billion tags shipped cumulatively through 2024 [5], signaling mass-market maturation. For the Data Center RFID Market, lower tag costs eliminate the primary procurement objection from mid-tier enterprise operators.

Edge and Micro-Data Center Proliferation

projects that 75% of enterprise-generated data will be processed outside centralized data centers by 2029 [6]. Edge sites — often unmanned and geographically dispersed — present acute asset visibility challenges that RFID solves without requiring permanent on-site staff. Telecom operators deploying 5G backhaul infrastructure are particularly active adopters, with NTT and Equinix both piloting RFID-enabled edge cabinets across Asia-Pacific [11]. The Data Center RFID Market captures incremental demand from these smaller, higher-frequency deployment sites.


Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
High upfront integration costs –4.5% Global Short-term (≤2 yr)
Interoperability and standards fragmentation –3.8% Global Medium-term (2–4 yr)
RF interference in dense metal environments –2.5% Global Long-term (≥4 yr)
Data privacy concerns with granular tracking –1.8% Europe Medium-term (2–4 yr)
Limited skilled RFID integration workforce –1.5% Emerging markets Short-term (≤2 yr)


High Upfront Integration Costs

While per-tag costs have fallen sharply, the total cost of an enterprise RFID deployment — encompassing readers, antennas, middleware licenses, cabling, and systems integration — remains substantial. A mid-sized colocation facility with 5,000 rack positions can face initial deployment costs of USD 300,000–500,000 before realizing ROI [12]. This capital intensity disproportionately affects smaller operators and delays adoption in price-sensitive markets. The Data Center RFID Market must contend with this upfront barrier even as long-term economics favor deployment.

Interoperability and Standards Fragmentation

Despite progress by GS1 and the RAIN RFID Alliance, significant gaps remain between vendor-specific tag encoding schemes, middleware APIs, and data formats [13]. Operators running multi-vendor environments — common in colocation settings — encounter integration friction when consolidating RFID data into a single management platform. The absence of a universally adopted data center–specific RFID standard creates switching costs and vendor lock-in risk, dampening competitive pricing dynamics within the Data Center RFID Market.

RF Interference in Dense Metal Environments

Server racks, cable trays, and metal flooring panels create multipath reflection and signal attenuation that challenge RFID read accuracy [14]. Active tags mitigate this through higher signal strength but at greater per-unit cost. Engineering workarounds — including directional antennas and reader placement optimization — add design complexity. For the Data Center RFID Market, solving the physics of RF propagation in metallic enclosures remains a persistent technical constraint that influences tag type selection and deployment architecture.


Data Center RFID Market Opportunities

AI-Powered Predictive Asset Lifecycle Management

Combining RFID telemetry with machine learning models allows operators to predict hardware failures, optimize refresh cycles, and reduce unplanned downtime. The Data Center RFID Market stands to capture a premium software layer as vendors embed predictive analytics directly into middleware platforms. Cisco and Schneider Electric have both demonstrated proof-of-concept integrations linking RFID-sourced location data to AI-driven capacity forecasting engines [7].

Sustainability and Carbon Footprint Tracking

European sustainability disclosure requirements under CSRD (Corporate Sustainability Reporting Directive) demand granular energy attribution at the asset level [8]. RFID enables per-device power consumption correlation when integrated with smart PDU systems, giving operators auditable data for Scope 2 and Scope 3 emissions reporting. The Data Center RFID Market can position sustainability compliance as a value proposition distinct from traditional inventory management, opening a new buyer segment among ESG-focused enterprises.

Emerging Market Data Center Build-Out

India's data center capacity is projected to more than triple between 2024 and 2030, driven by the Digital India initiative and domestic data localization requirements [16]. Brazil, Saudi Arabia, and Indonesia are experiencing similar capacity ramps. These greenfield facilities present an opportunity to embed RFID infrastructure from day one, avoiding the retrofit costs that constrain brownfield adoption. The Data Center RFID Market can achieve faster penetration in emerging economies by bundling RFID systems into turnkey data center construction packages.

RFID-as-a-Service and Managed Subscription Models

Hardware-centric revenue models are giving way to managed service offerings that bundle tags, readers, middleware, and ongoing analytics under annual subscription contracts. This shifts procurement from CapEx to OpEx, lowering the adoption barrier for mid-tier operators. The Data Center RFID Market benefits from recurring revenue streams that improve vendor margin predictability while expanding the addressable customer base.

Secure Decommissioning and Chain-of-Custody Verification

Data destruction compliance — mandated by NIST SP 800-88 and similar frameworks — requires verifiable tracking of storage media from active use through physical destruction [17]. RFID tagging of hard drives, SSDs, and backup tapes creates an immutable audit trail that satisfies regulatory and insurance requirements. The Data Center RFID Market can target this high-value niche by partnering with IT asset disposition (ITAD) providers.


Data Center RFID Market Future Outlook

Autonomous Data Center Operations

The convergence of RFID telemetry, robotic process automation, and AI-driven orchestration is accelerating the transition toward lights-out data center operations. By 2030, an estimated 25% of hyperscale facilities will operate with minimal human on-site presence [7]. The Data Center RFID Market will serve as the sensory backbone for these autonomous environments, providing continuous location, status, and environmental data that robotic systems require to execute maintenance, provisioning, and decommissioning tasks without manual intervention.

Platform Economics and Data Monetization

RFID-generated datasets — encompassing asset utilization rates, thermal mapping, airflow patterns, and lifecycle aging metrics — hold latent commercial value beyond operational efficiency. Colocation providers can leverage anonymized, aggregated RFID data to benchmark facility performance, inform capacity pricing models, and offer premium analytics services to tenants. The Data Center RFID Market will increasingly derive revenue from platform-level subscription services rather than hardware-only transactions, mirroring the broader SaaS transition across enterprise technology.

Electrification and Power Infrastructure Tracking

Global data center electricity consumption is projected to exceed 1,000 TWh by 2030, roughly doubling from 2023 levels [20]. Tracking power distribution equipment — transformers, UPS units, switchgear, and bus bars — with RFID enables granular energy attribution and maintenance scheduling. The Data Center RFID Market will expand its addressable scope from IT assets to electrical and mechanical infrastructure as operators pursue power usage effectiveness (PUE) improvements mandated by regional energy codes and corporate sustainability commitments.

ESG Reporting and Circular Economy Integration

Corporate sustainability frameworks — CSRD in Europe, SEC climate rules in the US, and ISSB standards globally — demand auditable evidence of responsible asset disposal and material recovery [8]. RFID tagging throughout the hardware lifecycle creates a verifiable chain-of-custody that supports circular economy claims and Scope 3 emissions accounting. The Data Center RFID Market is positioned to become integral to ESG compliance infrastructure, with ITAD providers and recyclers adopting RFID as a documentation standard by the early 2030s.


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 38% share Hyperscale campus RFID mandates; compliance-driven auditing
Europe USD 0.63 Billion (2025) GDPR/DORA audit trails; sustainability reporting
Asia-Pacific 15.2% CAGR Colocation expansion in India, Japan, ASEAN
South America 7% share Greenfield builds in São Paulo and Santiago corridors
Middle East & Africa USD 0.15 Billion (2025) Sovereign cloud mandates; UAE smart city programs
Total USD 2.50 Billion (2025)

The Data Center RFID Market exhibits distinct regional adoption patterns shaped by regulatory environments, hyperscale concentration, and colocation density. North America leads on installed base, while Asia-Pacific demonstrates the steepest growth trajectory.


North America

Country Key Metric Key Driver
US 78% of regional share Northern Virginia data center corridor
Canada CAGR 12.8% Toronto and Montreal colocation growth
Mexico USD 0.03 Billion (2025) Nearshoring-driven facility development


The United States remains the backbone of the Data Center RFID Market in North America, with Northern Virginia alone hosting over 3 GW of commissioned data center capacity [3]. Major colocation providers — Equinix, Digital Realty, and QTS — increasingly require RFID-enabled asset management as a standard feature in new leases. Canada benefits from favorable power costs in Québec and Ontario, attracting hyperscale expansion that pulls RFID demand alongside it. Mexico's emerging data center corridor in Querétaro serves as a nearshoring hub for US and Latin American enterprises.

Europe

Country Key Metric Key Driver
Germany 24% of regional share Frankfurt financial data center cluster
UK CAGR 13.1% London Docklands expansion
France USD 0.09 Billion (2025) Paris Saclay campus developments
Italy 8% of regional share Milan edge deployments
Spain CAGR 14.3% Madrid hyperscale corridor
Nordic Countries 15% of regional share Renewable-powered facilities
Russia USD 0.02 Billion (2025) Domestic cloud infrastructure mandates
Rest of Europe CAGR 11.9% Distributed edge networks


DORA compliance requirements effective January 2025 have catalyzed RFID adoption among European financial institutions operating dedicated or leased data center infrastructure [10]. The Frankfurt FLAP-D corridor (Frankfurt, London, Amsterdam, Paris, Dublin) accounts for the majority of European capacity, and operators in these metros face stringent physical asset documentation obligations under both GDPR and national cybersecurity frameworks. The Data Center RFID Market in Europe benefits from regulatory tailwinds that make RFID less a discretionary upgrade and more a compliance necessity.

Asia-Pacific

Country Key Metric Key Driver
China 34% of regional share State-backed "East Data, West Computing" program
India CAGR 17.8% Digital India; Chennai and Mumbai hubs
Japan USD 0.08 Billion (2025) Tokyo/Osaka edge densification
South Korea 12% of regional share Seoul metro colocation expansion
ASEAN CAGR 16.5% Singapore, Jakarta, Bangkok capacity additions
Rest of Asia-Pacific USD 0.03 Billion (2025) Developing market greenfield sites


Asia-Pacific is the fastest-growing region in the Data Center RFID Market, propelled by unprecedented colocation construction in India and Southeast Asia. India added more than 200 MW of new data center capacity in 2024 alone [16], with operators like CtrlS, Yotta, and NTT embedding RFID into commissioning protocols. China's "East Data, West Computing" initiative is redirecting capacity toward inland provinces, creating new RFID deployment opportunities in previously underserved geographies. Japan and South Korea, while more mature, continue investing in edge densification that favors high-frequency RFID-enabled monitoring.

South America

Country Key Metric Key Driver
Brazil 62% of regional share São Paulo metro data center cluster
Argentina CAGR 13.9% Buenos Aires colocation growth
Rest of South America USD 0.03 Billion (2025) Santiago and Bogotá emerging hubs


Brazil's São Paulo metro area has emerged as Latin America's primary data center hub, with Ascenty, Equinix, and ODATA expanding capacity to serve regional cloud demand [18]. The Data Center RFID Market in South America is still nascent but growing rapidly as international operators import asset management standards from their North American and European operations into new Latin American builds.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 29% of regional share NEOM and Vision 2030 digital infrastructure
UAE CAGR 16.2% Dubai smart city and sovereign cloud programs
South Africa USD 0.02 Billion (2025) Johannesburg data center corridor
Egypt CAGR 14.1% New Administrative Capital digital hub
Rest of MEA 18% of regional share Emerging capacity in Kenya and Nigeria


Saudi Arabia and the UAE are leading Middle Eastern investment in data center infrastructure, with NEOM's planned digital backbone and Abu Dhabi's Khazna Data Centers driving demand for embedded RFID tracking [19]. The Data Center RFID Market in MEA benefits from greenfield construction standards that incorporate RFID from the design phase, avoiding the integration complexity common in retrofit scenarios. South Africa's Johannesburg corridor serves as the continental gateway for sub-Saharan deployments.


Data Center RFID Market By Region, 2025-2035

Data Center RFID Market Segmentation

By Component

Segment Key Metric Primary Demand Driver
Hardware (Tags, Readers, Antennas) 52% share Volume tag deployments across hyperscale facilities
Software CAGR 14.8% Analytics and dashboarding demand
Middleware USD 0.31 Billion (2025) System integration and API orchestration


Hardware remains the foundation of the Data Center RFID Market, with passive UHF tags constituting the majority of unit volume. Tags alone represent roughly 60% of the hardware sub-segment, while readers and fixed antennas account for the balance. Hyperscale operators deploying RFID across entire campuses require tens of thousands of tags per facility, creating steady replenishment demand as tags are consumed during asset decommissioning cycles.

Software and middleware are growing faster than hardware as the market matures beyond initial deployment. Operators who completed tag rollouts between 2021 and 2024 are now investing in analytics platforms that transform raw RFID data into actionable insights — capacity forecasts, maintenance predictions, and compliance dashboards. The Data Center RFID Market is shifting toward recurring software revenue as a share of total spending.

By Tag Type

Segment Key Metric Primary Demand Driver
Passive 67% share Low unit cost; high-density suitability
Active CAGR 15.1% Real-time location for critical mobile assets


Passive RFID tags dominate the Data Center RFID Market on unit volume and revenue share, offering a cost-effective solution for static assets — racked servers, storage arrays, and networking equipment. Active tags command a premium but deliver continuous location updates, making them preferable for mobile assets such as portable storage carts, diagnostic equipment, and high-value GPU clusters that move between zones. The active segment is gaining share as edge and modular data centers require real-time visibility across distributed, often unmanned locations.

By Data Center Type

Segment Key Metric Primary Demand Driver
Colocation 41% share Multi-tenant audit and SLA compliance
Enterprise CAGR 12.9% In-house IT governance and refresh planning
Edge USD 0.38 Billion (2025) Distributed, unmanned site management


Colocation facilities represent the largest segment of the Data Center RFID Market because multi-tenant environments demand rigorous asset demarcation and auditability. Enterprise data centers are adopting RFID as CIOs seek to rationalize sprawling IT estates and enforce refresh schedules tied to warranty and performance benchmarks. Edge facilities, though smaller individually, are proliferating rapidly and collectively contributing meaningful volume to the Data Center RFID Market.

By Application

Segment Key Metric Primary Demand Driver
Asset Tracking and Inventory 48% share Core use case; compliance documentation
Workflow Automation CAGR 14.5% Hands-free check-in/check-out processes


Asset tracking and inventory management remains the primary application driving the Data Center RFID Market, underpinning compliance audits, insurance documentation, and financial asset registers. Workflow automation — encompassing automated receiving, provisioning, relocation, and decommissioning processes — is the faster-growing application as operators seek to reduce manual touchpoints and associated human error rates across the asset lifecycle.


Competitive Benchmarking

The Data Center RFID Market exhibits moderate concentration, with the top five vendors accounting for an estimated 35–42% of global revenue. The competitive structure blends large diversified technology conglomerates (Zebra Technologies, Honeywell) with pure-play RFID specialists (Impinj, RF Code) and tag/inlay manufacturers (Avery Dennison, Alien Technology). No single player exceeds a 12% share, and the market's middle tier is fragmented among regional integrators and niche software providers.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Zebra Technologies ~8–11% Fixed and handheld readers, asset visibility platform End-to-end hardware-software ecosystem
Impinj ~7–10% RAIN RFID chips, reader gateways, ItemSense software Silicon-to-cloud platform leader
Avery Dennison ~5–8% RFID inlays, Smartrac tag portfolio High-volume tag manufacturing scale
HID Global (ASSA ABLOY) ~5–7% RFID access and asset tags, LinTRAK platform Convergence of physical security and asset tracking
Honeywell ~4–7% Industrial RFID readers, workflow solutions Integration with building management systems
Alien Technology ~3–5% UHF RFID tags, Higgs IC platform Cost-competitive tag innovation
RF Code ~3–5% Active RFID sensors, CenterScape platform Environmental monitoring focus
Checkpoint Systems ~2–4% RFID labels, OATSystems middleware Retail-to-enterprise crossover
Asset Vue ~2–4% Data center–specific RFID asset management software Purpose-built for rack-level tracking
GAO RFID ~1–3% Readers, tags, turnkey deployment kits Emerging market distribution


Recent News & Developments

  • Zebra Technologies (September 2024): Launched the ATR7000 RFID reader designed for overhead ceiling-mount deployment in data center aisles, enabling continuous passive tag reads across entire hot-aisle/cold-aisle configurations [21].
  • Impinj (June 2024): Released the M800 RAIN RFID tag chip with enhanced sensitivity at –24 dBm, improving read reliability in metal-dense server rack environments [22].


Data Center RFID Market Report Scope

Parameter Detail
Market Scope Global Data Center RFID Market (Segments-Components, Tag type, Data center type, Application)
Study Period 2021–2035
CAGR 13.5% (2026–2035)
Base Year Market Size USD 2.50 Billion (2025)
Forecast Endpoint USD 8.88 Billion (2035)
Fastest Growing Segment Active tags (by tag type); Asia-Pacific (by region)
Companies Profiled 10 (see Section 10)
Valuation Currency USD Billion

FAQs

What is the typical payback period for deploying RFID in a mid-sized data center?
Most mid-sized deployments achieve payback within 14–22 months through reduced manual audit labor, lower asset ghost rates, and faster provisioning cycles [12]. Facilities with over 3,000 rack positions tend to reach breakeven faster due to scale efficiencies.
How does RFID compare to BLE-based asset tracking for data center environments?
RFID offers lower per-tag cost and no battery dependency for passive deployments, while BLE provides continuous telemetry at higher unit expense [14]. Most operators select passive RFID for static assets and reserve BLE for mobile equipment requiring constant location updates.
Can RFID tags withstand the thermal conditions inside server racks?
Commercial data center RFID tags are rated for operating temperatures between –20°C and +85°C, comfortably covering standard rack exhaust temperatures [22]. Specialized high-temperature inlays extend this range for hot-aisle containment zones.
What role does RFID play in meeting SOC 2 audit requirements?
RFID provides automated, timestamped evidence of asset location and movement, directly supporting SOC 2 physical security controls [4]. Auditors increasingly accept RFID-generated logs as primary documentation.
Are there data center–specific RFID standards that operators should follow?
No single universal standard exists, but GS1's EPC Tag Data Standard and the RAIN RFID Alliance specifications are widely adopted benchmarks [13]. Operators should verify middleware compatibility with these frameworks before procurement.
How do operators handle RFID tag recycling during hardware refresh cycles?
Most passive tags are single-use and disposed of with decommissioned hardware, costing under USD 0.05 per unit [5]. Active tags with reusable housings are typically reclaimed, re-encoded, and redeployed during refresh events.
What integration challenges arise when layering RFID onto legacy DCIM platforms?
Primary friction points include API incompatibility, inconsistent asset naming conventions, and middleware latency during bulk read events [13]. Operators typically resolve these through a phased rollout starting with a single facility before enterprise-wide deployment.    
Author
Author Author Profile Apoorva Priyadarshi LinkedIn Research Analyst
With 4+ years of experience in Market Intelligence and Strategic Research, Apoorv specializes in ICT, Semiconductor, and BFSI markets. Combining strong analytical capabilities with a deep understanding of technology-driven industries, he focuses on delivering data-driven insights that support strategic decision-making. With a background in technology and business research, Apoorv has contributed to numerous global market studies, competitive landscape analyses, and opportunity assessments across sectors such as semiconductors, digital banking, cybersecurity, and telecommunications.
Co-Author Co-Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry standards, peer-reviewed technology journals, IoT publications, and authoritative technology organizations. Key sources included the International Organization for Standardization (ISO) for RFID standards (ISO/IEC 18000 series), EPCglobal (GS1), Federal Communications Commission (FCC) for spectrum allocation, European Telecommunications Standards Institute (ETSI), Institute of Electrical and Electronics Engineers (IEEE) for RFID protocols, National Institute of Standards and Technology (NIST) for cybersecurity frameworks, Uptime Institute for data center tier classifications, International Data Corporation (IDC) for IT infrastructure forecasts, Gartner Research for enterprise technology adoption, CB Insights for venture capital and startup tracking, European Union Agency for Cybersecurity (ENISA), U.S. General Services Administration (GSA) for federal procurement data, U.S. Census Bureau for technology sector economic indicators, OECD Digital Economy Outlook, World Economic Forum (WEF) Digital Transformation reports, and national communications regulatory authorities from key markets.

These sources were employed to compile data center infrastructure statistics, RFID deployment metrics, regulatory compliance requirements, technology adoption trends, and competitive landscape analysis for passive RFID systems, active RFID systems, semi-passive RFID technologies, and integrated software platforms.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources comprised CEOs, CTOs, VPs of Product Development, leaders of IoT solutions, and commercial directors from RFID hardware manufacturers, software developers, systems integrators, and data center infrastructure providers. Chief information officers (CIOs), data center facility managers, IT operations directors, network engineers, and procurement leads from hyperscale data centers, colocation facilities, enterprise data centers, and cloud service providers constituted demand-side sources. Primary research verified market segmentation across components (tags, readers, antennas, software), confirmed product development roadmaps, and collected insights on deployment patterns, integration challenges, total cost of ownership models, and ROI metrics for RFID implementations.

Primary Respondent Breakdown:

By Designation: C-level Executives (42%), Director Level (25%), Others (33%)

By Region: North America (40%), Europe (25%), Asia-Pacific (28%), Rest of World (7%)


Market Size Estimation

Revenue mapping and deployment volume analysis were implemented to determine global market valuation. The methodology comprised the following:

Identification of over 40 significant RFID technology providers and data center solution vendors in North America, Europe, Asia-Pacific, and Latin America

Product mapping encompasses readers, antennas, active RFID systems, semi-passive RFID solutions, and management software platforms.

Analysis of annual revenues that are specific to data center RFID portfolios, as reported and modeled

Coverage of manufacturers and solution providers that account for 72-78% of the global market share in 2024

Segment-specific valuations for asset tracking, inventory management, access control, and environmental monitoring applications are derived through extrapolation using bottom-up (deployment volume × ASP by country/region) and top-down (vendor revenue validation) approaches.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















