Custom Software Development Market (2026 – 2035)

Custom Software Development Market Size, Share and Research Report By Solution (Web-Based Solutions, Mobile Applications, Enterprise Software, Embedded and IoT Software, Analytics and AI Software), By Deployment Model (On-Premise, Cloud-Hosted), By Enterprise Size (Small and Medium Enterprises, Large Enterprises), By End-User Vertical (BFSI, Healthcare and Life Sciences, Retail and E-Commerce, Manufacturing, IT and Telecom, Government and Public Sector, Others) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
ID: MRFR/ICT/10399-HCR 128 Pages Ankit Gupta Last Updated: September 15, 2026
Custom Software Development Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)17.0%
2025 Market SizeUSD 40.83 Billion
2035 Market SizeUSD 197.75 Billion
Key Players
Accenture
Tata Consultancy Services
Infosys
Cognizant
Capgemini
Wipro
Opportunities
  • Regulated-Vertical Accelerators
  • Emerging-Market Digital Public Infrastructure
  • Data Monetisation and Outcome-Linked Contracting

Custom Software Development Market Summary

The Custom Software Development Market closed 2025 at USD 40.83 Billion and enters the forecast window at USD 48.14 Billion in 2026, on track to reach USD 197.75 Billion by 2035 at a 17.0% CAGR. Two catalysts anchor this trajectory. The first is regulatory: United States Executive Order 14028 and the follow-on CISA attestation regime made software bills of materials a procurement condition, pushing regulated buyers toward code they can audit line by line [1][5]. The second is fiscal — India's IT services export base crossed USD 200 billion in FY2025, giving global buyers deep, price-competitive engineering capacity [13].

When it comes to differentiation, packaged enterprise suites are losing momentum. Buyers are replacing monolithic ERP extensions, custom-coded COBOL claims engines, and vendor-locked middleware with containerized microservices and event-driven integration layers. In 2026, it is anticipated that enterprises will spend more than USD 1.28 trillion on software, with a growing portion of this expenditure allocated to bespoke development rather than license renewal . It is precisely this transition that the Custom Software Development Market captures.

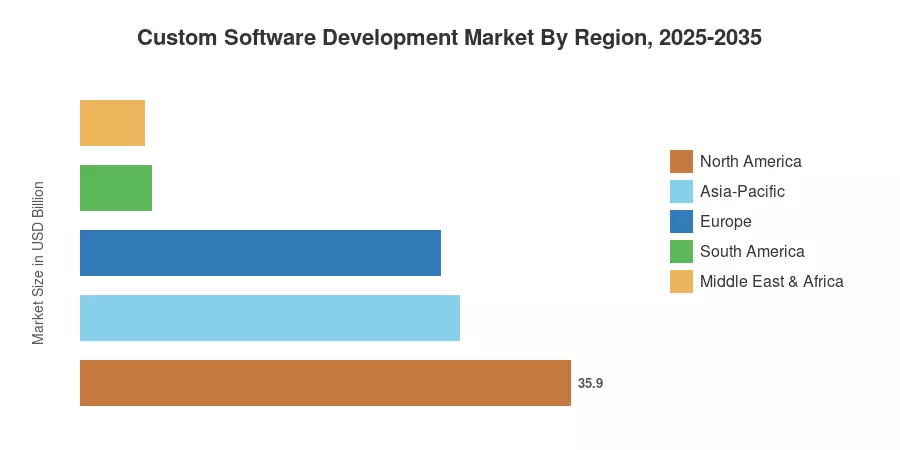
North America accounts for 35.9% of 2025 revenue, which is bolstered by the densest concentration of digital-native buyers and regulated-industry compliance spend. Asia-Pacific is expected to experience the most rapid growth, with a compound annual growth rate (CAGR) of 19.4% through 2035. Europe, which is in second place at 26.4%, is being driven by the implementation of the Data Act and the DORA financial-resilience deadlines [9][10]. Vendors that are capable of combining AI-accelerated delivery economics with regulated-domain depth will benefit from momentum throughout the decade.

Key Report Takeaways

• By Solution

  • Enterprise software led the Custom Software Development Market with 34.1% revenue share in 2025
  • Embedded and IoT software is set to advance at a 20.8% CAGR through 2035
  • Web-based solutions generated USD 9.39 billion in 2025 revenue

• By End-user

  • BFSI commanded 22.0% of 2025 revenue, the largest single vertical
  • Healthcare and life sciences is forecast to expand at an 18.6% CAGR to 2035
  • Cloud-hosted deployment captured 57.1% of Custom Software Development Market share in 2025

• By Region

  • North America accounted for 35.9% of 2025 revenue in the Custom Software Development Market.
  • Asia-Pacific is expected to post the fastest regional CAGR at 19.4%
  • Europe generated USD 10.78 billion in 2025


Market Size and Forecast (2021–2035)

Estimates blend vendor-reported services revenue, national IT-export statistics from India's MeitY and Ireland's CSO, procurement disclosures from regulated buyers, and a bottom-up build of billable engineering capacity by delivery geography [13][21]. Historical years are reconciled against audited annual reports; forecast years apply segment-weighted growth rather than a flat blended rate. The Custom Software Development Market is expressed in USD Billion throughout.
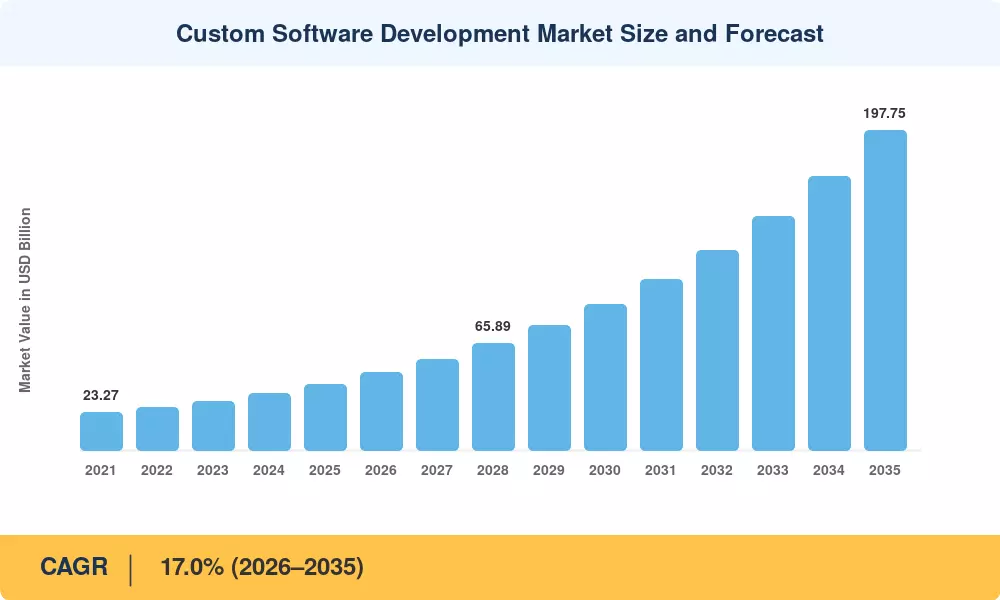
Custom Software Development Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Generative-AI coding assistants compressing delivery cycles +3.1 pp Global Short-term (≤2 yr)
Cloud-native re-platforming of core enterprise systems +2.9 pp Global Medium-term (2–4 yr)
Software supply-chain security mandates +2.4 pp North America, Europe Short-term (≤2 yr)
Regulated-industry compliance divergence +2.2 pp Europe, Americas Medium-term (2–4 yr)
Edge and IoT workload proliferation +1.8 pp Asia-Pacific, Europe Long-term (≥4 yr)
Sovereign digital-infrastructure programmes +1.6 pp Asia-Pacific, MEA Long-term (≥4 yr)
Composable, API-led integration architectures +1.4 pp Global Medium-term (2–4 yr)


AI-Accelerated Delivery Economics

Coding assistants changed the unit economics of bespoke build before they changed anything else. GitHub's Octoverse data shows more than 1.1 billion contributions across AI-assisted repositories in 2024, and controlled studies report 26–55% task-completion gains on scoped development work [8]. That collapses the cost gap between configuring a packaged suite and commissioning a purpose-built one, which is why the Custom Software Development Market is absorbing budget that previously defaulted to licence renewals.

Supply-Chain Security as a Procurement Gate

Federal buyers now require attested provenance. Producers who sell to US agencies are required by CISA's secure-software certification form, which went into effect in June 2024, to record build environments and dependency trees [5]. Bids are completely lost by vendors that lack that discipline. Large private purchasers downstream successfully taxed opaque third-party code by copying the clause into their own master service agreements.


Compliance Divergence in Regulated Verticals

There is no longer a convergence of rules. Brazil's LGPD enforcement proceedings are expedited till 2024, DORA requires ICT third-party risk registers on almost 22,000 European financial companies, and HIPAA's proposed security regulation update adds required asset inventories [9][10][20]. Programs for re-engineering and modernizing historical systems are scoped as bespoke builds since each divergence produces jurisdiction-specific logic that packaged software cannot afford to carry.


Core Systems Re-Platforming

Banks and insurers are working through decades of accumulated technical debt. The European Central Bank flagged legacy core dependency as a supervisory concern in 2024, and several tier-one institutions disclosed multi-year modernisation budgets exceeding USD 500 million each [9][22]. These are not lift-and-shift jobs; they require re-expressing business rules in maintainable code.


Restraints Impact Analysis

Restraint weightings follow the same directional convention as Section 4. Values indicate drag on growth rather than subtractable CAGR components.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Senior engineering talent scarcity and wage inflation −2.3 pp Global Medium-term (2–4 yr)
Total-cost-of-ownership scrutiny versus packaged SaaS −1.7 pp North America, Europe Short-term (≤2 yr)
Data-residency and cross-border transfer restrictions −1.4 pp Europe, Asia-Pacific Medium-term (2–4 yr)
Project overrun and delivery-failure risk −1.2 pp Global Short-term (≤2 yr)
AI-generated code provenance and IP liability −0.9 pp Global Long-term (≥4 yr)


The Senior Talent Bottleneck

Junior capacity is abundant; architects are not. United States Bureau of Labor Statistics projections show software developer employment growing 17% through 2033, far above the all-occupation average, yet vacancy durations for principal-level roles stretched past 60 days in 2024 [17]. Wage inflation of 8–12% in specialist domains — payments, medical device firmware, real-time telemetry — compresses vendor margins and slows programme starts.

Build-Versus-Buy Scrutiny

Finance functions have grown sceptical. When a packaged platform covers 80% of requirements, boards increasingly demand justification for the remaining 20%, and a 2024 technology cost survey found IT budget owners under explicit pressure to reduce bespoke maintenance obligations . Projects that cannot demonstrate defensible competitive advantage are deferred.

Data Localisation Friction

Sovereignty rules fragment delivery models. The EU Data Act, applicable from September 2025, adds switching and portability obligations, while India's DPDP Act and Saudi PDPL impose residency conditions that complicate distributed engineering [10][16]. Vendors respond by standing up in-country delivery centres — effective, but capital-intensive and slow.


Custom Software Development Market Opportunities

Regulated-Vertical Accelerators

Pre-built compliance scaffolding — audit logging, consent capture, retention policy engines — turns repeatable regulatory work into productised assets. Vendors packaging these for BFSI and healthcare buyers shorten time-to-value while preserving custom-build margins.

Emerging-Market Digital Public Infrastructure

Governments across Africa, Southeast Asia and Latin America are commissioning identity, payments and health registry stacks. The World Bank's ID4D programme has supported implementations in more than 45 countries, and these engagements rarely suit packaged software [21]. For the Custom Software Development Market, sovereign programmes represent durable, multi-year demand insulated from private-sector budget cycles.

Data Monetisation and Outcome-Linked Contracting

Buyers increasingly want revenue participation rather than fixed deliverables. Vendors that build telemetry-rich platforms can negotiate per-transaction or per-outcome pricing, converting one-off projects into annuity streams. Manufacturing and logistics clients have proved most receptive.

Edge and Embedded Workloads

Industrial operators are pushing inference to the plant floor. IEA analysis of data centre and network electricity demand highlights the efficiency case for local processing, and embedded software carries higher realisation rates than commodity web work [11].

Modernisation of Mid-Market Estates

Mid-sized firms carry proportionally more technical debt than large enterprises but lack in-house capability. Fixed-scope modernisation offerings priced under USD 500,000 open a segment historically served by staff augmentation.


Custom Software Development Market Future Outlook

Autonomous Delivery Pipelines

Agentic tooling will move beyond code completion into test generation, dependency remediation and release orchestration. By the early 2030s, expect substantial portions of maintenance work to run with human review rather than human authorship. The Custom Software Development Market will reprice accordingly — output-based commercial models replacing time-and-materials for commoditised layers, while architecture and domain modelling command premium rates.

Platform Economics and Reusable Assets

Vendors are converting delivery experience into licensable accelerators. This shifts gross margins from the mid-30s toward the mid-40s for firms that industrialise successfully, and it changes competitive dynamics: scale advantages accrue to whoever amortises assets across the most engagements, not whoever holds the largest bench.

Energy-Aware and Sustainable Engineering

Compute intensity is becoming a design constraint. IEA analysis projects data centre electricity demand rising sharply through 2030, and corporate sustainability reporting under CSRD now pulls IT emissions into audited disclosures [11][10]. Efficient code is starting to carry measurable balance-sheet value.

Sovereign Technology Stacks

Fragmentation will deepen. More jurisdictions will mandate domestic hosting, domestic key management and in-country source escrow, which raises delivery costs but expands total addressable spend as buyers duplicate capability across regions rather than centralising it.


Regional Market Share Analysis

Region Share of 2025 Revenue (%) Primary Investment Themes
North America 35.9 Supply-chain security attestation, core banking modernisation
Asia-Pacific 27.8 Delivery capacity expansion, digital public infrastructure
Europe 26.4 DORA resilience, Data Act portability
South America 5.2 Fintech platforms, LGPD compliance
Middle East & Africa 4.7 Sovereign cloud, national vision programmes
Total 100.0 —

Regional distribution in the Custom Software Development Market reflects where regulated spend and engineering supply intersect.


North America

Country Metric Key Driver
US 82.4% share of region Federal attestation regime and BFSI core replacement [5]
Canada USD 1.69 Billion (2025) Open banking framework build-out [22]
Mexico 16.8% CAGR (2026–2035) Nearshore delivery hubs serving US buyers


Federal procurement set the tone for the entire region. Once agencies required attested build pipelines, prime contractors cascaded the requirement through their supply base, and remediation work reached buyers who had never previously inventoried their dependencies [5]. Canadian demand runs narrower but deeper, concentrated in financial services where open banking timelines forced API exposure of systems designed for batch settlement.

Europe

Country Metric Key Driver
Germany 23.1% share of region Industrial software and Industrie 4.0 platforms [11]
UK USD 2.42 Billion (2025) Financial services and public sector transformation [22]
France 14.6% share of region Sovereign cloud certification requirements [10]
Italy 8.9% share of region PNRR digitalisation funding [10]
Spain 7.8% share of region Digital Spain 2026 agenda [10]
Nordic Countries 17.4% CAGR (2026–2035) Healthcare data platforms [20]
Russia USD 0.44 Billion (2025) Import-substitution software mandates
Rest of Europe 9.6% share of region Cross-border payments integration [9]


Regulatory sequencing drives European volumes. DORA's third-party risk provisions forced financial entities to map every ICT dependency, and the mapping exercise itself surfaced hundreds of undocumented integrations requiring rebuild [9]. Germany's demand profile differs — it is industrial, tied to machine data and shop-floor systems rather than compliance.

Asia-Pacific

Country Metric Key Driver
China 28.6% share of region Domestic platform localisation
India 21.9% CAGR (2026–2035) Export delivery capacity and DPDP compliance [13]
Japan 18.7% share of region 2025 legacy systems cliff remediation [14]
South Korea 9.4% share of region Smart factory and semiconductor tooling software [14]
ASEAN USD 1.58 Billion (2025) Digital payments and e-government platforms [21]
Rest of Asia-Pacific 6.2% share of region Cloud-first government policies [16]


Japan's situation deserves attention. METI's long-flagged systems cliff — the concentration of mainframe applications maintained by a retiring engineer cohort — became operationally urgent in 2025, and remediation budgets moved from study phase to build phase [14]. India, meanwhile, supplies the labour that much of the Custom Software Development Market consumes, while simultaneously becoming a substantial domestic buyer.

South America

Country Metric Key Driver
Brazil 61.3% share of region Pix ecosystem and open finance mandates [20]
Argentina USD 0.34 Billion (2025) Export-oriented engineering services
Rest of South America 22.7% share of region Public sector digitalisation programmes [21]


Brazilian instant payments reshaped local demand. Pix processed record transaction volumes through 2024, and every participating institution needed reconciliation, fraud-scoring and dispute-handling logic that no vendor sold off the shelf [20]. Argentina's contribution is more supply-side, with dollar-denominated engineering contracts absorbing capacity that domestic buyers cannot fund.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 34.8% share of region Vision 2030 giga-project systems [16]
UAE 26.1% share of region Government service digitalisation [16]
South Africa 15.3% share of region Banking modernisation and fintech [21]
Egypt 20.4% CAGR (2026–2035) Offshore delivery centre expansion [21]
Rest of MEA 12.6% share of region Telecom OSS/BSS replacement


Gulf demand is programme-driven rather than cyclical. Saudi authorities have tied technology procurement to local content thresholds, obliging international vendors to establish in-kingdom delivery and transfer capability [16]. Egypt is emerging as a cost-competitive delivery base for European buyers seeking time-zone alignment.


Custom Software Development Market By Region, 2025-2035

Custom Software Development Market Segmentation

Segment structure in the Custom Software Development Market follows solution type, deployment model, enterprise size and end-user vertical.

By Solution

Segment Metric Primary Demand Driver
Enterprise Software 34.1% share (2025) Core system replacement and ERP extension
Web-Based Solutions USD 9.39 Billion (2025) Customer-facing portals and commerce
Mobile Applications 16.4% CAGR (2026–2035) Field workforce and consumer engagement
Embedded and IoT Software 20.8% CAGR (2026–2035) Industrial telemetry and device firmware
Analytics and AI Software USD 5.31 Billion (2025) Decision automation and model deployment


Enterprise software retains leadership within the Custom Software Development Market because the work is structurally non-substitutable — business rules encoding decades of pricing, underwriting or entitlement logic cannot be configured into a packaged product without unacceptable compromise. Embedded and IoT software grows fastest from a smaller base, pulled by manufacturers instrumenting equipment they previously sold as passive hardware.

By Deployment Model

Segment Metric Primary Demand Driver
Cloud-Hosted 57.1% share (2025) Elastic scaling and managed service economics
On-Premise 19.6% CAGR (2026–2035) Data residency and latency-sensitive workloads


Cloud dominance in the Custom Software Development Market is settled, but on-premise is not disappearing — it is being redefined. Sovereign and edge deployments now use the same container tooling as public cloud, so the architectural gap has narrowed even as the hosting decision has become more politically loaded.

By Enterprise Size

Segment Metric Primary Demand Driver
Large Enterprises 53.3% share (2025) Multi-year modernisation programmes
Small and Medium Enterprises 18.7% CAGR (2026–2035) Affordable modernisation via fixed-scope offerings


Large enterprises anchor the Custom Software Development Market through programme scale, but SME growth is the more interesting story. AI-assisted delivery lowered the minimum viable project size, bringing bespoke build within reach of firms that previously had to accept whatever a packaged vendor offered.

By End-User Vertical

Segment Metric Primary Demand Driver
BFSI 22.0% share (2025) Regulatory reporting and payments modernisation
Healthcare and Life Sciences 18.6% CAGR (2026–2035) Interoperability mandates and clinical data platforms
Retail and E-Commerce USD 5.72 Billion (2025) Omnichannel fulfilment orchestration
Manufacturing 14.9% share (2025) Industrial IoT and supply-chain visibility
IT and Telecom USD 4.90 Billion (2025) Network automation and OSS/BSS replacement
Government and Public Sector 11.3% share (2025) Citizen service digitalisation
Others USD 2.86 Billion (2025) Energy, logistics and education platforms


BFSI's lead in the Custom Software Development Market rests on regulatory density rather than budget size alone. Healthcare's acceleration traces to interoperability enforcement — information-blocking penalties and standardised exchange requirements created integration work that vendors had deferred for years [20].


Competitive Benchmarking

Concentration in the Custom Software Development Market is moderate. Estimated HHI sits near 340, with the top five providers holding roughly 25–31% of global revenue — high enough that scale matters in large programme bids, low enough that thousands of specialist boutiques compete profitably in vertical niches. Differentiation increasingly rests on domain depth and delivery-asset reuse rather than headcount.

Company Est. Revenue Share Range Key Offerings for Custom Software Development Market Strategic Positioning
Accenture ~7–9% Full-lifecycle build, industry platforms, cloud migration Scale leader with deep consulting-led entry
Tata Consultancy Services ~5–7% Core banking modernisation, contextual knowledge model Long-tenure client relationships in BFSI
Infosys ~4–6% Cobalt cloud services, AI-assisted engineering Platform-plus-services hybrid model
Cognizant ~3.5–5% Healthcare and BFSI application development Vertical specialisation in regulated sectors
Capgemini ~3–4.5% Intelligent industry, embedded software engineering Strong European public and industrial base
Wipro ~2.5–4% Application modernisation, cybersecurity-embedded delivery Consulting-integrated engineering
EPAM Systems ~2.5–4% Product engineering, complex platform builds Premium-rate positioning, high-end technical work
HCLTech ~2–3.5% Engineering R&D, embedded and IoT software Product engineering heritage
Globant ~1.5–2.5% Digital product studios, AI pods Design-led delivery for consumer brands
Endava ~1–2% Payments, fintech platform engineering Nearshore Europe and Latin America focus
Thoughtworks ~0.8–1.5% Continuous delivery, legacy modernisation Engineering culture and methodology authority


Recent News & Developments

  • CISA (June 2024): Secure software attestation form became binding for critical federal software, requiring producers to certify build-environment controls — a durable procurement gate for the Custom Software Development Market [5]
  • European Supervisory Authorities (January 2025): DORA obligations took effect across roughly 22,000 financial entities, triggering ICT third-party register builds and remediation contracts [9]
  • Accenture (September 2024): Expanded generative-AI workforce commitment and closed multiple engineering acquisitions to deepen data and AI delivery capacity [22]
  • EPAM Systems (2024): Acquired regional engineering firms to broaden nearshore delivery footprint in Latin America and Central Europe [22]
  • Government of India (2024): Digital Personal Data Protection Act rules progressed toward operationalisation, prompting consent-architecture rebuilds across domestic platforms [13]
  • European Commission (September 2025): Data Act became applicable, imposing cloud-switching and portability obligations that force API-first custom software architecture into vendor roadmaps [10]
  • Capgemini (2025): Announced expanded intelligent-industry engineering investment targeting embedded and edge software demand in European manufacturing [22]
  • Saudi Arabia (2024–2025): Digital Government Authority tightened local-content and in-kingdom delivery requirements for public technology procurement [16]


Custom Software Development Market Report Scope

Parameter Detail
Market Scope Global custom and bespoke software design, build, integration and modernisation services across solution, deployment, enterprise size and end-user vertical
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 17.0% (2026–2035)
Market Size Checkpoints 2025: USD 40.83 Billion; 2026: USD 48.14 Billion; 2031: USD 105.53 Billion; 2035: USD 197.75 Billion
Fastest Growing Segments Embedded and IoT software (solution); healthcare and life sciences (vertical); Asia-Pacific (geography)
Companies Profiled Accenture, TCS, Infosys, Cognizant, Capgemini, Wipro, EPAM Systems, HCLTech, Globant, Endava, Thoughtworks
Valuation Currency USD Billion

FAQs

What contracting model works best for a first engagement in the Custom Software Development Market?
Start with a paid discovery sprint priced separately from delivery. It surfaces requirement risk before either side commits to a fixed-price envelope, and it gives you a real sample of the vendor's engineering quality [18].
Who owns the intellectual property when AI tools generate part of the codebase?
Ownership depends on your contract, not the tool. Insist on assignment clauses covering AI-assisted output, plus vendor warranties on training-data provenance and third-party licence compliance [12][24].
How should buyers evaluate offshore versus nearshore delivery in the Custom Software Development Market?
Compare total landed cost, not hourly rates. Time-zone overlap of four or more hours typically cuts rework enough to offset a 20–30% rate premium on complex, iterative work .
What protects a buyer if the development vendor fails or is acquired?
Source code escrow with periodic verified deposits, documented build instructions, and contractual access to the CI/CD configuration. Test the restore process annually rather than assuming it works [24].
How do procurement teams verify security claims in the Custom Software Development Market?
Request a software bill of materials for every release plus evidence of build-environment controls. Attestation forms are now standard for regulated buyers and increasingly expected commercially [5].
When does staff augmentation beat a managed delivery team?
Augmentation suits stable roadmaps where you own architecture and accountability. Managed teams make sense when outcomes matter more than headcount control and you lack senior technical leadership internally [17].
What integration challenge derails custom builds most often?
Undocumented behaviour in legacy interfaces. Budget explicit discovery time for reverse-engineering existing integrations — teams that skip it routinely lose entire sprints to surprises [14][18].    
Author
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry associations, peer-reviewed technology journals, and authoritative government IT organizations. Key sources included the US Bureau of Labor Statistics (BLS), National Institute of Standards and Technology (NIST), US Census Bureau Business & Industry Data, International Telecommunication Union (ITU), European Commission Digital Economy and Society Index (DESI), Organization for Economic Co-operation and Development (OECD) Digital Economy Outlook, International Data Corporation (MRFR), MRFR Research, IEEE Xplore Digital Library, ACM Digital Library, World Economic Forum (WEF) Global Information Technology Report, UNCTAD Digital Economy Report, and national digital transformation strategies from key markets including USA (NITRD Program), UK (DCMS Digital Strategy), Germany (Digital Hub Initiative), India (MeitY Digital India), and Singapore (IMDA Smart Nation). These sources were used to collect industry statistics, technology adoption metrics, software export data, regulatory frameworks, and market landscape analysis for consulting services, development services, maintenance support services, integration services, cloud-based deployments, and on-premises solutions.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consisted of CEOs, CTOs, VPs of Engineering, product development chiefs, and practice leaders from custom software development companies, system integrators, and IT consulting firms. The demand-side sources included Chief Information Officers (CIOs), IT Directors, procurement heads, and digital transformation leads from large enterprises, small and medium enterprises (SMEs), healthcare institutions, banking and financial services organizations, retail chains, and manufacturing firms in North America, Europe, Asia-Pacific, South America, the Middle East, and Africa. Market segmentation was verified, product pipeline timelines were confirmed, and insights regarding technology adoption patterns, pricing strategies, cloud migration trends, and cybersecurity investment priorities were gathered through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (32%), Others (40%)

By Region: North America (38%), Europe (25%), Asia-Pacific (28%), South America (4%), Middle East & Africa (5%)

By Industry Vertical: Banking Financial Services (22%), Healthcare (18%), Retail (15%), Manufacturing (14%), Others (31%)

By End User: Large Enterprises (45%), Small and Medium Enterprises (55%)


Market Size Estimation

Global market valuation was derived through revenue mapping and project volume analysis. The methodology included:

Identification of 55+ key service providers across North America, Europe, Asia-Pacific, South America, and Middle East & Africa

Service mapping across consulting services, development services, maintenance support services, and integration services

Deployment mapping across on-premises and cloud-based solutions

Analysis of reported and modeled annual revenues specific to custom software development portfolios

Coverage of service providers representing 65-70% of global market share in 2024

Extrapolation using bottom-up (project volume × ASP by country/region) and top-down (service provider revenue validation) approaches to derive segment-specific valuations across service types, deployment models, industry verticals (healthcare, BFSI, retail, manufacturing), and end-user segments (large enterprises, SMEs)

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Global Diameter Signaling Market
Case Study
Information and Communications Technology
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















