Corn Oil Market (2026 - 2035)

Corn Oil Market Size, Share, Industry Trend & Analysis Research Report Information By Product Grade (Refined Corn Oil, Unrefined and Virgin Corn Oil, Blended Corn Oil), By End User (Industrial, Household/Retail Consumers, Horeca), By Region (North America, Europe, Asia-Pacific, South America, Middle East and Africa) – Forecast Till 2035
ID: MRFR/FnB/10387-HCR 128 Pages Snehal Singh Last Updated: October 01, 2026
Corn Oil Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.37%
2025 Market SizeUSD 5.88 Billion
2035 Market SizeUSD 10.90 Billion
Key Players
Cargill
Incorporated
Bunge Global SA
Wilmar International Limited
Ingredion Incorporated
Associated British Foods plc
Opportunities
  • Non-GMO and Organic Premium Retail
  • Carbon-Intensity Data as a Revenue Stream
  • Emerging-Market Retail Expansion

Corn Oil Market Summary

The global Corn Oil Market was valued at USD 5.88 Billion in 2025 and is projected to reach USD 6.25 Billion in 2026, climbing to USD 10.90 Billion by 2035 at a CAGR of 6.37% over 2026–2035. Two policy levers anchor that trajectory. The U.S. Renewable Fuel Standard set biomass-based diesel volumes at 3.35 billion gallons for 2025 [5], and the Section 45Z Clean Fuel Production Credit, effective January 2025, rewards low-carbon feedstocks such as distillers corn oil [7]. Food demand provides a steadier base beneath these fuel-driven swings.

Processing practices are shifting as quickly as demand. Partially hydrogenated oils, once the default frying medium in packaged foods and quick-service kitchens, are giving way to fully refined and blended formulations after the World Health Organization reported that 43 countries, covering 2.8 billion people, had adopted best-practice trans-fat policies [11]. On the supply side, U.S. dry-mill ethanol plants have invested heavily in extraction retrofits, turning a low-value stillage stream into a feedstock contested by food refiners and renewable diesel producers [10].

North America leads the Corn Oil Market with a 38.4% share, backed by the world's largest corn processing and ethanol base. Asia-Pacific is the fastest-growing region at a 7.9% CAGR and ranks second by value, lifted by China's wet-milling capacity and rapid foodservice expansion across India and Southeast Asia. Europe follows, anchored by retail demand and certified biofuel imports. Over the next decade, the balance between fuel and food outlets will decide where incremental volumes flow and how processors price them.

Key Report Takeaways

• By Product Grade

  • Refined Corn Oil holds a 66.5% share of the Corn Oil Market in 2025, reflecting its neutral flavor, high smoke point, and suitability for industrial frying and retail bottling
  • Blended Corn Oil is the fastest-growing product grade, expanding at a 7.55% CAGR through 2035 as processors engineer fatty-acid profiles for fry life and cost
  • Unrefined and Virgin Corn Oil generated USD 0.73 Billion in 2025, serving premium, nutrient-focused retail niches

• By End User

  • Industrial buyers account for a 51.6% share of the Corn Oil Market, spanning renewable diesel, biodiesel, animal feed, and processed foods
  • Horeca is the fastest-growing end user at an 8.40% CAGR, led by quick-service restaurant reformulation
  • Household/Retail Consumers represented USD 1.77 Billion in 2025, supported by value-priced bottled formats

• By Region

  • North America leads with a 38.4% share, driven by U.S. ethanol coproduct recovery
  • Asia-Pacific posts the fastest growth at a 7.9% CAGR
  • Europe reached USD 1.15 Billion in 2025

Corn Oil Market Size and Forecast (2021–2035)

Market Research Future built the historical series from production, crush, and trade data published by the USDA Economic Research Service and Foreign Agricultural Service [1][2], cross-checked against segment disclosures in leading processors' annual reports [17][18][19]. Forecast values combine volume projections for food, feed, and fuel outlets with price assumptions aligned to the OECD-FAO Agricultural Outlook [13]. The 2022 jump reflects the commodity price spike that followed Black Sea supply disruptions rather than a volume surge [12]; growth slowed in 2023 as prices normalized.
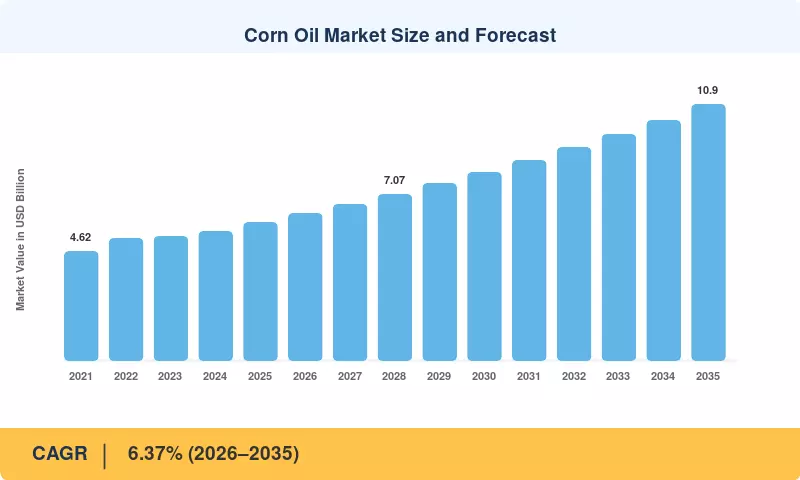
Corn Oil Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Renewable diesel and SAF feedstock demand +1.4% North America, Europe Long-term (≥4 yr)
RFS volumes and 45Z tax credit +1.1% United States Medium-term (2–4 yr)
Dry-mill ethanol oil extraction +0.8% United States, Brazil Medium-term (2–4 yr)
Trans-fat elimination mandates +0.9% Global Short-term (≤2 yr)
Asia-Pacific foodservice growth +1.0% Asia-Pacific, MEA Long-term (≥4 yr)
Heart-health label positioning +0.4% North America Short-term (≤2 yr)
Brazil corn ethanol expansion +0.6% South America Medium-term (2–4 yr)


Renewable Diesel and SAF Feedstock Demand

More quickly than any other trend, the market for corn oil was transformed by renewable fuel. According to the U.S. Energy Information Administration, renewable diesel capacity surpassed biodiesel for the first time in early 2023, reaching around 3.0 billion gallons annually [3]. Refiners pay more for distiller corn oil since it has one of the lowest carbon-intensity scores among lipid feedstocks. The demand is extended well into the 2030s by sustainable aviation fuel projects constructed along the same hydroprocessing path.


RFS Volumes and the 45Z Tax Credit

Firm demand is created from feedstock interest through federal mandates. For 2023, 2024, and 2025, the EPA's Set 1 rule set biomass-based diesel volumes at 2.82, 3.04, and 3.35 billion gallons [5]. Low-score inputs are immediately rewarded by the 45Z credit, which is worth up to USD 1.00 per gallon for road fuel and USD 1.75 for aviation fuel at the lowest carbon intensity [7]. For both incentives, corn oil is at the front of the line.


Dry-Mill Ethanol Oil Extraction

Nearly every U.S. dry-mill ethanol plant now recovers corn oil from thin stillage, according to the Renewable Fuels Association [10]. Output per bushel has climbed as plants add centrifuge and chemical aid upgrades, lifting yields toward 1 pound per bushel at leading facilities. That extraction stream gives ethanol producers a margin buffer when ethanol spreads compress. It also keeps supply growing without requiring new corn acreage.

Trans-Fat Elimination Mandates

Regulation is pushing food manufacturers away from partially hydrogenated fats. WHO's 2023 progress report counted 43 countries with best-practice trans-fat policies [11], and India's FSSAI capped industrial trans fat at 2% of total fat from January 2022 [14]. Reformulating bakery, snack, and frying applications favors refined and blended corn oils with neutral flavor and high smoke points. Cargill's removal of industrially produced trans fats from its global oils portfolio reinforced the shift [15].

Asia-Pacific Foodservice Growth

Restaurant expansion across Asia is lifting frying-oil consumption. China's catering revenue reached about CNY 5.57 trillion in 2024, according to the National Bureau of Statistics [25]. Quick-service chains entering tier-two and tier-three cities standardize on refined or blended oils with predictable fry life. India and Southeast Asia add similar demand as organized foodservice captures share from street vendors.

Heart-Health Label Positioning

The U.S. Food and Drug Administration permits a qualified health claim that consuming about 1 tablespoon (16 grams) of corn oil daily may reduce coronary heart disease risk when it replaces saturated fat [23]. Brand owners use the claim on retail packaging to differentiate against lower-priced alternatives. The effect is modest but durable, supporting shelf placement and price realization in North American grocery channels.

Brazil Corn Ethanol Expansion

Brazil's corn ethanol industry has grown from a marginal player to more than one-fifth of national ethanol output, according to the USDA Foreign Agricultural Service [24]. New plants in Mato Grosso and Goiás increasingly install oil-recovery systems modeled on U.S. dry mills. That adds a fresh supply source in South America and gives regional biodiesel producers a lower-carbon feedstock option alongside soy.

Restraints Impact Analysis


Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Corn and competing oil price volatility −0.9% Global Short-term (≤2 yr)
Food-versus-fuel supply competition −0.7% North America Medium-term (2–4 yr)
Omega-6 health perception −0.4% North America, Europe Long-term (≥4 yr)
GMO perception and non-GMO sourcing costs −0.5% Europe, Asia-Pacific Medium-term (2–4 yr)
Biofuel policy uncertainty −0.6% United States Short-term (≤2 yr)


Corn and Competing Oil Price Volatility

Because corn oil prices follow benchmarks for maize, diesel, and soybean oil, buyers are subject to uncontrollable fluctuations. The FAO oils sub-index fell precipitously through 2023 after reaching a record in March 2022 [12]. Foodservice contracts frequently reset on a quarterly basis, which puts pressure on processor margins during downturns, and retail brands find it difficult to withstand sudden fluctuations in costs.


Food-Versus-Fuel Supply Competition

Nowadays, a significant portion of the maize oil produced in the United States is absorbed by biofuel companies. Distillers' maize oil is one of the most important inputs for biomass-based diesel, according to EIA feedstock data [4]. Fuel purchasers outbid food refiners when credit values increase, which reduces supply for bottlers and ingredient consumers. During high-credit times, the competition limits the amount of food channels that can be used.


Omega-6 Health Perception

Corn oil contains more than 50% linoleic acid and a high omega-6 to omega-3 ratio. Nutrition commentary favoring monounsaturated fats has steered some health-focused shoppers toward olive and high-oleic alternatives [13]. The debate remains unsettled scientifically, but perception alone slows premium retail growth in North America and Western Europe.

GMO Perception and Non-GMO Sourcing Costs

More than 90% of U.S. corn acreage is planted with genetically engineered varieties, according to USDA data [1]. European and some Asian buyers demand non-GMO or identity-preserved supply, which requires segregated handling and testing. Those controls add cost and limit the pool of qualified exporters, slowing penetration in label-sensitive markets.

Biofuel Policy Uncertainty

Fuel-side demand depends on rules that change frequently. The July 2025 budget law restricted 45Z eligibility to feedstocks from the United States, Mexico, and Canada from 2026 [8], while EPA's June 2025 proposal would halve RIN generation for imported feedstocks [22]. Shifting rules complicate long-term offtake contracts and plant investment decisions.

Corn Oil Market Opportunities

Non-GMO and Organic Premium Retail

Identity-preserved and organic corn oils command meaningful price premiums in European and East Asian grocery channels. Processors with segregated wet-milling lines can capture that value, particularly for Unrefined and Virgin Corn Oil. Traceable sourcing programs tied to non-GMO verification open private-label contracts with retailers seeking clean-label differentiation.

Carbon-Intensity Data as a Revenue Stream

Low carbon-intensity feedstock earns more under California's LCFS and the federal 45Z credit [7][9]. Ethanol plants that meter energy use and certify farm-level practices can sell verified CI data alongside the oil, creating a new data-driven business model. Digital traceability platforms that package this documentation for refiners could command subscription or per-lot fees.

Emerging-Market Retail Expansion

India, Southeast Asia, and North Africa show rising per capita consumption of packaged oils as consumers shift from loose to branded formats. Import-dependent markets reward suppliers with reliable logistics and competitive landed costs. Small-pack formats priced for daily purchase offer a clear entry route in lower-income segments.

Engineered Frying Blends for Quick-Service Chains

Horeca growth favors blends that extend fry life and reduce oil changes. Suppliers pairing blended corn oil with fryer-monitoring services can shift from commodity sales to performance-based contracts priced per fry cycle. This model lowers operators' total cost and locks in multi-year supply relationships.

Pharmaceutical and Cosmetic Grades

Highly refined corn oil serves as a carrier in soft-gel capsules and as an emollient in skin-care formulations. Volumes are small, but margins are several times higher than commodity grades. Processors with pharmaceutical-grade quality systems can diversify revenue away from fuel-credit volatility.

Corn Oil Market Future Outlook

Low-Carbon Fuel Feedstock Supercycle

The IEA's Renewables 2024 report forecasts global biofuel demand growing by close to 40 billion liters over 2024–2030, with renewable diesel and biojet accounting for much of the increase [21]. Lipid feedstocks with low carbon scores will stay scarce, keeping distillers corn oil in demand. The Corn Oil Market will increasingly price off fuel-credit values rather than food fundamentals.

Health-Led Reformulation and Clean Label

Food manufacturers will continue replacing hydrogenated and palm-heavy fats in snacks, bakery, and frying applications. Blended formulations that balance oxidative stability with nutritional positioning will gain share. Expect more brands to pair corn oil with high-oleic oils and natural antioxidants to address omega-6 concerns without sacrificing price [15].

Digital Traceability and AI-Driven Procurement

Large buyers are adopting digital platforms that track origin, GMO status, and carbon intensity lot by lot. Machine learning tools that forecast crush margins and credit values will guide when processors direct oil to food or fuel channels. Suppliers unable to supply structured data risk exclusion from premium contracts.

ESG and Carbon-Intensity Reporting

Scope 3 disclosure requirements are pushing food companies to quantify supply-chain emissions. California's LCFS amendments tightened carbon-intensity targets toward a 30% cut by 2030 [9], and similar frameworks are spreading. Processors that document farm practices and plant energy use will capture price premiums in both food and fuel channels.

Regional Market Share Analysis

Region Key Metric Primary Investment Themes
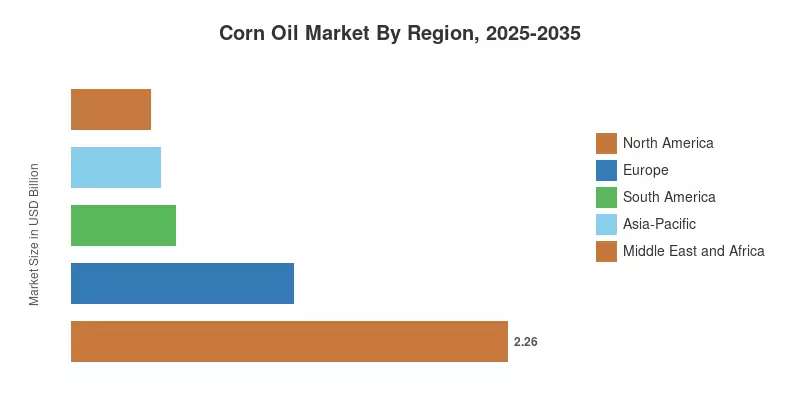
North America 38.4% share Dry-mill oil recovery, renewable diesel feedstock
Europe USD 1.15 Billion Certified biofuel imports, non-GMO retail
Asia-Pacific 7.9% CAGR Foodservice expansion, wet-milling capacity
South America 9.2% share Brazil corn ethanol, biodiesel blending
Middle East and Africa 6.9% CAGR Import-led retail, urban foodservice
Total USD 5.88 Billion —

Regional performance in the Corn Oil Market reflects where corn is processed, how biofuel policy is structured, and how quickly organized foodservice is growing.


North America

Country Key Metric Key Driver
US 84.5% share of region RFS, 45Z credit, dry-mill extraction
Canada 5.8% CAGR Clean Fuel Regulations, retail demand
Mexico USD 0.21 Billion Foodservice growth, 45Z feedstock eligibility


The U.S. dominates regional supply through roughly 190 ethanol plants and a mature wet-milling sector [10]. Federal incentives keep fuel demand firm, and the 2025 budget law's North American origin rule favors domestic and Mexican feedstock over imports [8]. Canada's growth comes from low-carbon fuel requirements and steady retail consumption, while Mexico gains from both foodservice expansion and eligibility under the new U.S. feedstock rules.

Europe

Country Key Metric Key Driver
Germany 17.8% share of region Biofuel blending, food manufacturing
UK USD 0.12 Billion Retail private label
France 4.9% CAGR Wet-milling, food ingredients
Italy 11.2% share of region Food processing, household use
Spain USD 0.10 Billion Foodservice, tourism demand
Nordic Countries 4.6% CAGR Renewable diesel refining
Russia 13.5% share of region Domestic corn processing
Rest of Europe USD 0.25 Billion Eastern European corn supply


European demand splits between food manufacturing and certified biofuel feedstock. The Renewable Energy Directive's sustainability criteria require documented supply chains, which favors ISCC-certified corn oil from established exporters. Nordic refiners running hydrotreated vegetable-oil-route plants absorb low-carbon feedstocks, while southern European markets rely on retail and foodservice consumption. Non-GMO requirements remain a gatekeeper for imported volumes.

Asia-Pacific

Country Key Metric Key Driver
China 41.5% share of region Wet-milling scale, catering growth
India 9.1% CAGR Import substitution, packaged formats
Japan USD 0.17 Billion Premium retail, food manufacturing
South Korea 5.9% share of region Processed foods, QSR
ASEAN 8.3% CAGR Urban foodservice expansion
Rest of Asia-Pacific USD 0.14 Billion Australia and New Zealand retail


China anchors the region through large integrated corn processors and a catering sector exceeding CNY 5.5 trillion in revenue [25]. India is the growth engine: the country imports roughly 60% of its edible oil needs, and packaged corn oil is gaining share as a mid-priced option in metro retail [14]. ASEAN demand rises with quick-service chain openings in Vietnam, Indonesia, and the Philippines, where standardized frying specifications favor refined grades.

South America

Country Key Metric Key Driver
Brazil 58.4% share of region Corn ethanol oil recovery
Argentina 7.2% CAGR Corn exports, biodiesel
Rest of South America USD 0.07 Billion Household consumption


Brazil's corn ethanol boom is converting the country into a meaningful corn oil producer, with new plants in the Center-West adding extraction capacity [24]. Rising biodiesel blend mandates create a domestic outlet for recovered oil. Argentina, one of the world's largest corn exporters, holds untapped processing potential, and policy stability will determine how quickly that capacity materializes.

Middle East and Africa

Country Key Metric Key Driver
Saudi Arabia 21.6% share of region Retail and foodservice imports
UAE 7.6% CAGR Re-export hub, hospitality sector
South Africa USD 0.05 Billion Domestic corn milling
Egypt 18.9% share of region Subsidized retail demand
Rest of MEA 6.1% CAGR Urbanization in Sub-Saharan Africa


Gulf markets rely almost entirely on imports and favor refined, branded products for retail and hospitality. The UAE doubles as a regional trading hub, re-exporting to East Africa and South Asia. South Africa benefits from domestic corn surpluses, while Egypt's demand is shaped by food subsidy programs and currency movements that affect import affordability.

Corn Oil Market By Region, 2025-2035

Corn Oil Market Segmentation

By Product Grade


Segment Key Metric Primary Demand Driver
Refined Corn Oil 66.5% share Neutral flavor, high smoke point, cost efficiency
Unrefined and Virgin Corn Oil USD 0.73 Billion Nutrient retention, premium positioning
Blended Corn Oil 7.55% CAGR Engineered fry life, cost balance


Refined Corn Oil dominates because refining removes free fatty acids and pigments, delivering a smoke point near 232°C and long shelf life that suit industrial frying and retail bottling. Unrefined and Virgin Corn Oil stays niche, limited by darker color, stronger flavor, and lower smoke points, yet it earns premium prices from nutrient-focused shoppers. Blended Corn Oil grows fastest as processors combine corn oil with other plant oils to tune oxidative stability and cost for specific applications.

By End User


Segment Key Metric Primary Demand Driver
Industrial 51.6% share Biofuel feedstock, feed, processed foods
Household/Retail Consumers USD 1.77 Billion Value pricing, heart-health claims
Horeca 8.40% CAGR QSR reformulation, fry-life economics


Industrial users lead, driven by renewable diesel and biodiesel producers, feed manufacturers, and processed-food makers relying on corn oil's neutral taste and stability. Household/Retail Consumers form a stable base supported by competitive pricing and the FDA-qualified health claim [23]. Horeca grows fastest as quick-service restaurants and institutional kitchens move away from partially hydrogenated oils toward blended formulations that last longer in fryers and cut oil-change labor.

Competitive Benchmarking

The Corn Oil Market is highly concentrated at the processing level, with an estimated Herfindahl-Hirschman Index of 1,500–1,800 and the top five players holding roughly 45–55% of global revenue. Integrated agribusinesses control wet-milling and crushing assets, while ethanol producers supply much of the distillers' corn oil sold into fuel channels. Regional packers and private-label bottlers fragment the retail tier.

Company Est. Revenue Share Range Key Offerings for Corn Oil Market Strategic Positioning
Archer Daniels Midland Company ~12–15% Refined corn oil, distillers corn oil, bulk ingredients Integrated corn processing and renewable fuel feedstock leader
Cargill, Incorporated ~11–14% Refined and blended frying oils, foodservice solutions Trans-fat-free portfolio, global foodservice reach
Bunge Global SA ~8–11% Bulk and packaged oils, blended formulations Expanded origination after Viterra combination
Wilmar International Limited ~5–8% Branded retail oils across Asia Dominant Asian distribution footprint
Ingredion Incorporated ~5–7% Corn germ and refined corn oil Wet-milling specialist with ingredient focus
Associated British Foods plc (ACH Food Companies) ~4–6% Mazola-branded retail corn oil Leading North American retail brand
COFCO Corporation ~3–5% Refined corn oil for Chinese retail and foodservice State-backed scale in China
AWL Agri Business Limited ~2–4% Packaged oils for Indian retail Broad Indian distribution network
Louis Dreyfus Company ~2–4% Bulk oils and origination Global trading and logistics strength
Grain Processing Corporation ~1–3% Corn-derived oils and ingredients Specialty wet-milling in the U.S. Midwest


Recent News & Developments

Policy actions shaped the Corn Oil Market more than product launches during 2023–2025.

  • World Health Organization (January 2023): Reported that 43 countries had implemented best-practice trans-fat policies covering 2.8 billion people, accelerating reformulation toward refined and blended oils [11]
  • U.S. EPA (June 2023): Finalized RFS volumes for 2023–2025, raising biomass-based diesel obligations to 3.35 billion gallons by 2025 and supporting corn oil feedstock demand [5]
  • U.S. EPA (June 2024): Approved POET Shelbyville's RFS pathway recognizing corn oil as a dry-mill ethanol coproduct, clarifying fuel-market eligibility [6]
  • California Air Resources Board (November 2024): Approved LCFS amendments tightening carbon-intensity targets, raising the value of low-CI feedstocks [9]
  • U.S. Treasury (January 2025): Issued guidance for the 45Z Clean Fuel Production Credit, rewarding feedstocks such as distillers corn oil [7]
  • U.S. EPA (June 2025): Proposed 2026–2027 RFS volumes with reduced RIN generation for imported feedstocks, favoring domestic corn oil [22]
  • U.S. Congress (July 2025): Extended the 45Z credit through 2029 and limited eligibility to North American feedstocks from 2026 [8]
  • Bunge (July 2025): Completed its combination with Viterra, expanding origination and processing reach across oilseed and grain supply chains [16]

Corn Oil Market Report Scope

Parameter Details
Market Scope Global Corn Oil Market by Product Grade, End User, and Region
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.37% (2026–2035)
Market Size checkpoints USD 5.88 Billion (2025); USD 6.25 Billion (2026); USD 10.90 Billion (2035)
Fastest Growing Segments Blended Corn Oil (Product Grade); Horeca (End User); Asia-Pacific (Region)
Companies Profiled ADM, Cargill, Bunge, Wilmar, Ingredion, ABF (ACH Food), COFCO, AWL Agri Business, Louis Dreyfus, Grain Processing Corporation
Valuation Currency USD Billion; volume in liters
CAGR Driver Disclaimer Driver and restraint impacts are directional estimates and not additive to the headline CAGR

FAQs

How does distillers corn oil differ from food-grade oil in the Corn Oil Market?
Distillers corn oil is recovered from ethanol stillage and carries higher free fatty acids, so it goes mainly to biofuel and feed. Food-grade oil comes from wet-mill germ pressing and full refining, earning a price premium [10].
What should foodservice buyers compare when choosing frying oils?
Buyers should compare total cost per fry cycle rather than price per liter. Fry-life trials under actual menu conditions reveal how often oil must be replaced and how labor costs change.
Which certifications matter most for exporters in the Corn Oil Market?
ISCC sustainability certification is increasingly required for biofuel-bound volumes entering Europe and California programs. Non-GMO verification remains the key credential for food-grade shipments to label-sensitive Asian and European buyers [9].
How do carbon-intensity scores affect corn oil pricing?
Lower scores earn more credits under the LCFS and 45Z, so refiners pay more for documented low-CI lots. Plants that meter energy use and certify farm practices capture the largest premiums [7][9].
Is corn oil used in pharmaceutical products?
Yes, highly refined corn oil serves as a carrier in soft-gel capsules and some injectable formulations. Pharmaceutical grades require stricter quality systems but deliver margins well above commodity sales.
What risks should new investors in the Corn Oil Market weigh?
Policy exposure is the largest risk, since credit values shift with each EPA rule or tax guidance update. Returns should hold up even if fuel premiums narrow and food channels must carry margins [22].
How do refiners extend corn oil shelf life?
Refiners add natural tocopherols and flush bottles with nitrogen during filling to limit oxidation. UV-blocking packaging further slows rancidity on retail shelves.
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of agricultural databases, peer-reviewed food science journals, industry publications, and authoritative regulatory bodies. Key sources included the US Department of Agriculture (USDA), National Corn Growers Association (NCGA), Corn Refiners Association (CRA), Food and Drug Administration (FDA), Environmental Protection Agency (EPA), US Energy Information Administration (EIA), National Institute of Food and Agriculture (NIFA), European Food Safety Authority (EFSA), European Commission Agriculture and Rural Development, Food and Agriculture Organization (FAO) of the United Nations, International Grains Council (IGC), US Grains Council (USGC), National Oilseed Processors Association (NOPA), American Oil Chemists' Society (AOCS), USDA National Agricultural Statistics Service (NASS), USDA Economic Research Service (ERS), International Trade Centre (ITC) Trade Map, World Bank Commodity Price Data, OECD-FAO Agricultural Outlook, US Census Bureau Trade Data, and national agricultural ministry reports from Brazil, Argentina, China, and India. These sources were used to collect production and consumption statistics, regulatory compliance data, pricing trends, biodiesel mandate policies, trade flow analysis, and market landscape assessment for crude corn oil, refined corn oil, food-grade applications, industrial applications, and biodiesel feedstock segments.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. CEOs, VPs of Operations, procurement heads, and commercial directors from corn oil refiners, maize wet millers, and biodiesel manufacturers comprised the supply-side sources. Demand-side sources included category managers from food and beverage companies, procurement leads from pharmaceutical and cosmetics firms, R&D chiefs from industrial applications, and sustainability officers from biofuel companies. Market segmentation was verified, capacity expansion timelines were confirmed, and insights regarding the adoption of extraction technology, pricing volatility management, and supply chain sustainability practices were obtained through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

By Region: North America (32%), Europe (30%), Asia-Pacific (25%), Rest of World (13%)


Market Size Estimation

Global market valuation was derived through production volume and revenue mapping analysis. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across crude corn oil, refined corn oil, food-grade corn oil, feed-grade corn oil, and industrial/biodiesel applications

Analysis of reported and modeled annual revenues specific to corn oil product portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (production volume × ASP by region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations, accounting for by-product economics from corn wet milling and dry milling processes

This methodology is tailored for the corn oil market's unique characteristics, emphasizing agricultural data sources, food safety regulators, and biofuel policy frameworks while maintaining the structural format you've consistently used.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















