Consumer Electronics MLCC Market Summary
The Consumer Electronics Mlcc Market was valued at USD 13.21 Billion in 2025 and is projected to reach USD 15.34 Billion in 2026, climbing to USD 55.09 Billion by 2035 at a CAGR of 15.26% over 2026–2035. Two catalysts anchor this outlook. The first is the steady rise of 5G handsets, which carry far denser RF front-end circuitry than 4G designs. The second is industrial policy: India approved an outlay of INR 22,919 crore in 2025 for its Electronics Component Manufacturing Scheme, pulling capacitor production closer to fast-growing assembly hubs [5].
Key Report Takeaways
• By Dielectric Type
- Class 1 capacitors held a 58.4% share of the Consumer Electronics Mlcc Market in 2025, supported by demand for temperature-stable C0G/NP0 parts in RF circuits
- Class 2 parts generated USD 5.50 Billion in 2025, anchored in bulk power-rail decoupling
• By Case Size
- The 201 footprint accounted for a 52.3% share in 2025, reflecting its dominance in space-constrained handsets.
- The 402 case size is forecast to expand at a 15.8% CAGR as high-volume factories standardize on it for assembly yield.
• By Voltage
- Low Voltage (less than or Equal To 100V) parts captured a 55.2% share, since nearly all mobile subsystems run below 12 V
- Mid-voltage 100-500V capacitors generated USD 4.27 billion in 2025, tied to GaN charger adoption.
• By MLCC Mounting Type
- Surface-Mount parts held a 38.7% share in 2025
- Metal Cap variants are projected to grow at a 15.6% CAGR as drop-test thresholds tighten in premium phones.
• By Region
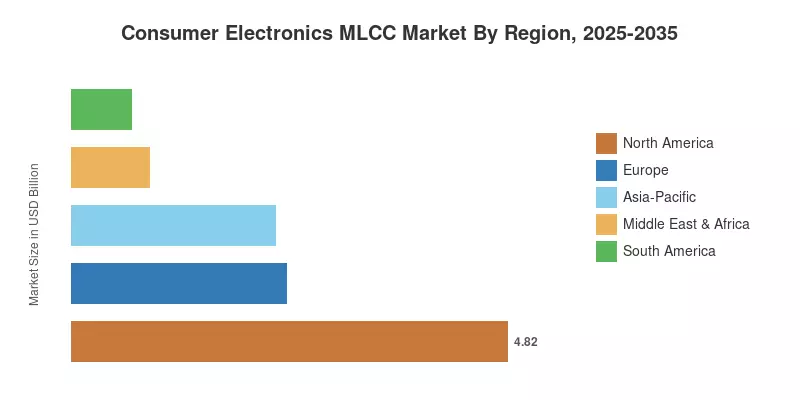
- North America led the Consumer Electronics Mlcc Market with a 36.5% share in 2025
- Asia-Pacific is expected to post a 17.1% CAGR through 2035
- Europe represented USD 2.38 billion in 2025
Market Size and Forecast (2021–2035)
Estimates for the Consumer Electronics MLCC Market combine bottom-up shipment modeling of smartphones, PCs, tablets, wearables, and home devices with average capacitor content per device and weighted average selling prices by case size and dielectric class. Supply-side checks draw on vendor segment disclosures, trade statistics, and industry association production data, while demand-side checks use device tracker data and interviews with procurement and design engineers [21].





 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



