Computer Vision Market (2026 - 2035)

Computer Vision Market Size, Share and Research Report By Privacy and Sovereignty Constraints, By Data and Talent Bottlenecks, By Brownfield Integration Friction and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
ID: MRFR/ICT/4050-CR 200 Pages Apoorva Priyadarshi, Shubham Munde Last Updated: August 27, 2026
Computer Vision Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)14.8%
2025 Market SizeUSD 25.75 Billion
2035 Market SizeUSD 107.05 Billion
Key Players
Cognex Corporation
Keyence Corporation
NVIDIA Corporation
Sony Semiconductor Solutions
Teledyne Technologies
Intel Corporation
Opportunities
  • Vision-as-a-Service Contracting
  • Emerging-Market Manufacturing Corridors
  • Imagery Data Monetization

Computer Vision Market Summary

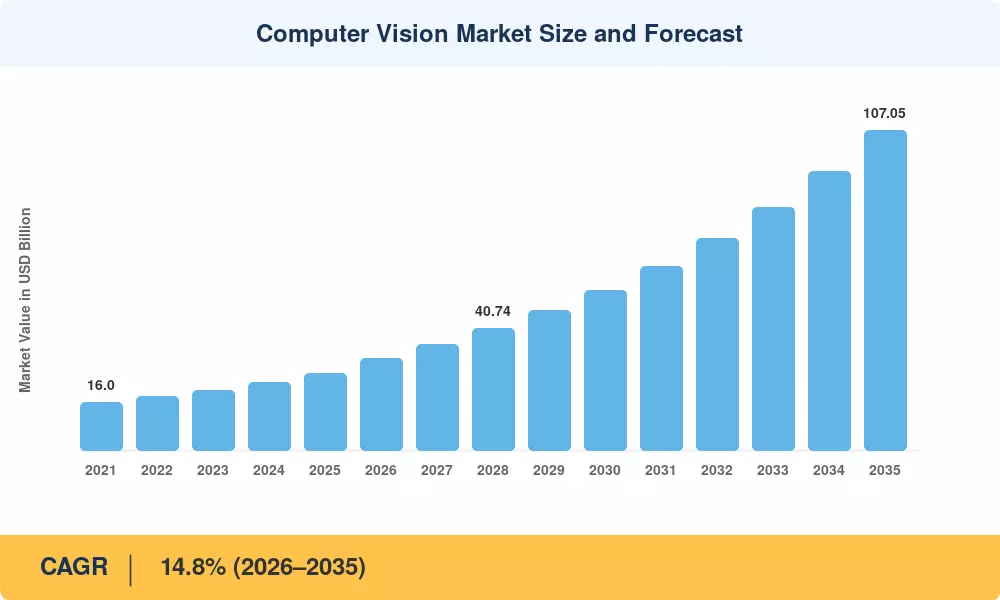
The Computer Vision Market reached USD 25.75 billion in 2025 and opens its forecast run at USD 30.91 billion in 2026, climbing to USD 107.05 billion by 2035 at a 14.8% CAGR. Two catalysts anchor that trajectory. The first is the CHIPS and Science Act, which committed USD 52.7 billion to domestic semiconductor manufacturing and research, tightening the supply of image sensors and inference silicon that vision systems depend on [2]. The second is vehicle safety regulation: Euro NCAP and equivalent United States rulemaking have effectively made forward-facing cameras standard equipment on new passenger vehicles [4].

The trainable neural inference stacks that tolerate part variation and changeover are replacing fixed-rule machine vision – threshold-based blob detection, hand-tuned lighting rigs, single-purpose smart cameras – that factories once relied on. Money is coming in. Global industrial automation manufacturers are forecast to spend over 19% more on vision-enabled inspection cells between 2023 and 2025, with pharmaceutical serialization and food safety standards accounting for a disproportionate amount of that spend [9][12].


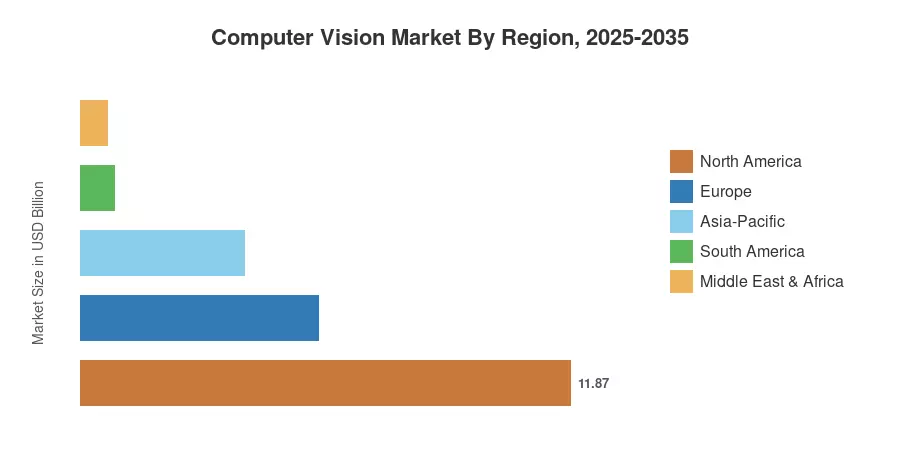
In 2025, the Computer Vision Market saw North America contribute 46.1% of revenue, fueled by demand from hyperscalers and defense imaging programs. Asia-Pacific quickest at 15.4% CAGR through 2035, driven by Chinese and Korean factory-automation subsidies. Europe is second, driven by automotive tier-one demand and a regulatory environment that favors auditable on-premise inference. The competitive dilemma over the next decade will change from who creates the best camera to who owns the model lifecycle.


Key Report Takeaways

• By Technology

  • Hardware accounted for 61.3% of Computer Vision Market share in 2025, still the revenue anchor despite margin migration toward software.
  • Software is compounding at a 14.9% CAGR through 2035 as subscription licensing displaces perpetual seat models.
  • Edge deployment held 44.5% of installed value in 2025, outpacing both cloud and on-premise footprints.

• By Sector

  • Manufacturing led the Computer Vision Market with a 26.8% share in 2025
  • Automotive is the fastest-expanding end-user vertical at a 17.1% CAGR over 2026–2035
  • Life sciences applications generated USD 3.66 billion in 2025

• By Geography

  • North America commanded 46.1% of global revenue in 2025
  • Asia-Pacific posts the fastest regional CAGR at 15.4% through 2035
  • Europe generated USD 5.77 billion across the Computer Vision Market in 2025


Market Size and Forecast (2021–2035)

The figures below are a blend of supply-side revenue triangulations from vision hardware and software providers, import data at the customs level for image sensors and industrial cameras and demand-side installation counts from automotive, pharmaceutical and logistics capital budgets. Historical years are reconciled against audited files, and prospective years are reconciled using the calibrated 14.8% growth rate for the Computer Vision Market for 2026-2035.
Computer Vision Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
ADAS and vehicle safety camera mandates ~3.1 pp Global (EU, US, Japan) Medium-term (2–4 yr)
Falling cost of edge inference silicon ~2.8 pp Global Short-term (≤2 yr)
Pharmaceutical and food quality-control rules ~2.2 pp North America, Europe Short-term (≤2 yr)
Semiconductor incentive programs ~1.9 pp North America, Europe Long-term (≥4 yr)
Skilled inspection labour shortages ~1.7 pp Asia-Pacific, Europe Medium-term (2–4 yr)
Retail loss prevention and frictionless checkout ~1.4 pp North America, Asia-Pacific Medium-term (2–4 yr)
Public-safety and smart-city procurement ~1.2 pp Asia-Pacific, MEA Long-term (≥4 yr)


Regulated Vehicle Vision

Regulators removed the optionality. Euro NCAP's protocol updates and the United States rule requiring automatic emergency braking on essentially all light vehicles by the 2029 model year have converted forward cameras from a premium trim option into a homologation requirement [4][5]. Tier-one suppliers now quote multi-year camera module programs at volumes that justify dedicated ASIC development, and the resulting unit-cost compression cascades into adjacent industrial applications.

Edge Silicon Economics

Inference that once required a discrete accelerator card now runs on integrated blocks inside mainstream processors from AMD, Qualcomm, and Intel. Cost per inferred frame at the industrial edge declined by roughly 40% between 2022 and 2025 [7]. That shift matters because it moves vision from a capital project requiring a server closet to a line-item upgrade on an existing control cabinet.

Quality Compliance in Regulated Manufacturing

Pharmaceutical serialization under the Drug Supply Chain Security Act and food-facility rules under FSMA Section 204 both demand traceable, image-backed evidence of unit-level integrity [9][10]. Deployment of computer vision for quality inspection in manufacturing has therefore become an audit-defense expenditure rather than a productivity experiment — a distinction that survives capital-budget scrutiny in downturns.

Industrial Labour Scarcity

Manufacturers across Japan, Germany, and Korea report unfilled inspection and metrology roles at rates exceeding 15% of budgeted headcount [12]. Vision cells absorb that gap without the recruitment lag, which explains why the Computer Vision Market grows fastest in the same economies posting the steepest demographic decline.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Data-sovereignty and biometric privacy law ~-1.9 pp Europe, China Medium-term (2–4 yr)
Integration and vision-engineering talent scarcity ~-1.5 pp Global Short-term (≤2 yr)
Annotation and training-data acquisition cost ~-1.2 pp Global Short-term (≤2 yr)
Brownfield retrofit and legacy control complexity ~-1.0 pp North America, Europe Medium-term (2–4 yr)
Hardware ASP compression from embedded accelerators ~-0.8 pp Global Long-term (≥4 yr)


Privacy and Sovereignty Constraints

The EU AI Act classifies several vision use cases — remote biometric identification, emotion inference in workplaces — as prohibited or high-risk, carrying penalties of up to 7% of global turnover [6]. China's data-export rules impose parallel friction on cloud-hosted training pipelines. Vendors respond by localizing inference, which raises deployment cost per site and slows multi-country rollouts.

Data and Talent Bottlenecks

Labelled defect imagery remains scarce precisely where it is most valuable: low-defect, high-value production lines produce few positive examples. Enterprises report annotation and validation consuming 55–70% of total project hours on first deployments [13]. Combine that with a thin bench of engineers fluent in both optics and machine learning, and pilot-to-production conversion stalls.

Brownfield Integration Friction

Most factories are not greenfield. Retrofitting vision into installed PLC and MES environments means reconciling deterministic control logic with probabilistic model outputs, and integration frequently exceeds hardware cost by a factor of two to three on legacy lines [14].


Computer Vision Market Opportunities

Vision-as-a-Service Contracting

Subscription pricing tied to inspected units rather than installed cameras converts a capital objection into an operating expense. Vendors capturing recurring revenue at 70%-plus gross margins reset their valuation multiples, and buyers gain model retraining as an included service.

Emerging-Market Manufacturing Corridors

India's Production Linked Incentive schemes and ASEAN electronics relocation are creating greenfield plants that specify vision from day one, avoiding the retrofit penalty described earlier [11]. These corridors represent the highest-conversion pipeline in the Computer Vision Market outside established industrial economies.

Imagery Data Monetization

Aggregated, anonymized defect libraries have standalone commercial value — for insurers underwriting product liability, for equipment vendors benchmarking process drift, and for consortium training sets. Contract language governing image ownership is becoming a negotiated term rather than boilerplate [13].

Sensor Fusion Beyond RGB

Hyperspectral, thermal, and time-of-flight channels detect failure modes invisible to colour cameras. Food sorting and battery-electrode inspection are the earliest volume adopters, and fusion stacks carry materially higher average selling prices.

Compliance Tooling for Regulated AI

Model documentation, drift monitoring, and audit trails are becoming purchasable products in their own right as the EU AI Act phases in obligations through 2027 [6].


Computer Vision Market Future Outlook

Autonomous Operations

Vision graduates from inspection to closed-loop control across the decade. Robotic cells that adjust grip, path, and force from live imagery rather than fixed teach-points reduce changeover time on mixed-model lines, and the International Federation of Robotics projects installed industrial robot stock surpassing 7 million units globally within the forecast window [12].

Platform Economics

Value migrates toward whoever owns retraining. Camera hardware commoditizes as accelerators embed into mainstream silicon, while model management, drift detection, and labelled-data assets accrue switching costs. Expect software to approach parity with hardware revenue in the Computer Vision Market before 2035.

Energy and Compute Constraints

Data-centre electricity demand is on track to roughly double by 2030 on International Energy Agency projections. That pressure pushes vision inference toward the edge for reasons of power and cost, not just latency [18]. Watts per inference becomes a procurement specification.

Sustainability and Traceability Reporting

Corporate reporting regimes increasingly require verified physical-world evidence — waste streams, yield loss, packaging composition. Vision systems already capture that data as a by-product of inspection, positioning them as reporting infrastructure alongside their quality function [19].


Computer Vision Market Segmentation

Segmentation in the Computer Vision Market follows four dimensions: components, end-user industry, application, and deployment.

By Components

Segment Metric Primary Demand Driver
Hardware 61.3% share (2025) Cameras, optics, sensors and inference modules
Software 14.9% CAGR (2026–2035) Subscription model licensing and retraining services


Hardware still books the majority of revenue in the Computer Vision Market because every deployment requires physical capture. Its share erodes slowly, though, as accelerator functions fold into general-purpose processors and eliminate discrete card purchases. Software's faster compounding reflects a pricing shift: annual licences tied to inspected volume, bundled with model updates, produce revenue that recurs long after the camera is depreciated.

By End-User Industry

Segment Metric Primary Demand Driver
Manufacturing 26.8% share (2025) Defect detection and process control
Automotive 17.1% CAGR (2026–2035) ADAS camera mandates and assembly inspection
Life Sciences USD 3.66 billion (2025) Serialization and vial integrity checks
Retail 13.1% share (2025) Shrink reduction and checkout automation
Logistics 11.6% share (2025) Parcel dimensioning and damage capture
Agriculture 15.9% CAGR (2026–2035) Grading, sorting and yield estimation
Other Industries 7.6% share (2025) Energy, construction and public safety


Manufacturing leads the Computer Vision Market because the return calculation is unambiguous: scrap avoided and rework eliminated map directly to plant P&L. Automotive grows faster for a regulatory reason rather than an economic one — camera content per vehicle is legislated upward, and assembly-line inspection for panel gap, weld quality, and harness routing scales alongside it.

By Application

Segment Metric Primary Demand Driver
Inspection & Quality Assurance 38.6% share (2025) Regulated audit and scrap reduction
Surveillance USD 5.10 billion (2025) Public safety and perimeter monitoring
Measurement 16.4% share (2025) Dimensional metrology and tolerance verification
Classification 15.2% CAGR (2026–2035) Deep learning object detection and recognition at line speed
3D Modeling & Reconstruction 16.4% CAGR (2026–2035) Robotic bin-picking and digital twin capture


Inspection dominates because it monetizes fastest. Reconstruction grows quickest because robotics finally needs it — bin-picking and autonomous navigation demand depth, not just pixels, and depth sensing has become affordable enough to specify at cell level within the Computer Vision Market.

By Deployment

Segment Metric Primary Demand Driver
Edge 44.5% share (2025) Latency, sovereignty and bandwidth economics
On-Premise 30.2% share (2025) Regulated environments and legacy integration
Cloud 14.1% CAGR (2026–2035) Model training and multi-site fleet management


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 46.1% share Semiconductor incentives, defense imaging, retail automation
Europe USD 5.77 billion Automotive tier-one demand, regulated AI compliance
Asia-Pacific 15.4% CAGR (2026–2035) Factory automation subsidies, electronics relocation
South America 3.2% share Agribusiness grading, mining safety monitoring
Middle East & Africa USD 0.65 billion Smart-city programs, logistics hub screening
Total USD 25.75 billion

Regional performance across the Computer Vision Market reflects where inference silicon is fabricated, where safety regulation binds hardest, and where factory capital is being deployed.


North America

Country Metric Key Driver
US 78.4% of regional revenue Semiconductor incentives and hyperscaler demand
Canada USD 1.54 billion Automotive assembly and forestry grading
Mexico 13.6% CAGR Nearshored electronics and appliance assembly


Federal semiconductor funding has done more for this region than any single end-market. Awards under the CHIPS program touch sensor fabrication, advanced packaging, and inference logic simultaneously, and the resulting domestic supply reduces lead-time risk that previously delayed large vision rollouts [2]. Retail deployment adds a second engine, with shrink-reduction programs at national grocery chains reaching four-figure store counts [15].

Europe

Country Metric Key Driver
Germany 27.3% of regional revenue Automotive and machine-building inspection
UK USD 0.81 billion Pharmaceutical and logistics screening
France 12.4% of regional revenue Aerospace composite inspection
Italy 10.1% of regional revenue Packaging machinery integration
Spain 13.9% CAGR Food processing and agri-grading
Nordic Countries USD 0.44 billion Battery gigafactory metrology
Russia 3.8% of regional revenue Constrained by export controls
Rest of Europe 14.6% CAGR Central European contract manufacturing


Europe's distinguishing feature is regulatory gravity. The EU AI Act pushes buyers toward on-premise and edge architectures with documented model provenance, which suppresses cloud-vision attach rates but lifts hardware and services content per site [6]. German machine builders, meanwhile, embed vision as a shipped subsystem rather than an aftermarket add-on, exporting that content globally.

Asia-Pacific

Country Metric Key Driver
China 41.7% of regional revenue Factory automation policy and domestic sensor supply
India 18.9% CAGR Production Linked Incentive manufacturing build-out
Japan USD 1.19 billion Precision metrology and robotics integration
South Korea 14.8% of regional revenue Display, battery and semiconductor inspection
ASEAN 17.2% CAGR Electronics assembly relocation
Rest of Asia-Pacific 4.6% of regional revenue Textiles and food processing


Robot installation density tells the story: Korea and Singapore lead global rankings, and vision attach rates on new industrial robots now exceed half of shipments in advanced Asian economies [12]. India's trajectory is different in kind — greenfield capacity specified with edge-based computer vision for automation from the initial line layout, skipping a generation of rule-based systems entirely [11].

South America

Country Metric Key Driver
Brazil 63.5% of regional revenue Protein processing and grain grading
Argentina USD 0.11 billion Agricultural sorting and export inspection
Rest of South America 13.2% CAGR Mining safety and copper concentrate monitoring


Agribusiness anchors demand here. Brazilian meat processors deploy vision grading to meet importer specifications for cut consistency and foreign-object detection, requirements that carry direct trade consequences when audits fail [10]. Chilean and Peruvian mining operations add a second demand pool around haul-road safety and personnel-proximity detection.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 34.8% of regional revenue Vision 2030 industrial and city programs
UAE USD 0.16 billion Logistics hub and airport screening
South Africa 11.9% of regional revenue Mining and automotive assembly
Egypt 15.6% CAGR Textile and food manufacturing
Rest of MEA 9.4% of regional revenue Infrastructure monitoring


Gulf state investment programs bundle vision into broader infrastructure procurement rather than buying it as a discrete category, which makes the addressable spend larger but the sales cycle longer [17]. Port and free-zone operators in the UAE have moved fastest, using container and cargo imaging to compress dwell times.


Computer Vision Market By Region, 2025-2035

Competitive Benchmarking

The concentration of the Computer Vision Market is in the medium band. The top five suppliers account for around 34–39% of global sales, and an estimated Herfindahl-Hirschman Index between 550 and 700 indicates that the structure is more fractured than consolidated. Share is fought for at either end, with machine-vision specialists battling semiconductor outfits advancing up the stack and cloud platforms moving down the stack.

Company Est. Revenue Share Range Key Offerings for Computer Vision Market Strategic Positioning
Cognex Corporation ~9–12% Vision systems, deep-learning inspection software, ID readers Pure-play leader in factory inspection [20]
Keyence Corporation ~8–11% Smart cameras, 3D scanners, inline metrology Direct-sales model with premium margins [21]
NVIDIA Corporation ~6–9% Inference GPUs, edge modules, vision SDK stack Compute layer standard-setter [22]
Sony Semiconductor Solutions ~6–8% CMOS image sensors, intelligent vision sensors Upstream sensor supply dominance [23]
Teledyne Technologies ~4–7% Industrial cameras, thermal imaging, frame grabbers Broad imaging portfolio via acquisition [24]
Intel Corporation ~4–6% Vision accelerators, integrated inference blocks, toolkits Embedded accelerator incumbency [7]
OMRON Corporation ~3–5% Vision controllers, robotic integration, sensing Automation-suite bundling
Basler AG ~3–4% Area-scan and line-scan cameras, embedded vision kits Cost-competitive OEM camera supply
Qualcomm Technologies ~2–4% Edge vision SoCs, automotive imaging platforms Automotive and mobile inference reach
SICK AG ~2–4% Industrial sensors, 2D/3D vision, safety systems Safety-certified sensing niche
MVTec Software GmbH ~1–3% Vision libraries and development environments Toolkit layer for integrators
Ambarella Inc. ~1–3% Low-power vision SoCs for automotive and security Power-efficiency specialist


Recent News & Developments

  • Cognex (March 2024): Launched a deep-learning inspection platform aimed at low-defect-rate lines, addressing the training-data scarcity that stalls first deployments [20]
  • European Union (August 2024): The AI Act entered into force, phasing prohibitions and high-risk obligations through 2027 and reshaping biometric vision procurement across the bloc [6]
  • NVIDIA (June 2024): Expanded its edge inference module family with higher TOPS-per-watt parts targeted at industrial vision cells, compressing the cost of on-premise deployment [22]
  • NHTSA (April 2024): Finalized the automatic emergency braking rule for light vehicles, locking camera and sensing content into United States model-year planning through 2029 [5]
  • Teledyne (October 2023): Consolidated its imaging brands under a unified industrial vision portfolio to simplify integrator sourcing [24]
  • Keyence (February 2025): Introduced inline 3D metrology systems for battery electrode inspection, targeting gigafactory quality requirements [21]
  • US Department of Commerce (December 2024): Announced further CHIPS awards covering advanced packaging and sensor fabrication, strengthening domestic vision component supply [2]
  • India MeitY (September 2024): Extended incentive coverage to electronics component manufacturing, pulling vision-equipped assembly capacity into new state clusters [11]


Computer Vision Market Report Scope

Parameter Detail
Market Scope Global Computer Vision Market across components, end-user industry, application, deployment and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 14.8% (2026–2035)
Market Size Checkpoints USD 25.75 billion (2025); USD 30.91 billion (2026); USD 61.63 billion (2031); USD 107.05 billion (2035)
Fastest Growing Segments Software (components); Automotive (end-user industry); 3D Modeling & Reconstruction (application); Asia-Pacific (geography)
Companies Profiled 12 leading suppliers spanning vision hardware, sensors, silicon and software
Valuation Currency USD billion

FAQs

What integration costs should buyers budget beyond hardware in the Computer Vision Market?
Budget two to three times the hardware cost for brownfield integration on legacy lines. Systems engineering, lighting design, and control reconciliation consume most of that figure [14].
How should procurement teams structure model ownership clauses?
Specify that trained model weights and annotated imagery remain buyer property, with vendor licence to use anonymized data only under explicit consent. Ambiguous clauses have blocked later vendor switches [13].
Which vendor selection criteria matter most in the Computer Vision Market?
Prioritize retraining turnaround time, integrator network depth in your region, and documented performance on low-defect datasets. Camera specifications differentiate far less than these operational factors [20].
When does cloud inference still make commercial sense?
Cloud remains preferable for fleet-wide model training, cross-site benchmarking, and applications tolerating latency above 200 milliseconds. Real-time control loops belong at the edge [18].
What compliance documentation will European deployments require?
High-risk classifications demand technical documentation, logging, human oversight provisions, and post-market monitoring. Obligations phase in through 2027, so specify audit trails now rather than retrofitting them [6].
How do buyers evaluate accuracy claims in the Computer Vision Market?
Insist on false-negative rates measured on your own production imagery, not vendor benchmark datasets. Escape rate on defects matters more than headline accuracy percentages [3].
Which emerging use cases warrant early pilots?
Hyperspectral sorting in food processing and electrode inspection in battery manufacturing both show strong early returns. Both address defects that colour imaging cannot detect [21].    
Author
Author
Author Profile
Apoorva Priyadarshi LinkedIn Research Analyst
With 4+ years of experience in Market Intelligence and Strategic Research, Apoorv specializes in ICT, Semiconductor, and BFSI markets. Combining strong analytical capabilities with a deep understanding of technology-driven industries, he focuses on delivering data-driven insights that support strategic decision-making. With a background in technology and business research, Apoorv has contributed to numerous global market studies, competitive landscape analyses, and opportunity assessments across sectors such as semiconductors, digital banking, cybersecurity, and telecommunications.
Co-Author
Co-Author Profile
Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of technology standards databases, peer-reviewed engineering journals, AI research publications, and authoritative ICT organizations. Key sources included the National Institute of Standards and Technology (NIST), National Science Foundation (NSF) Computer and Information Science and Engineering (CISE) Directorate, IEEE Computer Society, Association for Computing Machinery (ACM), Partnership on Artificial Intelligence (PAI), International Organization for Standardization (ISO/IEC JTC 1/SC 42 - AI), European Union Agency for Cybersecurity (ENISA), US Department of Energy (DOE) Advanced Scientific Computing Research, UK AI Council, China Academy of Information and Communications Technology (CAICT), European Commission's AI Watch, National Institutes of Standards and Technology (NIST) Face Recognition Vendor Program (FRVT), and national digital transformation reports from key markets.

The following sources were employed to gather algorithm performance benchmarks, regulatory compliance frameworks (EU AI Act, GDPR biometric guidelines), patent filings, adoption metrics across automotive and healthcare verticals, and competitive landscape analysis for deep learning frameworks, 3D vision systems, and edge computing accelerators.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consisted of CTOs, VPs of AI Research, leaders of edge computing product lines, and computer vision software leads from semiconductor manufacturers, cloud service providers, and AI software vendors. The demand-side sources included chief innovation officers from automotive OEMs, radiology AI directors from healthcare systems, retail loss prevention executives, manufacturing automation engineers, and procurement leads from smart city infrastructure initiatives. Primary research verified the timelines of SDK and API roadmaps, validated technology segmentation across cloud and edge deployment modalities, and collected insights on inference latency requirements, training data acquisition strategies, and ethical AI governance frameworks.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (38%), Europe (28%), Asia-Pacific (26%), Rest of World (8%)

By Vertical Focus: Automotive (28%), Healthcare/Medical Imaging (24%), Retail & E-commerce (18%), Security & Surveillance (16%), Manufacturing & Industrial (14%)


Market Size Estimation

Revenue mapping and inference volume analysis were employed to determine global market valuation. The methodology comprised the following:

The identification of over 60 essential technology providers in North America, Europe, Asia-Pacific, and the Middle East and Africa

Product mapping across deep learning frameworks, machine vision hardware (GPUs, NPUs, VPUs), image processing software, and 3D vision systems

Examination of the annual revenues of computer vision solution portfolios, including cloud API consumption metrics and periphery device shipments, as reported and modeled

Coverage of manufacturers and service providers that account for 75-80% of the global market share in 2024

Derive segment-specific valuations for hardware accelerators, software platforms, and integrated vision systems by extrapolating using bottom-up (deployment volume × ASP by deployment mode: cloud/edge/on-premises across face recognition, medical imaging, and object detection applications) and top-down (vendor revenue validation across NVIDIA, Intel, Microsoft, Google, and emerging pure-play computer vision startups) approaches.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















