Clean Energy Technology Market (2026 - 2035)

Clean Energy Technology Market Research Report By Technology (Solar Photovoltaic, Wind (Onshore & Offshore), Energy Storage Systems, Hydrogen & Electrolysers, Carbon Capture & Utilisation, Nuclear & Advanced Reactors, Bioenergy & Geothermal), By Sector (Utility-Scale Power, Industrial Decarbonisation, Commercial & Institutional, Residential, Transport & Charging Infrastructure), By End User (Independent Power Producers, Regulated Utilities, Industrial Corporates, Government & Public Sector, Households & Prosumers) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast to 2035
ID: MRFR/EnP/34140-HCR 100 Pages Chitranshi Jaiswal Last Updated: September 17, 2026
Clean Energy Technology Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)9.4%
2025 Market SizeUSD 1,182.0 Billion
2035 Market SizeUSD 2,905.0 Billion
Key Players
Siemens Energy
Vestas Wind Systems
LONGi Green Energy
GE Vernova
Contemporary Amperex Technology
Ørsted
Opportunities
  • Long-Duration Storage Beyond Lithium
  • Africa and South Asia Distributed Buildout
  • Asset Performance Data as a Revenue Line

Clean Energy Technology Market Summary

The Clean Energy Technology Market Market closed 2025 at roughly USD 1,182.0 billion and enters the forecast window at approximately USD 1,286.0 billion in 2026, climbing to about USD 2,905.0 billion by 2035 at a 9.4% CAGR. Two catalysts anchor that trajectory. The U.S. Inflation Reduction Act's technology-neutral 45Y and 48E credits, extended through the early 2030s, have already unlocked more than USD 200 billion in announced manufacturing and generation projects [1]. Europe's Net-Zero Industry Act, meanwhile, sets a binding 40% domestic manufacturing target for strategic clean technologies by 2030 [2].

Capital is rotating away from unabated thermal generation. Coal retirements across the OECD, combined with ageing single-cycle gas peakers, are being replaced by hybridized solar-plus-storage plants, grid-forming inverters, and long-duration chemistries that legacy dispatch models never contemplated. Global energy investment reached roughly USD 3.3 trillion in 2025, with about two-thirds flowing to clean technologies [3]. The Clean Energy Technology Market Market absorbs the equipment, systems, and integration layer of that spend.

Asia-Pacific dominates with close to 46% of global revenue, driven by Chinese and Indian deployment volumes. The same region also grows fastest, compounding at 10.8% through 2035. North America ranks second on the strength of tax-equity structures and interconnection reform. Expect the competitive centre of gravity to shift from module cost toward system integration and firm-capacity delivery.

Key Report Takeaways

• By Technology

  • Solar photovoltaic systems hold the largest slice of the Clean Energy Technology Market Market at roughly 34% of 2025 revenue
  • Hydrogen and electrolyser platforms post the steepest expansion at a 21.4% CAGR through 2035
  • Battery and grid-scale storage contributed approximately USD 168.0 billion in 2025

• By Sector

  • Utility-scale power generation commands about 52% of Clean Energy Technology Market Market demand
  • Industrial decarbonisation deployments grow at 12.6% annually across the forecast
  • Commercial and institutional buildings accounted for near USD 141.0 billion in 2025

• By Geography

  • Asia-Pacific leads the Clean Energy Technology Market Market with roughly 46% share
  • Middle East & Africa is the second-fastest riser at a 10.4% CAGR
  • Europe generated approximately USD 271.0 billion in 2025 revenue

Market Size and Forecast (2021–2035)

Figures below blend bottom-up equipment shipment tracking with top-down capital expenditure reconciliation against national energy statistics, multilateral disbursement records, and audited vendor filings. Historical years are anchored to reported installation volumes; forecast years apply project-pipeline conversion rates discounted for interconnection queue attrition and supply-chain slippage.
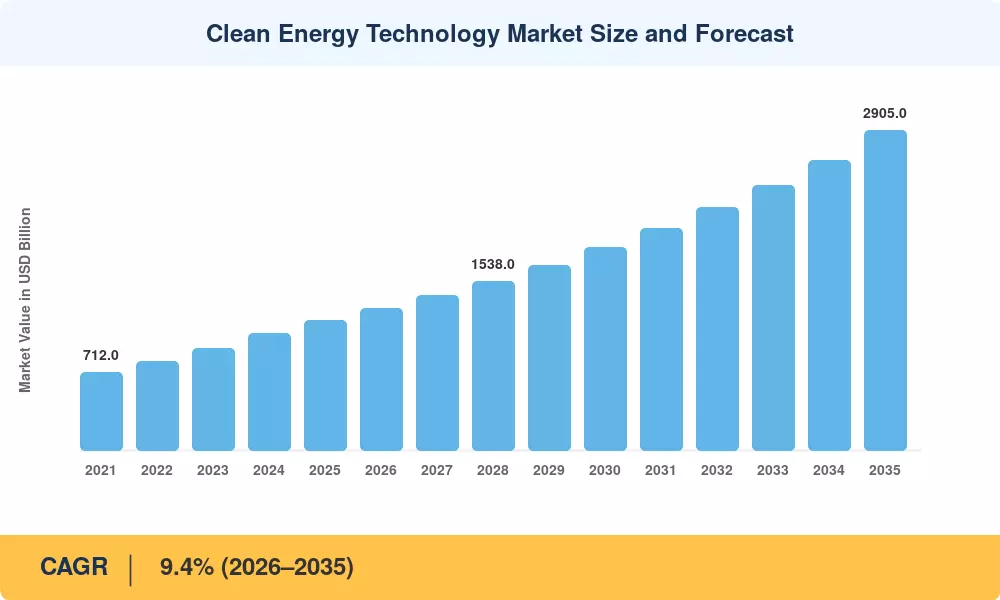
Clean Energy Technology Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Production and investment tax credits +2.1 North America, Europe Medium-term (2–4 yr)
Falling levelised cost of storage +1.8 Global Short-term (≤2 yr)
Corporate PPA and 24/7 procurement +1.4 North America, Europe, APAC Short-term (≤2 yr)
Grid modernisation and transmission capex +1.3 Global Long-term (≥4 yr)
Industrial decarbonisation mandates +1.1 Europe, Japan, Korea Long-term (≥4 yr)
Emerging-market concessional finance +0.9 Africa, South Asia, LatAm Medium-term (2–4 yr)
Data-centre load growth +0.8 North America, Nordics, APAC Short-term (≤2 yr)


Tax Credit Architecture Reshapes Project Economics

Treasury guidance on the 45X advanced manufacturing credit pays USD 35 per kilowatt-hour for domestically produced battery cells and USD 10 per kilowatt-hour for modules, which has pulled roughly USD 130 billion of announced factory investment into the United States since 2022 [1]. Developers now underwrite projects assuming credit transferability rather than traditional tax equity, compressing financing costs by an estimated 150 to 250 basis points. That single change alters the internal rate of return threshold at which marginal projects clear investment committees.

Storage Cost Curves Break Duration Barriers

Average turnkey four-hour system pricing fell below USD 165 per kilowatt-hour in 2025, down more than 40% from 2022 levels [5]. Lithium iron phosphate now dominates stationary applications on cycle-life and safety grounds, while sodium-ion pilots in China target sub-USD 100 chemistry by 2028. Utilities that once treated storage as a niche ancillary-services asset are procuring it as capacity, with more than 60 gigawatts of grid-scale awards issued globally in 2025 alone.

Corporate Demand Moves From Annual to Hourly Matching

Roughly 42% of Fortune Global 500 firms now hold active clean power contracts, and a growing subset commits to hourly carbon-free matching rather than annual netting [9]. Hourly matching materially raises technology intensity — it requires firm capacity, storage, and granular metering that annual RECs never demanded. Google, Microsoft, and Iron Mountain have all published 24/7 procurement frameworks that vendors now design against.

Data-Centre Load Rewrites Interconnection Priorities

Global data-centre electricity consumption is projected to roughly double to near 945 terawatt-hours by 2030, with AI workloads driving most of the increment [11]. Hyperscalers have responded by signing nuclear restart agreements, geothermal offtakes, and behind-the-meter solar deals at unprecedented scale. This demand shock has converted clean generation from a compliance cost into a scarce operational input.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Interconnection queue backlogs −1.6 North America, Europe Long-term (≥4 yr)
Critical mineral concentration risk −1.2 Global Medium-term (2–4 yr)
Permitting and land-use opposition −1.0 Europe, North America Long-term (≥4 yr)
Elevated cost of capital −0.9 Emerging markets Short-term (≤2 yr)
Skilled labour shortages −0.7 Global Medium-term (2–4 yr)


Queues Now Outlast Political Cycles

More than 2,300 gigawatts of generation and storage capacity sit in United States interconnection queues, with median wait times exceeding five years from request to commercial operation [7]. FERC Order 2023 imposed cluster-study reforms and firm deadlines, but transmission operators remain short of engineering staff to clear the backlog. Projects that miss credit-eligibility deadlines get repriced or abandoned outright.

Mineral Concentration Creates Single-Point Exposure

Refining for cobalt, graphite, and rare earths remains concentrated, with one country processing above 60% of global supply for several inputs [12]. Export licensing changes announced in 2023 and 2024 for graphite and gallium demonstrated how quickly cost curves can invert. Diversification programmes exist but typically require seven to ten years from discovery to qualified output.

Capital Costs Bite Hardest Where Growth Is Needed Most

Weighted average cost of capital for utility-scale solar sits near 4% in Northern Europe but exceeds 11% in parts of sub-Saharan Africa, a spread that can double levelised generation cost for identical hardware [10]. Blended finance vehicles and partial risk guarantees address part of the gap, yet concessional volumes remain roughly an order of magnitude below assessed need.

Clean Energy Technology Market Opportunities

Long-Duration Storage Beyond Lithium

Iron-air, flow, and thermal systems targeting 12 to 100 hours of discharge address a gap lithium cannot economically serve. Federal demonstration funding of roughly USD 350 million and utility pilot commitments in Minnesota and Colorado create a beachhead [15]. First-mover vendors that prove multi-day performance under real dispatch conditions will define the procurement specification.

Africa and South Asia Distributed Buildout

Roughly 685 million people still lack electricity access, concentrated in sub-Saharan Africa [10]. Mini-grid and rooftop deployment paired with mobile-money payment rails bypasses centralised grid capex entirely. Vendors offering financeable, pay-as-you-go hardware stacks capture recurring revenue that pure equipment sellers cannot.

Asset Performance Data as a Revenue Line

Operators sitting on decade-long inverter, turbine, and battery telemetry can monetise degradation models, warranty analytics, and insurance-grade performance certification. Subscription analytics carry gross margins two to three times equipment resale, and lenders increasingly require third-party verified production forecasts before disbursement.

Retrofit and Repowering of the 2010s Fleet

Over 200 gigawatts of wind and solar capacity installed before 2016 approaches end of original warranty [4]. Repowering with modern turbines or higher-efficiency modules on existing interconnection rights sidesteps queue delays entirely, offering some of the highest-return projects available anywhere.

Industrial Heat Electrification

Process heat below 400 degrees Celsius represents a large, largely unaddressed decarbonisation pool. Industrial heat pumps and electric boilers, supported by European carbon border adjustment pricing, convert an operating expense into a capital equipment sale [2].

Clean Energy Technology Market Future Outlook

Autonomous Grid Operations

Machine-learning dispatch and forecasting move from pilot to production over the next five years. Utilities deploying probabilistic forecasting report curtailment reductions in the mid-single digits, which at fleet scale translates to hundreds of millions in recovered revenue [7]. Grid-forming inverter control, not generation hardware, becomes the differentiating competence.

Firm Capacity Becomes the Priced Product

Buyers stop purchasing energy and start purchasing shaped, guaranteed delivery. That shift rewards portfolio operators who can blend solar, wind, storage, and dispatchable resources across a balancing area. Merchant developers without portfolio depth face margin compression as commodity energy prices converge toward marginal cost.

Nuclear and Firm Low-Carbon Re-Enter the Mix

More than twenty countries pledged to triple nuclear capacity by 2050, and hyperscaler power agreements have revived shuttered plants in the United States [18]. Small modular designs face first-of-a-kind cost risk, but the demand signal from industrial and data-centre buyers is now durable enough to support fleet ordering by the early 2030s.

Disclosure Regimes Convert Reporting Into Procurement

IFRS S2 and the European sustainability reporting standards push Scope 2 emissions into audited financial statements [19]. Once emissions data carries assurance liability, procurement teams demand traceable, time-stamped attributes — which in turn drives metering, registry, and verification technology spend well beyond generation hardware itself.

Regional Market Share Analysis

Region Metric Primary Investment Themes
Asia-Pacific 46.0% share Manufacturing scale, grid buildout, rooftop solar
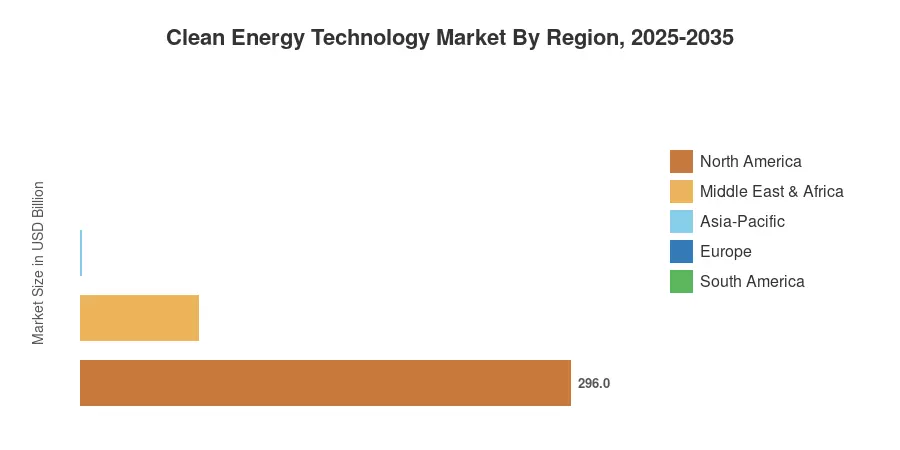
North America USD 296.0 Billion (2025) Tax credits, storage, nuclear restarts
Europe 22.9% share Offshore wind, heat pumps, industrial decarbonisation
South America 8.8% CAGR (2026–2035) Hydropower firming, distributed generation
Middle East & Africa USD 71.0 Billion (2025) Utility-scale solar, desalination coupling
Total USD 1,182.0 Billion (2025) —

The Clean Energy Technology Market Market shows sharper regional divergence than most industrial categories, because policy design rather than resource endowment sets the pace of deployment.


Asia-Pacific

Country Metric Key Driver
China 58.0% of region Manufacturing dominance and provincial quotas
India 13.2% CAGR PLI scheme and 500 GW non-fossil target
Japan USD 41.0 Billion Offshore auctions and grid reinforcement
Australia 9.6% CAGR Rooftop penetration and Capacity Investment Scheme
Rest of Asia-Pacific 9.4% of region ASEAN power purchase liberalisation


China's provincial renewable portfolio obligations, combined with a manufacturing base producing over 80% of global module capacity, make it the structural anchor of regional demand [6]. India's Production Linked Incentive scheme has committed roughly USD 3 billion to domestic module and cell fabrication while ALMM listing rules restrict imported content in government-linked tenders. Japan's third offshore round awarded sites at strike prices well below earlier expectations, signalling supply-chain maturity.

North America

Country Metric Key Driver
United States 84.0% of region IRA credit stack and data-centre load
Canada USD 34.0 Billion Clean Electricity Regulations and hydro exports
Mexico 10.1% CAGR Nearshoring industrial demand


Credit transferability provisions have created a secondary market estimated above USD 25 billion annually, letting developers monetise incentives without traditional tax-equity partners [1]. Canada's investment tax credits for clean electricity and hydrogen mirror the U.S. structure at lower headline rates but with labour-condition bonuses. Mexican demand tracks manufacturing relocation more than energy policy, which makes it unusually sensitive to trade posture.

Europe

Country Metric Key Driver
Germany 24.0% of region EEG auctions and heat pump subsidy
United Kingdom USD 47.0 Billion Contracts for Difference AR rounds
France 7.9% CAGR Nuclear extension plus solar buildout
Netherlands 5.8% of region Offshore wind and hydrogen backbone
Rest of Europe 8.6% CAGR Nordic industrial electrification


REPowerEU redirected roughly EUR 300 billion toward supply diversification and accelerated permitting, with member states required to designate renewables acceleration areas carrying presumptive approval [2]. Germany's heat pump subsidy covers up to 70% of installation cost for lower-income households, converting a policy target into consumer economics. The United Kingdom's allocation rounds have stabilised after the 2023 offshore round attracted no bids at the prevailing administrative strike price.

South America

Country Metric Key Driver
Brazil 61.0% of region Distributed generation law and wind auctions
Chile 9.7% CAGR Solar resource quality and mining demand
Colombia USD 4.1 Billion Grid diversification away from hydrology risk
Rest of South America 8.1% CAGR Regional interconnection projects


Brazil's distributed generation framework grandfathered net-metering economics for existing installations while phasing in grid fees, producing a rush of installations ahead of deadline [16]. Chilean mining operators sign long-tenor clean supply agreements to protect copper export competitiveness against carbon-border pricing. Hydrological volatility in Colombia has moved firm renewable capacity from optional to essential.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 31.0% of region NREP tenders and Vision 2030 targets
United Arab Emirates USD 16.0 Billion Masdar pipeline and nuclear baseload
South Africa 11.2% CAGR Load-shedding response and REIPPPP rounds
Rest of Middle East & Africa 10.6% CAGR Mini-grid access programmes


Saudi Arabia's National Renewable Energy Program has awarded projects at some of the lowest recorded solar tariffs globally, underwritten by sovereign offtake and low-cost land [17]. South Africa's private generation licensing threshold removal unlocked a wave of self-build industrial projects that bypass the state utility entirely. Access-focused mini-grid programmes across East Africa increasingly attract commercial rather than purely concessional capital.

Clean Energy Technology Market By Region, 2025-2035

Clean Energy Technology Market Segmentation

By Technology

The Clean Energy Technology Market Market segments by generation and enabling technology as follows.

Segment Metric Primary Demand Driver
Solar Photovoltaic 34.0% share Cost leadership and modularity
Wind (Onshore & Offshore) USD 248.0 Billion Auction pipelines and repowering
Energy Storage Systems 14.2% share Firming and ancillary revenue
Hydrogen & Electrolysers 21.4% CAGR Industrial feedstock substitution
Carbon Capture & Utilisation 18.9% CAGR Hard-to-abate compliance
Nuclear & Advanced Reactors USD 96.0 Billion Baseload and data-centre offtake
Bioenergy & Geothermal 6.1% share Dispatchable renewable niche


Solar retains leadership on installed volume rather than price, since module deflation has compressed revenue per watt even as shipments rise. The value pool is migrating downstream toward trackers, inverters, and engineering services. Storage is the second story: attach rates on new utility solar in leading markets now exceed 55%, and the technology has stopped being an add-on and started being a design assumption.

By Sector

Segment Metric Primary Demand Driver
Utility-Scale Power 52.0% share Portfolio standards and auctions
Industrial Decarbonisation 12.6% CAGR Carbon pricing and border adjustment
Commercial & Institutional USD 141.0 Billion Corporate net-zero commitments
Residential 11.8% share Rooftop and heat pump adoption
Transport & Charging Infrastructure 13.9% CAGR Fleet electrification mandates


Utility-scale demand remains the volume engine, though its share erodes slowly as distributed and industrial applications scale faster. Industrial buyers behave differently from utilities — they optimise for delivered heat and process reliability rather than levelised cost, which favours vendors selling integrated outcomes over component suppliers.

By End User

Segment Metric Primary Demand Driver
Independent Power Producers 38.0% share Merchant and contracted development
Regulated Utilities USD 331.0 Billion Rate-base capital deployment
Industrial Corporates 12.9% CAGR Direct procurement and self-generation
Government & Public Sector 14.0% share Public building retrofit programmes
Households & Prosumers 10.7% CAGR Net metering and self-consumption


Independent power producers dominate because they absorb development risk that regulated entities cannot rate-base. Regulated utilities, though, are accelerating: transmission and distribution capital plans filed across major North American and European jurisdictions imply sustained double-digit annual increases through 2030.

Competitive Benchmarking

Concentration in the Clean Energy Technology Market Market is moderate and uneven by technology tier. An estimated Herfindahl-Hirschman Index near 620 across the aggregate market masks near-oligopoly conditions in offshore turbines and electrolyser stacks alongside genuine fragmentation in EPC and distributed installation. The top five participants control roughly 27% of global revenue, leaving a long tail of regional specialists competing on execution and local content compliance rather than technology differentiation.

Company Est. Revenue Share Range Key Offerings for Clean Energy Technology Market Market Strategic Positioning
Siemens Energy ~6–9% Turbines, grid technology, electrolysers Integrated grid and generation platform
Vestas Wind Systems ~5–8% Onshore and offshore wind, service contracts Service-annuity led model
LONGi Green Energy ~5–7% High-efficiency modules and cells Cost and efficiency leadership
GE Vernova ~4–7% Wind, gas, electrification, grid software Diversified transition portfolio
Contemporary Amperex Technology ~4–6% Grid-scale battery systems Chemistry and scale advantage
Ørsted ~3–5% Offshore wind development and operation Pure-play developer-operator
Schneider Electric ~3–5% Microgrid controls, energy management Digital and software attach
First Solar ~2–4% Thin-film modules, domestic content Policy-advantaged manufacturing
Enphase Energy ~2–3% Microinverters, residential storage Distributed and prosumer focus
Nordex Group ~2–3% Onshore turbines, project services Regional cost competitiveness


Recent News & Developments

  • U.S. Department of the Treasury (January 2025): Finalised technology-neutral clean electricity credit rules, resolving eligibility ambiguity that had stalled several gigawatts of hybrid project financings [1]
  • European Commission (February 2024): Adopted the Net-Zero Industry Act, setting a 40% domestic manufacturing benchmark and introducing non-price resilience criteria into public auctions [2]
  • Constellation Energy (September 2024): Announced a twenty-year power agreement supporting the restart of a shuttered Pennsylvania nuclear unit for hyperscaler load, reframing nuclear as a commercial product [18]
  • India Ministry of New and Renewable Energy (March 2024): Expanded ALMM enforcement to cover solar cells from mid-2026, accelerating domestic cell fabrication commitments [20]
  • Ørsted (November 2023): Ceased development on two U.S. offshore projects and recorded significant impairments, triggering an industry-wide repricing of offshore contract structures [21]
  • Saudi Power Procurement Company (July 2024): Awarded multi-gigawatt solar and wind tranches under the National Renewable Energy Program at tariffs among the lowest globally recorded [17]
  • FERC (July 2023): Issued Order 2023 mandating cluster study processes and penalties for transmission provider delays, the most consequential interconnection reform in two decades [7]
  • Brookfield and Infrastructure Partners (May 2025): Closed a multi-billion transition fund allocation targeting grid infrastructure and storage platforms across OECD markets

Clean Energy Technology Market Report Scope

Parameter Detail
Market Scope Global generation, storage, grid, hydrogen, carbon management, and enabling clean energy technologies
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 9.4% (2026–2035)
Market Size Checkpoints USD 1,182.0 Billion (2025); USD 1,841.0 Billion (2030); USD 2,905.0 Billion (2035)
Fastest Growing Segments Hydrogen & Electrolysers (technology); Transport & Charging Infrastructure (sector); Asia-Pacific (region)
Companies Profiled Siemens Energy, Vestas, LONGi, GE Vernova, CATL, Ørsted, Schneider Electric, First Solar, Enphase, Nordex
Valuation Currency USD, constant 2025 prices

FAQs

How should procurement teams structure warranty terms when buying into the Clean Energy Technology Market Market?
Tie warranty coverage to measured availability rather than nameplate capacity, and require parent-company guarantees where the supplying entity is a project-specific subsidiary. Escrowed spare-parts provisions protect against vendor insolvency, which has affected several storage integrators .
What due diligence gaps most often surface in Clean Energy Technology Market Market acquisitions?
Interconnection agreement transferability and land lease renewal terms are the most frequently mispriced items. Buyers also underestimate curtailment exposure in congested nodes, where actual delivered output can trail modelled output by double digits [7].
Which technology comparison matters most for a buyer choosing storage chemistry?
Compare cycle life at realistic depth of discharge, not headline energy density. Lithium iron phosphate wins on stationary economics and thermal safety, while nickel-based chemistries retain advantages only where footprint is severely constrained [5].
How do local content rules change vendor selection in the Clean Energy Technology Market Market?
Domestic content thresholds convert sourcing into a financing variable, since missing them forfeits bonus credit percentages. Require suppliers to provide auditable component-origin documentation before contract signature, not at delivery [1].
What integration challenge is most underestimated in hybrid projects?
Control system interoperability between inverters, battery management, and utility SCADA. Mismatched communication protocols routinely delay commissioning by months and are rarely allocated clearly in EPC contracts [23].
Are there emerging use cases worth tracking beyond conventional generation?
Yes — behind-the-meter industrial heat, demand-flexibility aggregation for data centres, and desalination coupled to variable renewables. Each converts intermittency from a liability into a schedulable process input [11].
How should investors think about policy reversal risk?
Weight contracted revenue over incentive-dependent revenue when valuing assets. Projects with investment-grade offtake survive policy change; those relying primarily on subsidy capture do not [24].
Author
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.



















