Brick Carton Packaging Market (2026 - 2035)

Brick Carton Packaging Market Research Report Information By Material (Paperboard, Low-Density Polyethylene (LDPE), Aluminum Foil, and Other Materials), By Opening/Closure Type (Cut, Clip, Twist Cap, and Straw Hole), By Filling Volume (Less Than 250 Ml, 250 – 500 Ml, and More Than 500 Ml), and By End-User Industry (Food and Beverages, Pharmaceuticals, Personal Care and Cosmetics, and Other End-User Industries) – Forecast Till 2035
ID: MRFR/PCM/10325-HCR 111 Pages Snehal Singh Last Updated: September 24, 2026
Brick Carton Packaging Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.68%
2025 Market SizeUSD 12.90 Billion
2035 Market SizeUSD 24.53 Billion
Key Players
Tetra Pak International S.A.
SIG Group AG
Elopak ASA
Greatview Aseptic Packaging
Nippon Paper Industries
Novolex
Opportunities
  • Ambient Dairy and School Nutrition in Emerging Markets
  • Connected Packs and Data-Driven Business Models
  • Water, Wine, and New Liquid Categories

Brick Carton Packaging Market Summary

The global Brick Carton Packaging Market was valued at USD 12.90 Billion in 2025. It is forecast to reach USD 13.71 Billion in 2026 and USD 24.53 Billion by 2035, a CAGR of 6.68% over 2026–2035. Two catalysts anchor that trajectory. The EU Packaging and Packaging Waste Regulation (PPWR) entered into force in February 2025 and requires all packaging placed on the EU market to be recyclable by 2030 [1]. Tetra Pak has also committed roughly €100 million a year to fiber-based materials and barrier development [2].

Material technology inside the pack is changing. For decades, a thin aluminum layer has given long ambient shelf life. Converters are now replacing it with polymer and fiber-based barriers, and SIG sells an aluminum-free full-barrier structure containing around 80% paperboard [3]. Filling lines are changing in parallel. Mechanical changeovers are giving way to servo-driven, digitally monitored systems that switch pack volumes in minutes rather than hours.

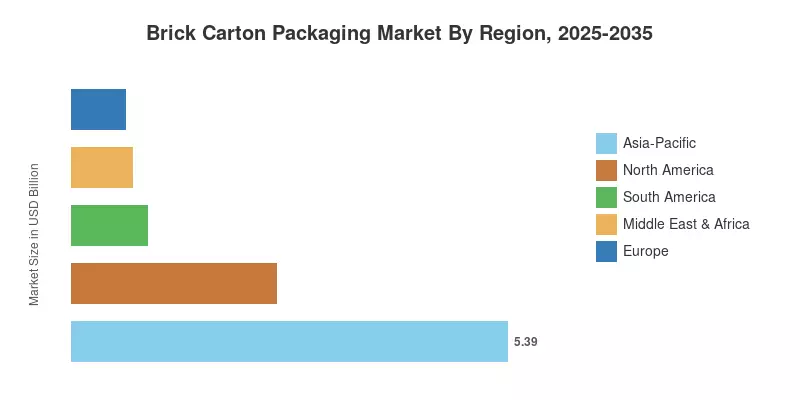
Asia-Pacific leads with a 41.8% share in 2025. It is also the fastest-growing region, with a projected 7.4% CAGR in shelf-stable dairy and juice demand in China, India, and ASEAN. Europe ranks second, supported by mature collection systems and PPWR compliance spending. Over the next decade, barrier chemistry and recyclability grading will shape supplier selection as much as unit price.

Key Report Takeaways

• By Material

  • Paperboard holds a 58.6% share of the Brick Carton Packaging Market in 2025 because it is the structural layer in nearly every commercial specification
  • Aluminum Foil is the fastest-growing material at an 8.67% CAGR as high-barrier soups, broths, and infant nutrition expand

• By Opening/Closure Type

  • Twist Cap closures account for a 37.6% share, driven by resealable multi-serve milk and juice packs
  • Straw Hole formats expand at a 7.65% CAGR on children's drinks and single-serve nutrition

• By Filling Volume

  • More Than 500 Ml packs command a 48.3% share, supported by household bulk purchasing
  • 250 – 500 Ml formats generate USD 3.64 Billion in 2025 across impulse and lunchbox occasions

• By End-User Industry

  • Food and Beverages represents 59.7% of the Brick Carton Packaging Market in 2025, led by UHT dairy and juice
  • Personal Care and Cosmetics grows at an 8.1% CAGR as refill and low-plastic formats gain retail listings

• By Region

  • Asia-Pacific holds a 41.8% share of ambient dairy consumption
  • North America generates USD 2.53 Billion, anchored by plant-based drinks and broths
  • Europe grows at a 5.21% CAGR under PPWR-driven specification changes

Market Size and Forecast (2021–2035)

Market Research Future sized the Brick Carton Packaging Market with a bottom-up model. It combines converter shipment data, filings from leading carton suppliers, and filler installed-base estimates, then cross-checks the result against top-down consumption data for milk, juice, and plant-based drinks. Historical values for 2021–2024 are reconciled against published annual reports [2][3][4]. Forecast values apply calibrated regional growth rates to the 2025 base year.
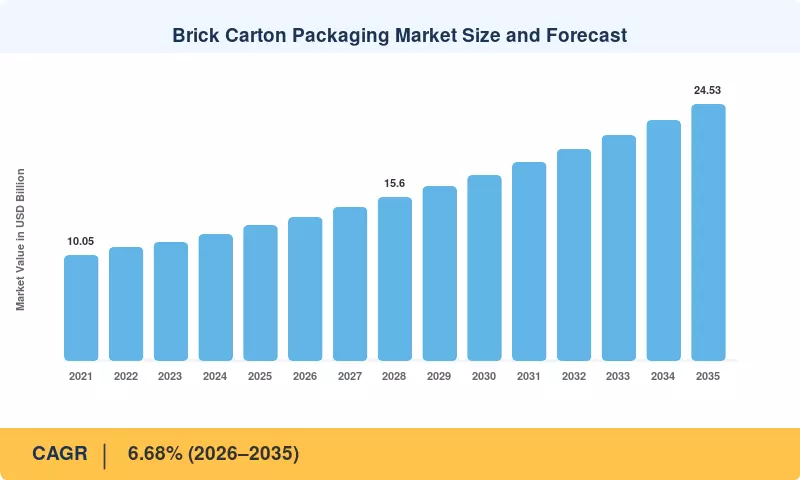
Brick Carton Packaging Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Plastic Reduction and EPR Mandates Favoring Fiber-Based Formats +1.3% Europe, Asia-Pacific, North America Medium term (2–4 yr)
Shelf-Stable Dairy Demand in Ambient-Chain Markets +1.2% Asia-Pacific, Middle East & Africa, South America Long term (≥4 yr)
Urbanization and Single-Serve Consumption +0.9% Asia-Pacific, South America Long term (≥4 yr)
Plant-Based and Functional Beverage Expansion +0.8% North America, Europe Short term (≤2 yr)
Aluminum-Free Barrier Innovation +0.7% Global, early gains in Europe Medium term (2–4 yr)
Filling-Line Automation and Digital Printing +0.5% Global Short term (≤2 yr)


Plastic Reduction and EPR Mandates Favoring Fiber-Based Formats

Regulation (EU) 2025/40 [1] establishes per-capita packaging waste reduction targets of 5% by 2030, 10% by 2035, and 15% by 2040 based on a 2018 baseline. Fees are growing more diverse in national EPR programs, with fibre-dominant packs seeing lower charges than multi-material plastics. India’s updated Plastic Waste Management Rules mandate brand owners to use 30% recycled content in rigid plastic packaging from 2025–26 [8]. Those expenses are prompting brands to switch juice and dairy SKUs away from PET and HDPE, and onto paperboard bricks.


Shelf-Stable Dairy Demand in Ambient-Chain Markets

The OECD-FAO Agricultural Outlook forecasts global milk production to expand by roughly 1.6% annually through 2033, with India and Pakistan driving over half of this growth [5]. A significant portion of this volume travels through retail networks lacking dependable refrigeration, making aseptic brick packaging essential for keeping UHT milk shelf-stable for months. Southern Europe illustrates the ultimate destination of this trend, as UHT heavily dominates liquid milk sales in Spain and Portugal. Comparable shifts happening across South Asia, Southeast Asia, and Africa are generating steady, volume-driven demand.


Urbanization and Single-Serve Consumption

The United Nations projects that 68% of the world's population will live in cities by 2050, up from 55% in 2018 [6]. Smaller households and longer commutes favor 125–250 ml portions that cost less per unit and fit school and convenience channels. China's 2020 plastics directive banned non-degradable straws in catering by the end of that year [9]. The ban pushed straw-fit designs toward paper straws and straw-free openings rather than away from bricks.

Plant-Based and Functional Beverage Expansion

Plant-based milk accounts for roughly 15% of US retail milk dollar sales [24], and almost all oat, almond, and soy drinks ship in ambient bricks. Brand owners keep extending into protein shakes, cold coffee, and fortified juices. Each new SKU needs a short print run and a compatible filling slot. That favors carton suppliers that can offer both flexible fillers and digital decoration to challenger brands without large minimum orders.

Aluminum-Free Barrier Innovation

A standard ambient pack is roughly 75% paperboard, 20% polymer, and 5% aluminum by weight [2]. The foil layer complicates fiber recovery at paper mills. SIG's aluminum-free full-barrier material raises paperboard content to around 80% [3]. Tetra Pak has run commercial validations of a paper-based barrier in Portugal [2]. These structures cut the carbon footprint of the pack and simplify recycling, helping carton suppliers defend share against flexible pouches in European retail tenders.

Filling-Line Automation and Digital Printing

High-speed ambient fillers now exceed 20,000 packs per hour, and servo-driven volume changeovers let one line serve several formats [2]. Digital printing removes plate costs, making runs of a few thousand packs viable for regional promotions and limited editions [3]. For co-packers, these capabilities raise line utilization and reduce changeover scrap. That improves the business case for moving products out of rigid plastics.

Restraints Impact Analysis

Restraint impacts are shown as negative directional adjustments to the forecast CAGR. As with the drivers, they overlap and should not be summed. Each reflects the drag Market Research Future expects the constraint to exert on the Brick Carton Packaging Market if it remains unresolved.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Recycling Infrastructure Gaps for Multilayer Packs −0.7% Asia-Pacific, South America, Middle East & Africa Long term (≥4 yr)
Paperboard and Pulp Price Volatility −0.6% Global Short term (≤2 yr)
Substitution by PET Bottles and Flexible Pouches −0.5% Global Medium term (2–4 yr)
Aluminum Foil Supply Tightness −0.4% Global, acute in Europe Short term (≤2 yr)
Barrier Chemistry and Food-Contact Compliance Costs −0.3% Europe, North America Medium term (2–4 yr)


Recycling Infrastructure Gaps for Multilayer Packs

The World Bank estimates that low-income nations collect only 39% of their municipal waste [7]. Dedicated pulpers are needed to separate fiber from polymer and foil. Over 80% of paper-based packaging is recovered in Europe [13], while over 62% of US households are able to recycle cartons [11]. However, collecting is still quite low across much of Asia, Latin America, and Africa. This undermines assertions about recyclability under future grading schemes.


Paperboard and Pulp Price Volatility

Between 2022 and 2024, mill closures, logistical shocks, and new South American capacity all moved in opposing directions, causing market pulp prices to fluctuate by more than a quarter [16]. Suppliers of carton board transmit these costs on with a lag, which puts pressure on converter margins during times of declining prices and drives up pack prices during times of rising costs. The biggest fluctuations are absorbed by small dairies with annual contracts.


Substitution by PET Bottles and Flexible Pouches

PET bottles and jars reached a 29.1% recycling rate in the US [12], and food-grade recycled PET supply keeps improving. Rising recycled content strengthens PET's environmental case with retailers. Stand-up pouches, meanwhile, use less material per litre. For premium juices and dairy drinks, transparent bottles also let shoppers see the product, which bricks cannot offer.

Aluminum Foil Supply Tightness

LME aluminum averaged above USD 2,400 per tonne in 2024 [25]. European smelter curtailments after the 2022 energy crisis reduced regional primary supply [15]. Thin-gauge foil for barrier laminates requires specialized rolling capacity, and only a handful of mills qualify. Lead times lengthened, prompting converters to dual-source or accelerate aluminum-free trials.

Barrier Chemistry and Food-Contact Compliance Costs

PPWR restricts PFAS in food-contact packaging above set thresholds from August 2026 [1]. California's SB 54 requires all covered packaging to be recyclable or compostable by 2032 [10]. Each new rule forces reformulation, migration testing, and requalification on customer filling lines. Those costs weigh hardest on smaller converters without in-house material laboratories.

Brick Carton Packaging Market Opportunities

Ambient Dairy and School Nutrition in Emerging Markets

School milk programmes reach about 160 million children worldwide, according to the FAO [23]. Most served portions are 125–200 ml ambient packs. Expansion of these programmes in South Asia, Sub-Saharan Africa, and Southeast Asia represents one of the largest untapped volume pools in the Brick Carton Packaging Market. Suppliers that combine low-cost filling equipment with local material conversion can win multi-year public tenders.

Connected Packs and Data-Driven Business Models

Unique digital codes printed on each pack enable traceability, anti-counterfeiting, loyalty programmes, and first-party consumer data for brand owners [2]. The same line-side data supports equipment-as-a-service contracts, where fillers pay per pack produced rather than buying machinery outright. Both models shift supplier revenue toward recurring streams and deepen customer lock-in.

Water, Wine, and New Liquid Categories

Consumer goods companies have pledged to cut virgin plastic use under the Ellen MacArthur Foundation's Global Commitment [14]. That creates openings for bricks in still water, boxed wine, cooking oils, and liquid detergents. These categories carry higher margins per pack than commodity milk and help converters use capacity in mature markets.

Bio-Based Polymers and Plant-Based Closures

Sugarcane-derived polyethylene for closures and laminate layers lets brands claim higher renewable content without changing filling equipment [2]. Retailers in Europe and Japan increasingly score suppliers on renewable content. That gives early adopters a pricing premium in private-label tenders.

Closed-Loop Recycling Partnerships

Stora Enso's dedicated line in Poland for recycling used cartons shows how board producers can turn post-consumer packs into feedstock [19]. Converters that co-invest in such capacity secure recycled fiber and credible end-of-life claims. They also gain a hedge against EPR fee increases.

Brick Carton Packaging Market Future Outlook

Fiber-Dominant Structures Replace Foil

By the early 2030s, Market Research Future expects aluminum-free structures to move from pilot to default for chilled and medium-barrier ambient products in Europe. SIG and Tetra Pak have already commercialized paper-rich barriers [2][3]. Brands tracking Global Commitment targets will specify them in new tenders [14]. Foil will remain in high-barrier niches such as infant formula and low-acid soups.

Digital Operations on the Filling Line

Remote monitoring, predictive maintenance, and AI-assisted quality inspection are becoming standard in new filler contracts [2]. Suppliers will compete on uptime guarantees and pay-per-pack pricing as much as on material cost. Converters without software capability risk being reduced to price-takers in the Brick Carton Packaging Market.

Recyclability Grading and Producer Fees

PPWR allows only packaging graded A, B, or C for recyclability from 2030, and only A or B from 2038 [1]. EPR fees will be tied to those grades. Suppliers that document fiber yield at real mills will win share as retailers standardize sustainable packaging scorecards across the EU and, later, California [10].

Demand Geography and Demographics

Global municipal waste is projected to rise from 2.01 billion tonnes in 2016 to 3.40 billion tonnes by 2050 [7], and urbanization reaches 68% [6]. Both trends concentrate demand where collection systems are weakest. Growth will tilt toward South Asia and Africa [5], where supplier investment in local recycling will increasingly condition tender access.

Regional Market Share Analysis

Region Key Metric (2025 share, 2025 USD, or 2026–2035 CAGR) Primary Investment Themes
North America USD 2.53 Billion Plant-based drinks, broths, SB 54 compliance
Europe 5.21% CAGR PPWR recyclability, aluminum-free barriers
Asia-Pacific 41.8% share UHT dairy growth, local converter capacity
South America USD 0.94 Billion Long-life milk, school feeding
Middle East & Africa 5.9% share Ambient dairy, food security programmes
Total USD 12.90 Billion —

Regional demand in the Brick Carton Packaging Market depends on two variables. The first is the share of milk and juice sold through ambient channels. The second is the maturity of collection systems, which increasingly determines regulatory treatment.


North America

Country Key Metric Key Driver
US 71.5% of region Plant-based and broth SKUs
Canada USD 0.33 Billion Provincial EPR programmes
Mexico 6.1% CAGR UHT milk dominance

Plant-based drinks, broths, and school milk anchor US demand. Mexico supplies much of the region's volume growth because shelf-stable UHT milk dominates its retail dairy aisle. Policy is tightening on plastics: California's SB 54 mandates full recyclability or compostability by 2032 and a 25% cut in single-use plastic packaging [10]. Novolex's 2025 acquisition of Pactiv Evergreen brought a major domestic carton converter under new ownership [17].


Europe

Country Key Metric Key Driver
Germany 21.4% of region VerpackG fee modulation
UK USD 0.44 Billion Plant-based drink demand
France 14.2% of region Anti-waste law plastic phase-down
Italy 4.6% CAGR UHT milk and passata
Spain USD 0.30 Billion UHT-dominant dairy
Nordic Countries 5.9% CAGR Fiber integration, low-carbon specs
Russia 6.8% of region Domestic converter substitution
Rest of Europe USD 0.52 Billion Central European dairy consolidation

Europe has the most mature collection systems and the heaviest regulatory load. PPWR's recyclability grading and PFAS limits reshape specifications from 2026 onward [1]. Germany's VerpackG licensing fees and the Nordic countries' fiber supply chains support premium, low-carbon structures. Spain and Italy remain UHT-heavy dairy markets. Russia's supply base has localized since international suppliers exited in 2022.


Asia-Pacific

Country Key Metric Key Driver
China 38.6% of region National dairy group volumes
India 9.8% CAGR Organized dairy and EPR
Japan USD 0.71 Billion Tea, juice, soy drinks
South Korea 5.2% of region Convenience-store single-serve
ASEAN 8.4% CAGR Flavored and school milk
Rest of Asia-Pacific USD 0.62 Billion Australia and Pakistan dairy

China is the largest single-country market. It is built on UHT milk and dairy drinks from national dairy groups, served by domestic suppliers of aseptic cartons such as Greatview alongside global players [20]. India grows fastest in the region as organized dairy expands and EPR rules push brand owners away from multilayer plastics [8]. Japan favors chilled gable-tops for milk but uses bricks widely for tea, juice, and soy drinks, a niche where Nippon Paper is active [18]. ASEAN demand centers on flavored and school milk in 110–180 ml packs.


South America

Country Key Metric Key Driver
Brazil 58.3% of region Long-life milk culture
Argentina USD 0.13 Billion Dairy export cycles
Rest of South America 6.4% CAGR School and convenience channels

Brazil dominates regional consumption because shelf-stable "longa vida" milk is the standard household format, making it one of the world's largest UHT markets. Argentina's demand tracks dairy output and currency cycles, which periodically raise the cost of imported barrier materials. In Chile, Colombia, and Peru, juice and dairy brands are adopting 200 ml packs for school channels, while waste cooperatives slowly add multilayer collection [7].


Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 24.7% of region Integrated dairy producers
UAE 7.6% CAGR Re-export and hospitality
South Africa USD 0.14 Billion Established recycling chain
Egypt 8.1% CAGR Population-driven dairy demand
Rest of MEA 22.5% of region School feeding programmes

Hot climates and patchy cold chains make ambient packs the default for milk and juice across the Gulf. Saudi Arabia leads, with vertically integrated dairy producers supplying domestic and GCC demand under Vision 2030 food-security goals. Egypt and the UAE grow fastest on population growth and re-export activity. School feeding schemes across Africa offer long-term volume upside [23].


Brick Carton Packaging Market By Region, 2025-2035

Brick Carton Packaging Market Segmentation

By Material

In the Brick Carton Packaging Market, material choice decides barrier performance, recyclability grade, and cost. Paperboard supplies stiffness and printability and holds the majority of value. Low-Density Polyethylene (LDPE) forms the inner and outer sealing layers. Aluminum Foil grows fastest despite substitution pressure because high-barrier soups, broths, and infant formulas expand quicker than the overall market. Other Materials, including EVOH and bio-based polymers, are gaining trial volume as brands test foil-free structures [3].

Segment Key Metric Primary Demand Driver
Paperboard 58.6% share Structural layer in every specification
Low-Density Polyethylene (LDPE) USD 2.84 Billion Heat-seal and moisture barrier
Aluminum Foil 8.67% CAGR High-barrier ambient foods
Other Materials 7.9% share EVOH and bio-based barrier trials


By Opening/Closure Type

Across the Brick Carton Packaging Market, closure choice follows consumption occasion. Twist Cap leads because families want resealable, leak-resistant packs for multi-serve milk, juice, and plant-based drinks. Straw Hole grows fastest as children's drinks, school milk, and functional shots multiply single-serve SKUs. Cut openings remain the low-cost choice for cooking products and value dairy. Clip closures serve premium juices and ready-to-drink coffee, where tamper evidence matters.

Segment Key Metric Primary Demand Driver
Cut USD 3.35 Billion Low-cost value and cooking packs
Clip 14.4% share Premium juices and coffee
Twist Cap 37.6% share Resealable multi-serve formats
Straw Hole 7.65% CAGR Single-serve and school milk


By Filling Volume

Pack size in the Brick Carton Packaging Market reflects household economics. More Than 500 Ml leads because families buy one-litre packs to reduce per-serving cost, and these packs palletize efficiently for club and grocery channels. Less Than 250 Ml grows fastest in urban single-person households, school programmes, and premium protein and coffee drinks. The 250 – 500 Ml tier bridges impulse purchases and lunchbox occasions without steep per-litre premiums.

Segment Key Metric Primary Demand Driver
Less Than 250 Ml 7.31% CAGR Single-serve and school channels
250 – 500 Ml USD 3.64 Billion Impulse and lunchbox occasions
More Than 500 Ml 48.3% share Household bulk purchasing


By End-User Industry

End-user demand in the Brick Carton Packaging Market remains anchored in Food and Beverages, where UHT milk, juice, broths, and plant-based drinks depend on ambient shelf life. Personal Care and Cosmetics grows fastest from a small base, as refill formats for shampoo and body wash reduce rigid plastic use. Pharmaceuticals use bricks for oral nutrition and clinical liquids. Other End-User Industries include household chemicals and pet food.

Segment Key Metric Primary Demand Driver
Food and Beverages 59.7% share UHT dairy, juice, plant-based drinks
Pharmaceuticals USD 2.19 Billion Clinical and oral nutrition
Personal Care and Cosmetics 8.1% CAGR Refill formats replacing rigid plastic
Other End-User Industries 14.8% share Household liquids and pet food


Competitive Benchmarking

The Brick Carton Packaging Market shows low overall concentration despite a clear global leader. Market Research Future estimates the Herfindahl-Hirschman Index in the 850–1,050 range, below the 1,500 threshold commonly used for unconcentrated markets. The top five suppliers hold an estimated 42–51% combined share. A long tail of Chinese, Indian, and European converters supplies materials compatible with third-party fillers, and competition centers on equipment bundling, barrier innovation, and cost per pack.

Company Est. Revenue Share Range Key Offerings for Brick Carton Packaging Market Strategic Positioning
Tetra Pak International S.A. ~24–28% Tetra Brik Aseptic, Tetra Prisma Aseptic, fillers and services Global leader bundling equipment, material, and service; paper-based barrier R&D
SIG Group AG ~8–11% Sleeve-fed aseptic bricks, aluminum-free full-barrier structures Flexible-volume fillers and fiber-rich materials
Elopak ASA ~4–6% Pure-Pak cartons, aseptic Pure-Pak formats Renewable-polymer focus, US capacity expansion
Greatview Aseptic Packaging ~3–5% Roll-fed brick materials compatible with third-party fillers Cost-competitive alternative in China and emerging markets
Nippon Paper Industries ~2–4% Board and carton systems for juice and tea Integrated Japanese board-to-pack supplier
Novolex (Pactiv Evergreen) ~2–4% Fresh and extended-shelf-life cartons, board North American converter scale
Stora Enso ~2–3% Carton board supply, carton recycling capacity Upstream fiber and circularity partner
Uflex Ltd. (Asepto) ~1–2% Aseptic brick materials Indian domestic supply and export
Lami Packaging (Kunshan) ~1–2% Filler-compatible brick materials Price-focused Chinese converter
Xinjufeng Pack ~1–2% Aseptic brick and pillow materials Regional Chinese dairy supplier
IPI S.r.l. ~1–2% Aseptic brick materials and filling systems Niche European equipment-plus-material provider


Recent News & Developments

  • European Union (January 2025): Regulation (EU) 2025/40 was published in the Official Journal and entered into force in February 2025, setting recyclability grades and PFAS limits that will redefine pack specifications [1]
  • Novolex (April 2025): Completed its acquisition of Pactiv Evergreen, consolidating a major North American carton and board converter into a broader packaging group [17]
  • CalRecycle (2025): Advanced rulemaking for SB 54, clarifying how producers must document recyclability and source reduction ahead of the 2032 deadlines [10]
  • India MoEFCC (March 2024): Notified the Plastic Waste Management (Amendment) Rules, 2024, tightening EPR registration and reporting for brand owners [8]
  • SIG (2024): Expanded commercial rollout of its aluminum-free full-barrier material with around 80% paperboard content [3]
  • Stora Enso (2024): Started its dedicated line in Poland for recycling used cartons into fiber feedstock [19]
  • Elopak (2024): Advanced construction of its first US converting plant in Little Rock, Arkansas, to supply North American dairy and juice customers [4]
  • Tetra Pak (2023): Began a commercial technology validation of a paper-based barrier with Portuguese dairy Lactogal, replacing the aluminum layer [2]

Brick Carton Packaging Market Report Scope

Parameter Details
Market Scope Global Brick Carton Packaging Market by Material, Opening/Closure Type, Filling Volume, End-User Industry, and Region
Study Period 2021–2035 (Historical: 2021–2024; Base Year: 2025; Forecast: 2026–2035)
CAGR 6.68% (2026–2035)
Market Size checkpoints USD 12.90 Billion (2025); USD 13.71 Billion (2026); USD 17.76 Billion (2030); USD 24.53 Billion (2035)
Fastest Growing Segments Aluminum Foil; Straw Hole; Less Than 250 Ml; Personal Care and Cosmetics
Companies Profiled Tetra Pak, SIG Group, Elopak, Greatview Aseptic Packaging, Nippon Paper Industries, Novolex (Pactiv Evergreen), Stora Enso, Uflex (Asepto), Lami Packaging, Xinjufeng Pack, IPI S.r.l.
Valuation Currency USD Billion
CAGR Driver Disclaimer Driver and restraint impacts are directional estimates; they overlap and do not sum to the forecast CAGR

FAQs

How should buyers compare aluminum-free structures when sourcing for the Brick Carton Packaging Market?
Request oxygen transmission data, accelerated shelf-life results, and heat-seal trials on your own filling line before switching. Aluminum-free laminates suit juice and chilled dairy well, but light-sensitive or low-acid ambient products may still need foil-level protection [3].
What does filler-and-material lock-in mean for procurement in the Brick Carton Packaging Market?
Leading suppliers design fillers around their own packaging material, so supply contracts often run for several years. Buyers in the Brick Carton Packaging Market should price service, spare parts, and exit terms alongside unit pack cost [2].
Can brick cartons hold carbonated beverages?
No. Carton walls cannot withstand carbonation pressure, so sparkling drinks stay in cans, glass, and PET. Brick formats serve still liquids only, where the Brick Carton Packaging Market competes on pallet efficiency and ambient shelf life [2].
Which certifications do retailers expect from brick carton suppliers?
Most large retailers require FSC or PEFC chain-of-custody certification for the paperboard and documented food-contact compliance for polymer layers. Certified chain of custody lets brands print a verified responsible-forestry label on each pack [21].
How long do aseptic brick products stay shelf-stable?
Correctly processed UHT milk and juice typically last six to twelve months unopened without refrigeration or preservatives. That window lets the Brick Carton Packaging Market serve weak cold chains, though US low-acid products must meet FDA 21 CFR Part 113 controls [22].
Is the Brick Carton Packaging Market well suited to online grocery channels?
Yes. Rectangular bricks stack without void space and resist crushing better than pouches in mixed delivery totes. Brands should still drop-test corners and closures, because impact damage during last-mile handling is the main leak risk [2].
What separates brick cartons from gable-top cartons?
Gable-tops usually carry chilled fresh milk with shelf lives of days to weeks, while bricks are mostly aseptic and ambient-stable. The brick shape also fits more product per pallet, lowering freight cost per litre in the Brick Carton Packaging Market [4].
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















