Automotive Safety System Market (2026 - 2035)

Automotive Safety System Market Research Report By System Type (Active Safety Systems, Passive Safety Systems, In-Cabin Biometric Analytics), By Technology Component (Radar, Camera, LiDAR, Ultrasonic Sensors, ECU and Domain Controllers, Software and Sensor Fusion Stack), By End-User (OEM, Aftermarket), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles), By Propulsion (Internal Combustion Engine, Battery Electric Vehicle, Hybrid and Plug-In Hybrid) - Forecast to 2035
ID: MRFR/AT/4340-HCR
100 Pages
Triveni Bhoyar, Swapnil Palwe
Last Updated: September 04, 2026
Automotive Safety System Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.61%
2025 Market SizeUSD 128.18 Billion
2035 Market SizeUSD 292.78 Billion
Key Players
Robert Bosch GmbH
Continental AG
ZF Friedrichshafen AG
Autoliv Inc.
Denso Corporation
Aptiv PLC
Opportunities
  • Retrofit ADAS for Commercial Fleets
  • In-Cabin Sensing as Regulated Content
  • Safety Data Monetisation and Usage-Based Insurance

Automotive Safety System Market Summary

The Automotive Safety System Market reached USD 128.18 billion in 2025 and opens the forecast window at USD 139.20 billion in 2026, climbing to USD 292.78 billion by 2035 at an 8.61% CAGR. Two catalysts anchor that trajectory. The United States finalised FMVSS No. 127, requiring automatic emergency braking with pedestrian detection on every light vehicle sold from September 2029 [4]. Europe's General Safety Regulation moved intelligent speed assistance, driver drowsiness warning and emergency lane keeping from optional content to type-approval requirements across all new registrations [5].

Hardware-only restraint architecture is giving way to something structurally different. Discrete airbag control units, seat-belt pretensioners and standalone camera modules are being folded into zonal controllers that run perception, planning and restraint logic on shared silicon. Continental's Aumovio spin-off packages cameras, high-performance controllers and cloud analytics as one commercial unit, and Volkswagen's Cariad software arm is co-developing a Level 3 highway pilot with Bosch for series production from 2026 [6][9]. Suppliers now compete on validated software releases rather than component tolerances, and the Automotive Safety System Market rewards that shift with premium content pricing.

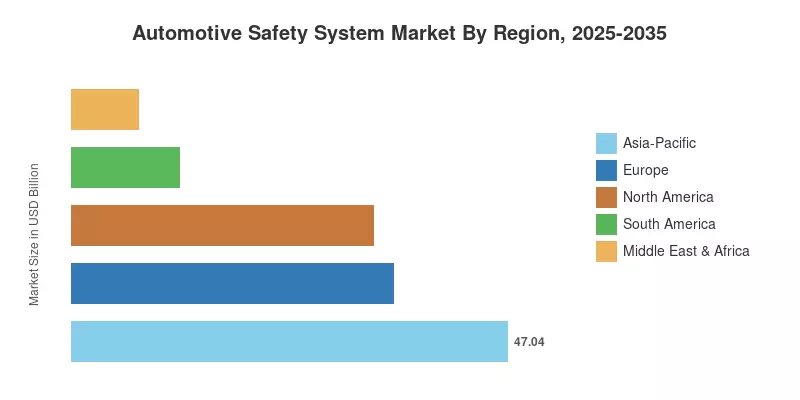
Regionally, Asia-Pacific holds 36.7% of 2025 revenue on the strength of Chinese intelligent-connected-vehicle access rules and India's Bharat NCAP rollout [11][12]. South America expands fastest at a 9.11% CAGR as Latin NCAP tightens protocols and Brazilian assembly lines localise restraint production [21]. Europe follows Asia-Pacific at 27.1% share, sustained by regulation rather than volume growth. Over the next decade, the Automotive Safety System Market will be shaped less by which sensors a vehicle carries and more by how quickly that sensor set can be updated after sale.


Key Report Takeaways

• By System Type

  • Active safety systems commanded 62.0% of Automotive Safety System Market revenue in 2025, reflecting near-universal fitment of camera-plus-radar front-crash prevention on new platforms.

• By Technology Component


  • Radar modules generated 31.7% of component-level revenue in 2025, holding the volume position against camera and ultrasonic alternatives.
  • LiDAR is forecast to expand at a 9.08% CAGR through 2035 as Level 3 highway pilots enter series production.

• By End-User

  • OEM factory-fit installations accounted for 77.2% of 2025 revenue, underscoring how homologation timelines concentrate demand upstream.
  • The aftermarket channel is projected to grow at a 9.15% CAGR, led by retrofit programs in commercial fleets.

• By Propulsion

  • OEM factory-fit installations accounted for 77.2% of 2025 revenue, underscoring how homologation timelines concentrate demand upstream
  • The aftermarket channel is projected to grow at a 9.15% CAGR, led by retrofit programs in commercial fleet
  • Battery-electric platforms register a 9.61% CAGR across the forecast, the fastest of any propulsion class in the Automotive Safety System Market.

• By Region

  • Asia-Pacific held 36.7% revenue share in 2025, anchored by Chinese and Japanese production volume.
  • Europe generated USD 34.74 billion in 2025 on regulation-driven content escalation.
  • South America posts a 9.11% CAGR through 2035, the fastest regional expansion tracked in this study.


Market Size and Forecast (2021–2035)

Figures below combine supplier-reported segment revenues, vehicle production data from national registration authorities, and bottom-up content-per-vehicle modelling calibrated against type-approval filings. Historical values reflect audited supplier disclosures where available; forecast values apply regulation-linked fitment curves to production outlooks. All revenue in the Automotive Safety System Market is measured at supplier sell-in, excluding installation labour and dealer margin.
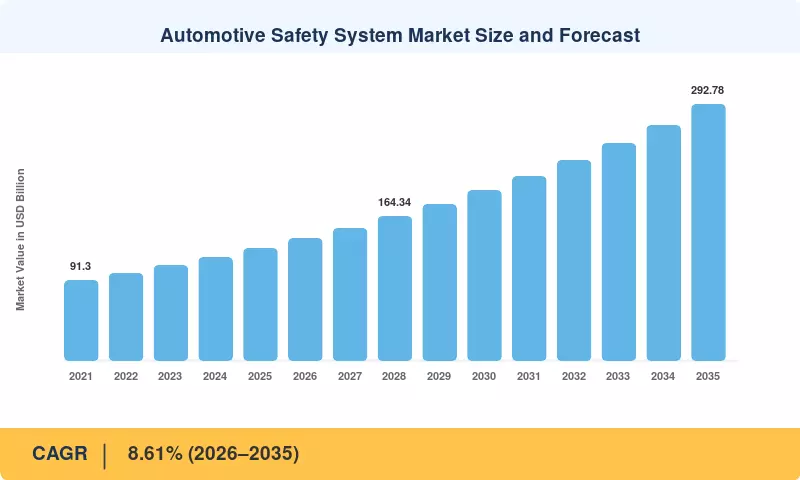
Automotive Safety System Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Mandated AEB and ADAS type-approval rules ~1.9% Global Short-term (≤2 yr)
NCAP star-rating protocol escalation ~1.5% Europe, APAC, LatAm Medium-term (2–4 yr)
Sensor bill-of-material cost erosion ~1.4% Global Medium-term (2–4 yr)
Software-defined vehicle and OTA architectures ~1.3% NA, Europe, China Long-term (≥4 yr)
Electric platform proliferation ~1.1% China, Europe Long-term (≥4 yr)
Commercial fleet mandates and insurance telematics ~0.9% NA, Europe Medium-term (2–4 yr)
Emerging-market road safety programs ~0.8% India, Brazil, MEA Long-term (≥4 yr)


Mandated AEB and ADAS Type-Approval Rules

Regulation establishes the content floor currently. By September 2029, all light vehicles sold in the United States must have automated emergency braking with pedestrian recognition, per NHTSA’s FMVSS No. 127, which applies to approximately 15 million units annually [4]. According to the General Safety Regulation in Europe, emergency lane keeping and sleepiness detection are required for all new registrations [5]. Compliance will convert optional information to standard content, boosting the average safety spend per vehicle by an estimated USD 210 across affected fleets.


NCAP Star-Rating Protocol Escalation

Regulation cannot change the way star ratings influence purchase behavior. Euro NCAP’s 2026 procedure moves the assessment to four pillars and raises the bar for child presence detection and post-crash reaction [1]. That timeframe is consistent with the stated road-map by ANCAP up to 2030 [16]. Manufacturers striving for five stars in the Automotive Safety System Market are specifying sensors beyond the legal minimum, which brings ahead nearly two model years of content adoption compared to a mandate-only baseline.


Sensor Bill-of-Material Cost Erosion

Falling component prices widen the addressable base. Automotive radar module costs have declined at a mid-single-digit annual rate as 77 GHz CMOS designs displaced discrete front-ends, and Qualcomm's Autotalks integration further consolidates the connectivity silicon stack [10]. Cheaper hardware lets B-segment vehicles in India and Brazil carry sensor suites that were C-segment content five years earlier, expanding unit volumes faster than average selling prices compress.

Software-Defined Vehicle and OTA Architectures

Post-sale revenue unlocked with architecture modification. Continental’s Aumovio unit mixes cameras, high-performance controllers, and cloud analytics in one commercial package, and similar zonal systems are moving into production throughout the German and Chinese OEM base [6]. UN R155 requires ongoing surveillance of attack surfaces on the connected car, thereby making an automotive cybersecurity safety system a homologation prerequisite rather than a differentiator [2], adding recurrent software content to every application.


Electric Platform Proliferation

Electrification increases the safety content per unit. In 2024, the IEA estimates more than 17 million electric car sales globally. Battery-electric systems tend to incorporate higher-voltage isolation monitoring, thermal-event detection, and pedestrian acoustic alerting in addition to traditional constraints [19]. Also, skateboard topologies allow more packaging capacity for additional sensor locations. Battery-electric platforms have an 18% higher content-per-vehicle than equivalent internal-combustion vehicles.


Commercial Fleet Mandates and Insurance Telematics

Fleet economics explicitly reward safety hardware. IIHS research has found that front-crash prevention is linked to double-digit decreases in rear-end collision rates, and underwriters are more frequently incorporating that benefit in commercial premiums[14]. For logistics firms with thousands of tractors, blind-spot detection and driver monitoring are loss-cost levers, not compliance spend. The calculation supports a 9.15% aftermarket CAGR until 2035.


Emerging-Market Road Safety Programs

Development finance is reshaping demand in lower-income markets. The World Health Organization attributes roughly 1.19 million annual deaths to road traffic crashes, with the burden concentrated outside high-income countries [13]. World Bank Global Road Safety Facility programs fund vehicle-standard upgrades alongside infrastructure work [20]. India's Bharat NCAP, operational since 2023, has already pushed six-airbag configurations into mass-market nameplates [12].


Restraints Impact Analysis

Restraint impacts below are modelled as drag against an unconstrained growth path and, like the driver estimates, are directional rather than additive. Several restraints interact — validation cost and cybersecurity compliance draw on the same engineering pool — so combining them linearly overstates their joint effect on the Automotive Safety System Market.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Semiconductor and sensor supply volatility ~-0.7% Global Short-term (≤2 yr)
Validation and homologation cost escalation ~-0.6% Europe, NA Medium-term (2–4 yr)
Entry-segment price sensitivity ~-0.5% India, ASEAN, LatAm Long-term (≥4 yr)
Cybersecurity compliance burden ~-0.4% Global Medium-term (2–4 yr)
Consumer distrust and alert fatigue ~-0.3% NA, Europe Medium-term (2–4 yr)


Semiconductor and Sensor Supply Volatility

Allocation risk has not disappeared. Bosch's 2024 reporting flags continued tightness in mature-node analog and power devices, the exact components restraint controllers depend on [9]. Because safety electronics carry ASIL-D qualification, second-sourcing takes 18 to 24 months rather than weeks. A single foundry disruption can strand vehicle production even when every other part is available.

Validation and Homologation Cost Escalation

Proving a perception system is expensive. SAE J3016 Level 2+ and Level 3 functions require statistically defensible evidence across weather, lighting, and edge-case scenarios, pushing validation fleets into the tens of millions of kilometres [22]. Programs routinely allocate 30% to 40% of ADAS engineering budget to verification alone. Smaller suppliers struggle to absorb that fixed cost across limited volume.

Entry-Segment Price Sensitivity

Affordability caps content in high-volume markets. Bharat NCAP submissions concentrate in vehicles priced above the mass-market median, leaving the largest Indian volume bands with minimum-compliance packages [12]. Every USD 100 of added safety content is material where transaction prices sit near USD 9,000. Fitment consequently lags regulation by several model cycles in these segments.

Cybersecurity Compliance Burden

Compliance consumes engineering capacity. UN R155 requires a certified cybersecurity management system covering the full vehicle lifecycle, and R156 adds a software update management system with version traceability [2][3]. Suppliers must staff security operations centres and maintain incident response for a decade or more after the end of production, costs that do not scale down for low-volume programs.

Consumer Distrust and Alert Fatigue

Driver behaviour undermines system value. IIHS field data shows that lane-keeping and forward-collision alerts are switched off at meaningful rates when false positives accumulate [14]. Deactivated systems deliver no crash reduction, which weakens the insurance and regulatory case for further content. Calibration quality, not sensor count, increasingly determines whether installed capability translates into measured outcomes.


Automotive Safety System Market Opportunities

Retrofit ADAS for Commercial Fleets

Depot-installable kits open a channel that OEM cycles cannot reach. Roughly 40% of the North American Class 8 parc predates any collision-mitigation fitment, and modular stacks designed for regional depot installation cut vehicle downtime to a single shift [18]. Aptiv's fleet-oriented ADAS packaging targets exactly this gap. The aftermarket's 9.15% CAGR through 2035 rests largely on this replacement pool.

In-Cabin Sensing as Regulated Content

Euro NCAP's 2026 protocol assigns points for child presence detection and impairment monitoring, converting a discretionary feature into scoring-relevant content [1]. Radar-based and camera-based interior sensing both qualify, and suppliers that certify against multiple protocols capture platform-wide fitment. This positions the occupant sensing safety system as regulated content rather than a premium option, with in-cabin biometric analytics growing at an 8.85% CAGR.

Safety Data Monetisation and Usage-Based Insurance

Event data recorders and ADAS telemetry generate exhaust that underwriters will pay for. Insurers running usage-based programs report loss-ratio improvements sufficient to fund per-vehicle data fees, and OEMs increasingly retain contractual rights to that stream [14][23]. Suppliers who own the perception stack are best placed to package anonymised scenario data for validation licensing — a recurring-revenue layer absent from traditional component economics.

Emerging-Market Protocol Expansion

Latin NCAP's 2024 protocol revision and Bharat NCAP's launch create simultaneous content step-changes in two large production bases [12][21]. Brazilian and Indian assembly plants source restraints locally, so suppliers with domestic manufacturing capture the uplift without tariff exposure. South America's 9.11% CAGR and India's country-level trajectory both derive from this dynamic.

Cyber-Secure Over-the-Air Safety Upgrades

R156-compliant update pipelines let manufacturers ship improved braking calibration or new detection classes to vehicles already in service [3]. That capability turns a one-time hardware sale into a maintained service relationship and shortens the gap between field incident and fleet-wide fix. Suppliers offering certified update infrastructure alongside sensors will defend margin as component pricing compresses.


Automotive Safety System Market Future Outlook

Perception AI and the Shift to Level 3 Volume

Machine-learning perception is displacing rule-based detection across the stack. Bosch's collaboration with Microsoft applies generative AI to automated-driving software development pipelines, compressing scenario-generation cycles that previously consumed months [9]. UN R157 amendments raised approved ALKS operating speeds, making highway pilot economically viable outside flagship models [3]. By 2032, conditional automation should appear on mainstream D-segment platforms in Europe and China, lifting per-vehicle software content substantially above 2025 levels.

Platform Economics and Recurring Revenue

Suppliers are restructuring around software licensing rather than component margin. ZF consolidated its active safety and chassis divisions into a single unit and shipped brake-by-wire on five million vehicles while delivering China's first steer-by-wire system for the Nio ET9 [7]. Integrated actuation plus perception creates a defensible platform position. Feature-on-demand safety upgrades, delivered through certified update pipelines, will contribute a growing share of Automotive Safety System Market revenue by the early 2030s [3].

Electrification and Content Convergence

Electric vehicle penetration reshapes the safety bill of materials. The IEA reported electric car sales exceeding 17 million units in 2024, with China accounting for the majority [19]. Battery platforms require thermal-event detection, high-voltage isolation monitoring and acoustic pedestrian alerting on top of conventional restraints, and their centralised electrical architecture makes zonal safety controllers economically sensible. Battery-electric propulsion carries a 9.61% CAGR, the highest of any propulsion class tracked here.

Cybersecurity, Liability and Sustainability Reporting

Regulatory scope keeps widening beyond crash performance. UN R155 obliges continuous monitoring of attack vectors across the connected vehicle fleet, and suppliers are building secure gateway architecture and security operations capability to satisfy audits [2]. Parallel pressure comes from sustainability disclosure: Valeo and Hyundai Mobis now report component-level carbon intensity alongside financial results, and OEM sourcing scorecards increasingly weight it [23][24]. Safety, security, and environmental compliance are converging into a single supplier qualification gate.


Automotive Safety System Market Segmentation

By System Type

Segment Metric Primary Demand Driver
Active Safety Systems 62.0% share (2025) AEB and lane-keeping type-approval mandates [4][5]
Passive Safety Systems USD 48.71 billion (2025) Airbag count escalation in emerging markets [12]
In-Cabin Biometric Analytics 8.85% CAGR (2026–2035) Euro NCAP child presence and impairment scoring [1]


Active systems dominate the Automotive Safety System Market because regulation now specifies function rather than hardware, and functional requirements point to sensing. Passive restraints remain a large absolute business, sustained less by developed-market growth than by airbag count increases across India, Brazil, and ASEAN. Interior sensing is the fastest-moving sub-segment: protocol scoring converted it from a luxury feature into scoring-relevant content within two assessment cycles.

By Technology Component

Segment Metric Primary Demand Driver
Radar 31.7% share (2025) All-weather front-crash prevention baseline [14]
Camera USD 34.60 billion (2025) Pedestrian classification and lane detection [4]
LiDAR 9.08% CAGR (2026–2035) Level 3 highway pilot programs [3]
Ultrasonic Sensors 11.4% share (2025) Low-speed manoeuvring and parking assistance
ECU and Domain Controllers 8.74% CAGR (2026–2035) Zonal architecture consolidation [6]
Software and Sensor Fusion Stack USD 12.31 billion (2025) Perception licensing and OTA maintenance [18]


Radar holds the volume position in the Automotive Safety System Market on cost and weather robustness, and 77 GHz CMOS integration keeps eroding its price floor without surrendering performance. Cameras follow closely, carrying the classification workload that pedestrian AEB rules require. LiDAR growth is concentrated rather than broad — a small number of Level 3 programs drive most of it. Controller and software revenue expands as functions migrate off discrete modules.

By End-User

Segment Metric Primary Demand Driver
OEM 77.2% share (2025) Type-approval requires factory fitment [5]
Aftermarket 9.15% CAGR (2026–2035) Commercial fleet retrofit economics [14]


Factory-fit installation captures the overwhelming majority of revenue because homologation is a vehicle-level process; a retrofit cannot alter a type-approval certificate. Aftermarket growth nonetheless outpaces OEM, driven by fleets that cannot wait for replacement cycles. Insurance-linked payback, not regulation, underwrites those purchases, and depot-level installation keeps operational disruption to a single shift.

By Vehicle Type

Segment Metric Primary Demand Driver
Passenger Cars 68.9% share (2025) Consumer star-rating sensitivity [1]
Light Commercial Vehicles USD 22.15 billion (2025) Last-mile delivery fleet expansion
Heavy Commercial Vehicles 8.73% CAGR (2026–2035) Blind-spot and driver monitoring mandates [5]


Passenger cars supply the bulk of demand because star ratings influence retail purchase decisions in a way they do not for fleet buyers. Heavy commercial vehicles grow faster from a smaller base: European rules extend direct-vision and blind-spot requirements to trucks, and fleet operators face measurable liability exposure. Light commercial demand tracks e-commerce logistics expansion rather than regulatory timing.

By Propulsion

Segment Metric Primary Demand Driver
Internal Combustion Engine 72.2% share (2025) Installed production base scale
Battery Electric Vehicle 9.61% CAGR (2026–2035) Higher content per vehicle on new platforms [19]
Hybrid and Plug-In Hybrid USD 17.94 billion (2025) Transitional platform volumes


Combustion platforms still carry most units, and therefore most safety revenue in the Automotive Safety System Market, but the growth story sits entirely with battery-electric architecture. New electric platforms are designed around centralised computing, which makes advanced sensing cheaper to integrate than retrofitting it onto legacy wiring. Hybrids occupy an intermediate position, inheriting combustion packaging constraints while adding high-voltage monitoring requirements.


Regional Market Share Analysis

Region Metric (2025 unless noted) Primary Investment Themes
North America 25.4% revenue share FMVSS 127 compliance, fleet retrofit, Level 3 highway pilots
Europe USD 34.74 billion GSR Phase 2, Euro NCAP 2026 protocol, cyber-secure gateways
Asia-Pacific 36.7% revenue share ICV access rules, Bharat NCAP, domestic sensor manufacturing
South America 9.11% CAGR (2026–2035) Latin NCAP protocols, local restraint assembly
Middle East & Africa USD 7.18 billion GCC vehicle standards, fleet safety programs
Total USD 128.18 billion

Regional performance in the Automotive Safety System Market tracks the interaction of production volume and regulatory intensity. Asia-Pacific leads on the first; Europe leads on the second. The table below reports one calibrated metric per region.


North America

Country Metric Key Driver
US 82.4% share of region FMVSS 127 pedestrian AEB deadline [4]
Canada USD 3.94 billion CMVSS harmonisation with US rulemaking
Mexico 9.05% CAGR (2026–2035) Export assembly content alignment


North American demand is front-loaded by a single regulatory deadline. FMVSS No. 127 gives manufacturers until September 2029 to fit pedestrian-capable automatic emergency braking on every light vehicle, and validation lead times mean sourcing decisions were largely locked during 2025 and 2026 [4]. Mexican assembly plants supplying US nameplates inherit that content specification regardless of domestic rules, which explains why Mexico grows faster than the regional average. Fleet retrofit adds a parallel demand stream, with insurers underwriting collision-mitigation installations on tractor units [14].

Europe

Country Metric Key Driver
Germany 26.8% share of region Premium OEM Level 3 programs [3]
UK USD 5.71 billion Automated Vehicles Act implementation
France 14.2% share of region Domestic Tier-1 sensor manufacturing [23]
Italy 8.65% CAGR (2026–2035) Light commercial vehicle fitment
Spain USD 2.43 billion Export-oriented B-segment assembly
Nordic Countries 5.9% share of region Winter-condition validation demand
Russia 7.42% CAGR (2026–2035) Constrained supplier access
Rest of Europe USD 3.16 billion Central European component clusters


Europe converts regulation into content faster than any other region. The General Safety Regulation made intelligent speed assistance, emergency lane keeping, and drowsiness detection mandatory for all new registrations, and Euro NCAP's 2026 protocol layers additional scoring pressure on top [1][5]. German premium manufacturers carry the Level 3 burden, with UN R157 amendments raising approved operating speeds and widening the addressable use case [3]. French and Spanish plants supply the volume segments, where sensor cost trajectories determine how quickly optional content becomes standard.

Asia-Pacific

Country Metric Key Driver
China 41.6% share of region MIIT intelligent connected vehicle access pilot [11]
India 10.24% CAGR (2026–2035) Bharat NCAP submissions accelerate [12]
Japan USD 8.92 billion MLIT automated driving guidelines [15]
South Korea 10.1% share of region Domestic OEM sensor vertical integration
ASEAN 9.46% CAGR (2026–2035) ASEAN NCAP protocol tightening
Rest of Asia-Pacific USD 3.11 billion Australian ANCAP alignment [16]


Asia-Pacific dominance in the Automotive Safety System Market rests on production scale plus fast-moving domestic regulation. China's MIIT access pilot for intelligent connected vehicles established conditional approval pathways for higher-automation systems and pushed domestic suppliers into steer-by-wire and brake-by-wire programs ahead of Western peers [11]. India's trajectory is steeper from a smaller base: Bharat NCAP submissions have made six-airbag configurations a marketing standard in segments that carried two airbags three years earlier [12]. Japanese demand is stable rather than expansive, anchored by MLIT's automated driving safety guidelines [15].

South America

Country Metric Key Driver
Brazil 54.3% share of region Latin NCAP 2024 protocol revision [21]
Argentina USD 1.19 billion Regional assembly integration
Rest of South America 8.62% CAGR (2026–2035) Import specification harmonisation


South America posts the fastest regional expansion from the smallest base. Latin NCAP's revised assessment protocol raised the threshold for adult and child occupant protection, and manufacturers selling into Brazil now specify electronic stability control and multi-airbag configurations that were previously export-only content [21]. Brazilian restraint assembly is largely localised, so content uplift translates directly into domestic supplier revenue. World Bank road safety financing supports parallel enforcement and infrastructure work, reinforcing the vehicle-standard trajectory [20].

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 24.6% share of region GCC standardisation and fleet renewal
UAE USD 1.44 billion Premium import mix and AV pilot corridors
South Africa 9.28% CAGR (2026–2035) Local assembly export compliance
Egypt USD 0.71 billion Domestic assembly localisation policy
Rest of MEA 21.4% share of region Used-vehicle import standards


Demand across the Middle East and Africa splits sharply between Gulf markets and the rest of the continent. GCC states import a premium-weighted mix that arrives with European or Japanese specification content already fitted, so safety spend tracks vehicle value rather than local mandates. South African assembly plants building for European export must meet GSR requirements regardless of domestic rules, producing the region's fastest country-level growth [5]. Used-vehicle import standards remain the binding constraint elsewhere, with WHO analysis linking imported older fleets to elevated fatality rates [13].


Automotive Safety System Market By Region, 2025-2035

Competitive Benchmarking

Concentration sits in the moderate range, with an estimated HHI between 950 and 1,150 and a top-five combined share of roughly 45% to 52%. That structure reflects genuine scale advantages in validation and manufacturing without the single-supplier dominance seen in some component categories. Semiconductor firms are entering from adjacent positions, and interior-sensing start-ups are winning OEM pilots, so fragmentation at the technology layer coexists with consolidation at the systems-integration layer of the Automotive Safety System Market.

Company Est. Revenue Share Range Key Offerings for Automotive Safety System Market Strategic Positioning
Robert Bosch GmbH ~13–16% Radar, camera, ESP, restraint control, AD software Broadest portfolio; AI development pipeline with Microsoft [9]
Continental AG (Aumovio) ~9–12% Cameras, high-performance controllers, cloud analytics Software-centric pivot via dedicated brand [6]
ZF Friedrichshafen AG ~8–11% Brake-by-wire, steer-by-wire, airbags, ADAS ECUs Merged chassis and active safety divisions [7]
Autoliv Inc. ~7–10% Airbags, seatbelts, steering wheels, pedestrian protection Restraint leader; e-VTOL collaboration with XPENG AEROHT [8]
Denso Corporation ~6–9% Radar, camera, ECUs, occupant sensing Japanese OEM anchor; vertically integrated silicon [17]
Aptiv PLC ~5–7% Modular ADAS stack, connectors, zonal architecture Fleet-retrofit packaging and depot serviceability [18]
Valeo SA ~4–6% LiDAR, ultrasonic sensors, interior monitoring Third-generation LiDAR volume programs [23]
Hyundai Mobis ~3–5% Integrated ADAS modules, airbags, braking Captive Korean OEM base with export expansion [24]
Magna International ~3–5% Cameras, driver monitoring, ADAS domain controllers Complete-vehicle assembly plus systems supply
Joyson Safety Systems ~2–4% Airbags, steering wheels, occupant classification China-anchored cost position with global footprint
Qualcomm Technologies ~1–3% Snapdragon Ride, V2X via Autotalks Semiconductor entry into safety-critical compute [10]
Nvidia Corporation ~1–3% DRIVE compute platforms, perception toolchains Compute supplier to Level 3 programs [22]


Recent News & Developments

  • NHTSA (April 2024): Finalised FMVSS No. 127 mandating automatic emergency braking with pedestrian detection on all light vehicles by September 2029, establishing the largest single content mandate in the market's history [4]
  • Bharat NCAP (October 2023): India launched its domestic crash-assessment program, triggering rapid six-airbag standardisation across mass-market nameplates and lifting restraint content per vehicle. [12]
  • UNECE (June 2023): Adopted amendments to UN R157 raising approved ALKS operating speeds, widening the commercial case for Level 3 highway pilot systems in Europe and Japan. [3]
  • ZF Friedrichshafen (September 2024): Merged its Active Safety and Chassis Solutions divisions into a single organisation, and delivered China's first production steer-by-wire system for the Nio ET9. [7]


  • Continental AG (2025): Launched the Aumovio brand to consolidate cameras, high-performance controllers and cloud analytics under a software-oriented commercial structure. [6]
  • Autoliv (2025): Announced a collaboration with XPENG AEROHT to develop dual-use restraint systems spanning road vehicles and low-altitude electric aircraft. [8]
  • China MIIT (November 2023): Issued the intelligent connected vehicle access and on-road pilot notice, creating conditional approval pathways for higher-automation systems in the world's largest vehicle market. [11]


Automotive Safety System Market Report Scope

Parameter Detail
Market Scope Global active and passive automotive safety systems, including sensing hardware, restraint devices, controllers, and associated software, measured at supplier sell-in
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 8.61% (2026–2035)
Market Size Checkpoints USD 128.18 billion (2025); USD 139.20 billion (2026); USD 210.40 billion (2031); USD 292.78 billion (2035)
Fastest Growing Segments Battery-electric propulsion (9.61% CAGR); aftermarket channel (9.15% CAGR); LiDAR components (9.08% CAGR); South America (9.11% CAGR)
Companies Profiled Bosch, Continental (Aumovio), ZF Friedrichshafen, Autoliv, Denso, Aptiv, Valeo, Hyundai Mobis, Magna International, Joyson Safety Systems, Qualcomm, Nvidia
Valuation Currency USD Billion, constant 2025 dollars, supplier sell-in basis

FAQs

How should procurement teams screen Tier-1 suppliers in the Automotive Safety System Market?
Weight ISO 26262 ASIL-D certification, documented cybersecurity management system audit trails, and multi-region validation capacity above unit price. A supplier lacking R155 evidence creates homologation risk that no bill-of-materials saving offsets. [2]
Which integration challenges most often delay ADAS program launches?
Sensor calibration drift and perception-stack validation consume more schedule than hardware sourcing does. Teams routinely underestimate the volume of real-world edge-case mileage regulators expect before accepting performance claims. [22]
Should buyers in the Automotive Safety System Market standardise on radar or LiDAR?
Radar remains the volume workhorse for cost-constrained platforms; LiDAR earns its cost only on Level 3 highway-pilot programs. Most manufacturers dual-source rather than committing to one sensing modality. [18]
What does UN R156 change about software update planning?
R156 requires a certified software update management system before any over-the-air safety change ships. Version traceability must be maintained for the vehicle's full service life, which lengthens supplier support obligations well past end of production. [3]
Where does the aftermarket offer the strongest returns in the Automotive Safety System Market?
Retrofit blind-spot detection and driver-monitoring kits for logistics fleets deliver the fastest payback, funded largely by insurance premium reductions. Depot installation keeps vehicle downtime inside a single shift. [14]
What warranty exposure do interior sensing deployments create?
False-suppression events in airbag deployment logic carry the highest claim severity of any interior-sensing failure mode. Suppliers increasingly ring-fence that exposure through shared-liability clauses tied to validated occupant-classification datasets. [8]
How should investors interpret supplier divisional consolidation?
Mergers of chassis and active-safety units typically signal margin recovery efforts rather than revenue expansion. Track engineering headcount redeployment and platform win rates instead of announced order intake. [7]      
Author
Author
Author Profile
Triveni Bhoyar LinkedIn Senior Research Analyst
Triveni Bhoyar has over 5 years of experience in the market research industry, specializing in the Automotive and Aerospace & Defense sectors. She has contributed to 200+ reports, including numerous custom projects for leading global companies, delivering solutions to complex business challenges. Renowned for her ability to generate valuable insights, Triveni excels in addressing unique market dynamics with precision and depth. Her expertise spans market sizing, competitive intelligence, and trend analysis, enabling clients to craft data-driven growth strategies. With strong analytical rigor and a client-centric approach, she plays a pivotal role in driving impactful, strategic decision-making.
Co-Author
Co-Author Profile
Swapnil Palwe LinkedIn Team Lead - Research
With a technical background as Bachelor's in Mechanical Engineering, with MBA in Operations Management , Swapnil has 6+ years of experience in market research, consulting and analytics with the tasks of data mining, analysis, and project execution. He is the POC for our clients, for their consulting projects running under the Automotive/A&D domain. Swapnil has worked on major projects in verticals such as Aerospace & Defense, Automotive and many other domain projects. He has worked on projects for fortune 500 companies' syndicate and consulting projects along with several government projects.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, technical standards publications, peer-reviewed engineering journals, and authoritative automotive safety organizations. Key sources included the US National Highway Traffic Safety Administration (NHTSA), European New Car Assessment Programme (Euro NCAP), Insurance Institute for Highway Safety (IIHS), US Department of Transportation (DOT), European Union Agency for Railways (ERA) and automotive safety directives, International Organization for Standardization (ISO 26262 - Functional Safety), SAE International (Society of Automotive Engineers), Japan Automobile Manufacturers Association (JAMA), China Association of Automobile Manufacturers (CAAM), International Transport Forum (ITF), US Bureau of Transportation Statistics, EU European Commission Mobility and Transport, National Transportation Safety Board (NTSB) accident databases, Global NCAP, International Energy Agency (IEA) Global EV Outlook, and national motor vehicle safety standards from key markets. These sources were used to collect vehicle safety regulation data, crash test ratings, technology adoption statistics, regulatory mandate timelines, and market landscape analysis for electronic stability control (ESC), anti-lock braking systems (ABS), lane departure warning (LDW), blind spot detection (BSD), tire pressure monitoring systems (TPMS), electronic brake-force distribution (EBD), and passive safety technologies.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. From Tier 1 automotive safety system manufacturers and OEMs, supply-side sources comprised CEOs, VPs of Engineering, leaders of Active Safety Systems, directors of passive safety divisions, and regulatory compliance officers. Vehicle safety engineers, procurement directors from automotive OEMs, fleet management safety officers, and regulatory affairs managers from passenger vehicle, light commercial vehicle (LCV), and heavy commercial vehicle (HCV) manufacturers were among the demand-side sources. The timelines for technology adoption were validated, product development pipelines were confirmed, and insights were obtained regarding integration challenges, pricing dynamics, and regulatory compliance strategies through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Region: North America (32%), Europe (30%), Asia-Pacific (33%), Rest of World (5%)


Market Size Estimation

Global market valuation was derived through revenue mapping and technology deployment analysis. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across active safety systems (ESC, ABS, LDW, BSD, TPMS, EBD), passive safety technologies (single stage and progressive stage operations), and manufacturing processes (hot stamping, cold stamping)

Analysis of reported and modeled annual revenues specific to automotive safety system portfolios

Coverage of manufacturers representing 72-78% of global market share in 2024

Extrapolation using bottom-up (vehicle production volume × safety system penetration × ASP by region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for passenger vehicles, light commercial vehicles (LCV), and heavy commercial vehicles (HCV)

Key Changes Made:

Company Tier: Shifted from 42/33/25 to 38/40/22 (emphasizing Tier 2 mid-market players)

Designation: Changed from 35/28/37 to 28/35/37 (elevating Director-level technical input)

Region: Modified from 35/27/30/8 to 32/30/33/5 (increasing Asia-Pacific emphasis, reducing RoW)

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















