Automotive Passive Electronic Component Market (2026 - 2035)

Automotive Passive Electronic Component Market Research Report By Type (Capacitors (Ceramic Capacitors, Tantalum Capacitors, Aluminum Electrolytic Capacitors, Paper and Plastic Film Capacitors, Supercapacitors), Inductors, Resistors (Surface-mounted Chips, Network and Array, Other Specialty), EMC Filters) - Forecast to 2035
ID: MRFR/AT/26064-HCR 128 Pages Shubham Munde, Sejal Akre Last Updated: October 23, 2026
Automotive Passive Electronic Component Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.0%
2025 Market SizeUSD 6.52 Billion
2035 Market SizeUSD 12.83 Billion
Key Players
Murata Manufacturing
TDK Corporation
Samsung Electro-Mechanics
Yageo Corporation
Panasonic Industry
Vishay Intertechnology
Opportunities
  • 800V Platforms and Silicon Carbide Inverters
  • Localized Supply in Emerging Markets
  • Redundant Power for By-Wire Systems

Automotive Passive Electronic Component Market Summary

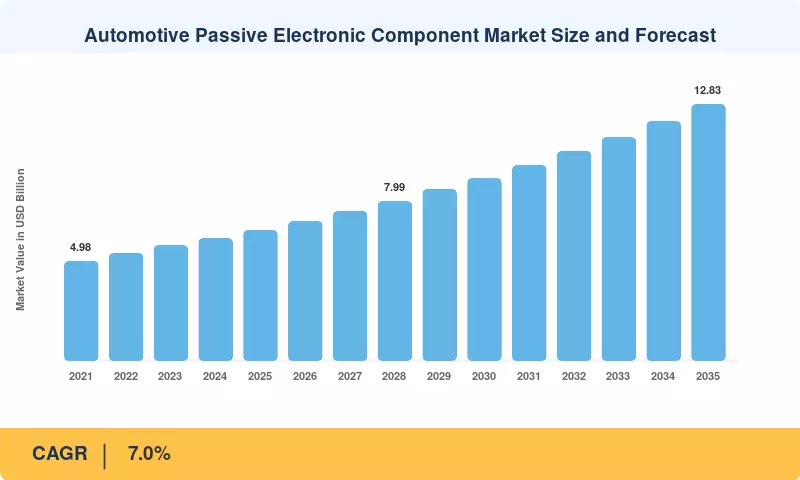
The Automotive Passive Electronic Component Market was valued at USD 6.52 billion in 2025 and is projected to reach USD 6.98 billion in 2026, climbing to USD 12.83 billion by 2035 at a CAGR of 7.0% over 2026–2035. Two catalysts anchor this trajectory. Global electric car sales passed 17 million units in 2024 [2], and mandatory driver-assistance rules in the European Union and the United States are pushing radar, camera and braking electronics into every new vehicle class [3][4]. Each of these systems depends on capacitors, inductors, resistors and filters to condition power and protect signals.

Underneath the headline numbers, the vehicle's electrical architecture is being rebuilt. Distributed, function-specific control boxes are giving way to zonal controllers and centralized compute, while 400V and 800V traction systems replace low-voltage drivetrains. That shift raises demand for high-capacitance ceramic parts, film capacitors rated for silicon carbide inverters, and power inductors that tolerate higher switching frequencies. Public money is reinforcing it: the US CHIPS and Science Act committed USD 52.7 billion to domestic semiconductor capacity and its surrounding ecosystem [6].

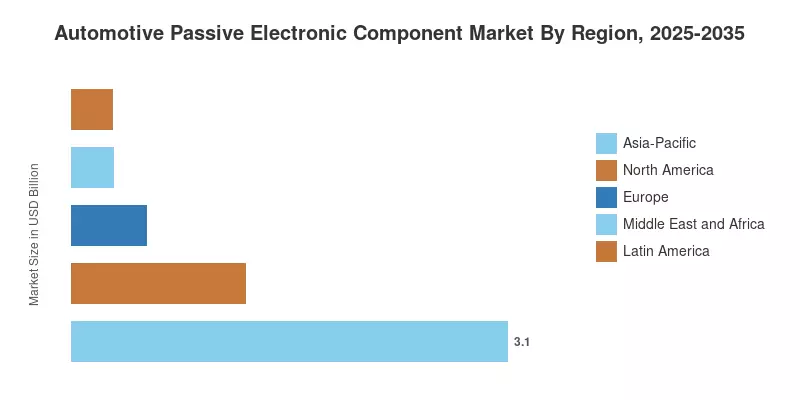
Asia-Pacific dominates with a 47.5% share, built on dense supply bases in China, Japan and South Korea. Europe, the second-largest regional base, is also the fastest growing at 8.1% CAGR, propelled by Euro 7 and ADAS mandates. North America holds a 19.0% share and benefits from reshoring incentives. Over the next decade, the Automotive Passive Electronic Component Market will increasingly reward suppliers that pair automotive-grade reliability with high-voltage capability.

Key Report Takeaways

• By Type

  • Capacitors lead the Automotive Passive Electronic Component Market with a 44.0% share in 2025, reflecting their role in power filtering and energy buffering across every ECU
  • EMC Filters represent the fastest-growing type at 8.6% CAGR, as higher switching speeds in traction inverters intensify electromagnetic interference challenges
  • Resistors generated USD 1.37 billion in 2025, with surface-mounted chips forming the bulk of shipments

• By Region

  • Asia-Pacific anchors the Automotive Passive Electronic Component Market with a 47.5% share, led by China's new energy vehicle output
  • Europe posts the fastest regional expansion at 8.1% CAGR, supported by regulatory safety and emissions mandates
  • North America accounts for a 19.0% share, with semiconductor reshoring and EV assembly investment lifting regional demand

Market Size and Forecast (2021–2035)

Estimates for the Automotive Passive Electronic Component Market combine supplier revenue disclosures, vehicle production statistics, and per-vehicle component content models validated through primary interviews with component makers, Tier-1 suppliers and automaker procurement teams. Historical values were reconciled against global production data [9] and annual reports of leading suppliers [12][13][14]. Forecast values assume steady electrification and ADAS penetration with no major supply shock.
Automotive Passive Electronic Component Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

The impact percentages below are directional estimates of each driver's contribution to growth in the Automotive Passive Electronic Component Market. They overlap and interact, so they should not be added together to reconstruct the headline CAGR.

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Vehicle electrification and high-voltage power electronics +1.8% Global, led by China and Europe Long-term (≥4 yr)
ADAS regulatory mandates +1.4% Europe, North America Medium-term (2–4 yr)
ECU proliferation and zonal architecture +1.0% Global Long-term (≥4 yr)
Connectivity, infotainment and RF content +0.7% Global Medium-term (2–4 yr)
Emissions rules driving ICE electronics +0.6% Europe, India Short-term (≤2 yr)
Production localization incentives +0.5% North America, India Medium-term (2–4 yr)

Vehicle Electrification and High-Voltage Power Electronics

Sales of electric vehicles exceeded 17 million in 2024 after reaching over 14 million in 2023 [1][2]. Leading providers estimate that the MLCC counts per battery-electric vehicle (EV) are approximately three times higher than those of an internal combustion engine (ICE) vehicle [12]. Battery EVs have a significantly higher passive content than combustion versions. Electrification is the single biggest growth lever for the automotive passive electronic component market since onboard chargers, DC-DC converters, and traction inverters all require DC-link capacitors, power inductors, and current-sense resistors.

ADAS Regulatory Mandates

Beginning in July 2024, all new cars must have driver drowsiness warning, emergency lane maintaining, and intelligent speed assistance, according to another safety regulation [3]. NHTSA's FMVSS No. 127, which mandates automated emergency braking on light vehicles in the US by September 2029, is anticipated to save at least 360 lives a year [4]. Low-noise capacitors and EMC filtering are used by radar modules, camera ECUs, and sensor fusion units to convert each mandate into a recurrent passive demand.

ECU Proliferation and Zonal Architecture

Premium vehicles already carry more than 100 electronic control units, and even entry-level models now integrate dozens [12]. Automakers are consolidating these into zonal controllers and central compute, but consolidation raises power density per board rather than lowering passive counts. High-performance processors need extensive decoupling networks, often hundreds of capacitors around a single system-on-chip, keeping per-vehicle passive value on an upward track.

Connectivity, Infotainment and RF Content

Telematics units, 5G modems, Wi-Fi and Bluetooth modules, and large infotainment displays each add RF inductors, filters and timing components. Suppliers report that automotive now ranks among their fastest-growing end markets for RF passives and noise suppression parts [13]. Vehicle-to-everything pilots in China, Europe and the US add further antenna and filtering content, particularly in higher trims where connected services carry subscription revenue.

Emissions Rules Driving ICE Electronics

Combustion vehicles are not standing still. Regulation (EU) 2024/1257, known as Euro 7, applies to new car types from November 2026 and extends limits to brake and tyre particles [5]. Meeting these rules requires more precise engine management, exhaust aftertreatment control and 48V mild-hybrid systems. India sold more than 3.89 million passenger vehicles in fiscal 2023 [7], and tightening norms there are expanding electronic content in mass-market ICE models.

Production Localization Incentives

Governments are funding regional electronics supply chains to reduce dependence on a handful of Asian hubs. The US CHIPS and Science Act allocated USD 52.7 billion to semiconductor manufacturing and research [6]. India's Production Linked Incentive scheme for automobiles and auto components carries an outlay of INR 25,938 crore [18]. Both programs encourage component makers to add local capacity close to vehicle assembly plants.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Miniaturization and reliability trade-offs −0.6% Global Long-term (≥4 yr)
High development and qualification costs −0.5% Global Medium-term (2–4 yr)
Raw material price and sourcing volatility −0.4% Global Short-term (≤2 yr)
Trade barriers and supply concentration −0.4% North America, China Medium-term (2–4 yr)
Automotive demand cycles and inventory corrections −0.3% Global Short-term (≤2 yr)

Miniaturization and Reliability Trade-offs

Although smaller components are more susceptible to board flex cracking, thermal cycle fatigue, and voltage derating, compact ECUs force designers to use 0402 and 0201 case sizes. Temperatures above 150°C under the hood exacerbate these dangers. Advanced dielectric materials and thinner layers are required to provide high capacitance in small packages without compromising durability, which slows product cycles and limits the supplier pool [11].

High Development and Qualification Costs

AEC-Q200 stress qualification, which includes temperature cycling, humidity bias, and 1,000-hour life testing, is a requirement for all automotive passives [11]. Programs for zero-defect quality and production part approval increase expenses and delays. Automotive-grade lines have a significantly greater capital intensity than consumer lines, according to suppliers [15], which discourages smaller manufacturers and increases hurdles to entry.

Raw Material Price and Sourcing Volatility

Tantalum capacitors depend on a mineral concentrated in a few countries, with the Democratic Republic of the Congo and Rwanda supplying more than half of mined output [10]. Conflict-mineral disclosure rules add audit costs [22]. Palladium, silver and nickel used in electrodes also swing sharply in price, compressing margins on long-term automotive contracts with fixed pricing.

Trade Barriers and Supply Concentration

The USTR's 2024 review raised Section 301 tariffs on Chinese semiconductors to 50% by 2025 and on Chinese electric vehicles to 100% [17]. Passive component manufacturing remains heavily concentrated in Japan, China, South Korea and Taiwan. Tariffs and export controls complicate sourcing, forcing automakers to qualify second sources and absorb higher landed costs.

Automotive Demand Cycles and Inventory Corrections

After stockpiling during the 2021–2022 shortage, distributors and Tier-1s worked down excess MLCC inventory through 2023 and 2024 [12]. Global vehicle production of roughly 92 million units in 2024 showed little growth [9]. Such corrections can depress orders for several quarters even while per-vehicle content keeps rising.

Automotive Passive Electronic Component Market Opportunities

800V Platforms and Silicon Carbide Inverters

The move to 800V architectures and silicon carbide switching creates demand for film capacitors with high ripple-current ratings, high-voltage resistors and low-loss inductors [2]. Suppliers that qualify products for 1,200V operation and elevated temperatures can capture premium pricing. Film and supercapacitor sub-segments stand to gain the most.

Localized Supply in Emerging Markets

India and ASEAN are building vehicle and electronics assembly capacity, but local automotive-grade passive production remains thin. India's PLI incentives [18] and domestic vehicle sales above 3.89 million units [7] create room for regional plants and joint ventures. India's 9.4% CAGR makes it the most attractive greenfield target in Asia.

Redundant Power for By-Wire Systems

Steer-by-wire, brake-by-wire and electronic door latches require backup energy if the main supply fails. Supercapacitors offer fast discharge and long cycle life suited to this role [13]. As higher autonomy levels demand fail-operational architectures, redundant power modules could become a standard fitment.

Traceability Data and Supply-Assurance Services

Automakers burned by the 2021–2022 shortage now pay for visibility. Suppliers can monetize lot-level traceability data, reliability analytics and vendor-managed inventory programs as subscription services. Digital product passport requirements under the EU Battery Regulation, applying from February 2027 [19], set a precedent that may extend component-level data obligations to electronics.

Circular Materials and Recycled Content

The European Commission's proposed End-of-Life Vehicles regulation would require recycled content targets and design-for-dismantling rules [20]. Suppliers developing recovered tantalum, palladium and silver streams can secure supply while meeting automaker sustainability scorecards.

Automotive Passive Electronic Component Market Future Outlook

Four themes will shape the Automotive Passive Electronic Component Market through 2035, each raising per-vehicle content and qualification standards.

High-Voltage Electrification Supercycle

Electric cars are expected to exceed 40% of global car sales by 2030 under stated policies [2]. That transition moves the center of gravity toward high-voltage film capacitors, power inductors and precision shunt resistors. Suppliers able to deliver parts rated for 800V operation and silicon carbide switching speeds will hold structural pricing advantages through the decade.

Zonal Architecture and Software-Defined Vehicles

Automakers are consolidating ECUs into zonal gateways and central compute platforms. These boards concentrate high-current power delivery and high-speed data lines, demanding dense decoupling arrays and common-mode filtering. Over-the-air updates also extend vehicle service life, raising lifetime reliability requirements for every board-level part.

Sensor Fusion and Higher Autonomy

Level 2+ and Level 3 systems combine radar, lidar and camera inputs with redundant power and compute. Each sensor channel needs clean power and EMI suppression, and fail-operational designs duplicate entire power paths. Advances in in-vehicle circuit technology, including chiplet-based processors, will push capacitor and inductor counts higher per autonomous-capable vehicle [4].

Sustainability and Materials Stewardship

The EU Battery Regulation [19] and the proposed End-of-Life Vehicles regulation [20] signal a future in which automakers must document material provenance and recycled content. Passive component makers will face growing scrutiny over tantalum sourcing [10], energy use in sintering, and recoverability. Early movers on low-carbon production will gain preferred-supplier status.

Regional Market Share Analysis

Region Key Metric (2025) Primary Investment Themes
North America 19.0% share EV assembly, CHIPS Act reshoring, AEB compliance
Europe 8.1% CAGR ADAS mandates, Euro 7, 800V premium platforms
Asia-Pacific 47.5% share NEV volume, MLCC capacity, export hubs
Latin America USD 0.29 Billion Brazil flex-fuel hybrids, nearshoring
Middle East and Africa 4.6% share Vehicle assembly programs, South African exports
Total USD 6.52 Billion —

Regional demand in the Automotive Passive Electronic Component Market tracks vehicle production, EV adoption and regulatory pressure. Asia-Pacific leads by volume, while Europe grows fastest on mandates.

North America

Country Key Metric (2025) Key Driver
US 76% of region EV and battery investment, AEB rule
Canada 6.1% CAGR EV supply chain incentives in Ontario
Mexico USD 0.17 Billion Tier-1 electronics assembly for export

The US dominates regional demand, supported by FMVSS No. 127 [4] and CHIPS Act funding that is pulling component makers toward domestic production [6]. Tariffs on Chinese electronics [17] are accelerating supplier qualification in Mexico, where electronics assembly for US-bound vehicles keeps expanding. Canada's growth is tied to battery and EV assembly announcements around Ontario.

Europe

Country Key Metric (2025) Key Driver
Germany 31% of region Premium EV and ADAS engineering
UK 7.6% CAGR ZEV mandate and EV production
France USD 0.19 Billion EV platform launches
Italy 9% of region Commercial vehicle electronics
Spain 8.4% CAGR Growing EV assembly base
Nordic Countries USD 0.08 Billion Battery manufacturing, premium EVs
Russia 3% of region Localized assembly under constraints
Rest of Europe USD 0.32 Billion Central European Tier-1 clusters

Germany anchors European demand through premium automakers deploying 800V platforms and sophisticated ADAS. The General Safety Regulation [3] and Euro 7 [5] push electronic content into every new model. Spain and Central Europe are attracting EV assembly and Tier-1 investment, while Russia's market remains constrained by sanctions and supply restrictions.

Asia-Pacific

Country Key Metric (2025) Key Driver
China 54% of region NEV volume leadership
Japan USD 0.56 Billion Component technology leadership, hybrids
South Korea 9% of region EV and battery exports
India 9.4% CAGR PLI incentives, rising vehicle sales
ASEAN USD 0.16 Billion Thai and Indonesian EV hubs
Australia and New Zealand 5.8% CAGR Aftermarket and imported EV fleet
Rest of Asia-Pacific 3% of region Taiwan component production

China sold close to 13 million new energy vehicles in 2024 [8], making it the largest demand center by a wide margin. Japan and South Korea host the leading MLCC and inductor producers, and their domestic vehicle electronics manufacturing ecosystems set global benchmarks for automotive-grade quality. India is the fastest-growing country, with PLI incentives [18] and Euro-equivalent norms raising electronic content across mass-market models.

Latin America

Country Key Metric (2025) Key Driver
Brazil 63% of region Flex-fuel hybrid programs
Argentina 6.6% CAGR Pickup and commercial vehicle output
Rest of Latin America USD 0.06 Billion Imported vehicle electronics

Brazil leads regional demand as automakers introduce flex-fuel hybrids that combine ethanol engines with electrified drivetrains. Argentina's output centers on pickups and light commercial vehicles with rising electronic content. Most passive components in the region are imported, leaving room for local distribution and value-added assembly.

Middle East and Africa

Country Key Metric (2025) Key Driver
Saudi Arabia 8.9% CAGR Domestic EV manufacturing ambitions
UAE 18% of region Premium imports, smart mobility pilots
South Africa USD 0.08 Billion Export-oriented vehicle plants
Egypt 7.4% CAGR Assembly localization programs
Rest of Middle East and Africa 30% of region Aftermarket replacement demand

South Africa remains the region's established production base, exporting vehicles to Europe under trade agreements. Saudi Arabia is building domestic EV capacity as part of economic diversification plans, which drives the fastest country growth. Egypt and other markets rely on assembly localization, while aftermarket replacement sustains demand in the rest of the region.

Automotive Passive Electronic Component Market By Region, 2025-2035

Automotive Passive Electronic Component Market Segmentation

The Automotive Passive Electronic Component Market is segmented by type into Capacitors, Inductors, Resistors and EMC Filters, with capacitors and resistors further divided into sub-segments.

By Type

Segment Key Metric (2025) Primary Demand Driver
Capacitors 44.0% share Power filtering and energy buffering
Inductors 7.9% CAGR DC-DC conversion in EVs
Resistors USD 1.37 Billion Current sensing and circuit protection
EMC Filters 8.6% CAGR Inverter EMI suppression

Within the Automotive Passive Electronic Component Market, capacitors hold the largest position because nearly every circuit needs decoupling and bulk energy storage. EMC Filters grow fastest as silicon carbide inverters switch at higher frequencies, generating interference that must be contained to meet vehicle EMC standards. Inductors follow closely, driven by onboard chargers and DC-DC converters. Resistors remain a steady, high-volume category tied to current sensing and battery management.

Capacitors

Segment Key Metric (2025) Primary Demand Driver
Ceramic Capacitors 52% of capacitors ECU decoupling, ADAS modules
Tantalum Capacitors 6.2% CAGR Stable capacitance in compact designs
Aluminum Electrolytic Capacitors USD 0.60 Billion Bulk storage in power supplies
Paper and Plastic Film Capacitors 12% of capacitors DC-link in traction inverters
Supercapacitors 11.2% CAGR Backup power for by-wire systems

Ceramic Capacitors dominate the capacitor segment of the Automotive Passive Electronic Component Market, with MLCCs used by the thousands in each EV [12]. Supercapacitors grow fastest from a small base as redundant power becomes mandatory for steer-by-wire and brake-by-wire. Paper and Plastic Film Capacitors gain share in 800V inverters, while Aluminum Electrolytic Capacitors remain essential for bulk storage in power supplies.

Inductors

Inductors serve power conversion, noise suppression and RF tuning across the vehicle. EV onboard chargers, DC-DC converters and LED lighting drivers depend on molded power inductors that tolerate high current and temperature. Their 7.9% CAGR reflects rising converter counts per vehicle and the move to higher switching frequencies, which favors compact metal-composite designs [13].

Resistors

Segment Key Metric (2025) Primary Demand Driver
Surface-mounted Chips 68% of resistors High-volume board assembly
Network and Array 6.9% CAGR Board space savings in ECUs
Other Specialty USD 0.19 Billion Shunt and high-voltage sensing

Surface-mounted Chips form the core of resistor demand because automated board assembly favors standardized chip formats. Network and Array resistors grow as designers consolidate parts to save space in crowded ECUs. Other Specialty resistors, including low-ohm shunts for battery current sensing and high-voltage dividers, carry the highest unit value [15].

EMC Filters

EMC Filters protect sensitive electronics from conducted and radiated interference generated by inverters, motors and high-speed data lines. Their 8.6% CAGR makes them the fastest-growing type, as wide-bandgap semiconductors raise switching edge rates sharply. Zonal architectures with high-speed Ethernet backbones also need common-mode chokes and filter arrays at every gateway.

Competitive Benchmarking

The Automotive Passive Electronic Component Market shows low-to-moderate concentration, with an estimated HHI of 750–900. The top five suppliers together hold an estimated 45–55% of revenue, led by Japanese and Korean MLCC specialists. A long tail of regional and niche producers competes in resistors, film capacitors and specialty filters, keeping the market fragmented outside high-end ceramics.

Company Est. Revenue Share Range Key Offerings for Automotive Passive Electronic Component Market Strategic Positioning
Murata Manufacturing ~14–17% Automotive MLCCs, inductors, EMI filters Global leader in high-capacitance ceramics
TDK Corporation ~10–13% MLCCs, film capacitors, power inductors Broad power electronics portfolio for EVs
Samsung Electro-Mechanics ~7–10% High-reliability automotive MLCCs Rapid capacity expansion in automotive grade
Yageo Corporation (incl. KEMET) ~7–9% Resistors, tantalum and film capacitors Scale player expanding through acquisitions
Panasonic Industry ~5–7% Aluminum polymer capacitors, resistors Strong Japanese automaker relationships
Vishay Intertechnology ~5–7% Shunt resistors, inductors, film capacitors Specialty power and sensing components
KYOCERA AVX ~4–6% Tantalum, ceramic capacitors, supercapacitors High-reliability niche focus
Taiyo Yuden ~3–5% MLCCs, power inductors Miniaturized high-capacitance parts
ROHM Semiconductor ~2–4% Shunt resistors, chip resistors Integration with SiC power devices
Würth Elektronik ~2–3% EMC components, inductors Design-support-led EMC specialist

Recent News & Developments

The developments below illustrate how capacity, regulation and consolidation are reshaping the Automotive Passive Electronic Component Market.

  • NHTSA (April 2024): Finalized FMVSS No. 127, requiring automatic emergency braking on new light vehicles by September 2029 and expanding sensor and braking electronics demand [4]
  • European Union (May 2024): Published Euro 7 as Regulation (EU) 2024/1257, extending emissions limits and durability requirements that raise electronic control content [5]
  • USTR (May 2024): Concluded its Section 301 review, increasing tariffs on Chinese semiconductors and electric vehicles and prompting supplier diversification [17]
  • Vishay Intertechnology (March 2024): Completed its acquisition of the Newport wafer fab in the UK, strengthening its automotive power and passive integration roadmap [15]
  • TDK Corporation (2024): Expanded its automotive film and ceramic capacitor lineup for 800V inverters and onboard chargers [13]
  • Murata Manufacturing (2024): Introduced higher-capacitance automotive-grade MLCCs in smaller case sizes targeting ADAS and ECU decoupling [12]
  • Yageo Corporation (2025): Pursued a tender offer for Japan's Shibaura Electronics to extend its sensor and specialty component reach [14]

Automotive Passive Electronic Component Market Report Scope

Parameter Details
Market Scope Capacitors, inductors, resistors and EMC filters supplied for automotive electronic systems across OEM and aftermarket channels in passenger and commercial vehicles
Study Period 2021–2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 6.52 Billion
Market Size in 2035 USD 12.83 Billion
CAGR (2026–2035) 7.0%
Fastest Growing Segments Supercapacitors (11.2% CAGR); EMC Filters (8.6% CAGR); Inductors (7.9% CAGR)
Regions Covered North America, Europe, South America, Asia Pacific, Middle East and Africa and ROW
Companies Profiled Murata Manufacturing, TDK Corporation, Samsung Electro-Mechanics, Yageo Corporation, Panasonic Industry, Vishay Intertechnology, KYOCERA AVX, Taiyo Yuden, ROHM Semiconductor, Würth Elektronik
Valuation Currency USD Billion
Methodology 350+ primary expert interviews; bottom-up market sizing; top-down validation; data triangulation; scenario-based forecasting; real-time project tracking

FAQs

How should buyers in the Automotive Passive Electronic Component Market evaluate supplier risk?
Prioritize AEC-Q200 qualification, multi-country production sites and documented conflict-mineral compliance [11][22]. Dual-sourcing critical MLCC values reduces exposure to regional disruptions.
Are polymer capacitors replacing tantalum in vehicles?
Partly. Conductive polymer aluminum capacitors offer lower ESR and avoid tantalum sourcing risk, though tantalum still wins where volumetric efficiency matters most [10].
What lead times are typical for automotive-grade passives?
Standard automotive MLCCs normally ship in 10–16 weeks. Specialty high-voltage film capacitors can exceed 20 weeks during demand peaks [12].
Which emerging use case could reshape the Automotive Passive Electronic Component Market?
Solid-state battery packs and wireless EV charging. Both require new high-frequency inductors and resonant capacitors with tight tolerances.
How do aftermarket channels differ from OEM supply?
Aftermarket demand centers on replacement modules rather than discrete parts. Margins run higher, but volumes depend on vehicle parc age and repair regulations [21].
What qualification hurdle slows new entrants in the Automotive Passive Electronic Component Market?
Production part approval with automakers can take 18–36 months. New suppliers must also demonstrate parts-per-billion defect rates [11].
Does vehicle-to-grid charging affect component specifications?
Yes. Bidirectional chargers face more frequent power cycling, demanding capacitors and inductors rated for higher ripple current and longer operating hours.
Author
Author Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author Co-Author Profile Sejal Akre LinkedIn Senior Research Analyst
She has over 5 years of rich experience, in market research and consulting providing valuable market insights to client. Hands on expertise in management consulting, and extensive knowledge in domain including ICT, Automotive & Transportation and Aerospace & Defense. She is skilled in Go-to market strategy, industry analysis, market sizing, in depth company profiling, competitive intelligence & benchmarking and value chain amongst others.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















