Automotive HVAC Market (2026 - 2035)

Automotive HVAC Market Research Report By Technology Type (Manual/Semi-automatic HVAC, Automatic HVAC), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Buses and Coaches), By Component (Compressor, Condenser, Evaporator, Electronic and Sensor Suites), By Propulsion Type (ICE Vehicles, Hybrid and Plug-In Hybrid Vehicles, Battery Electric Vehicles), By Sales Channel (OEM Factory-Fit, Aftermarket) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Forecast to 2035
ID: MRFR/AT/1577-HCR 200 Pages Shubham Munde, Sejal Akre Last Updated: September 15, 2026
Automotive HVAC Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.62%
2025 Market SizeUSD 63.58 Billion
2035 Market SizeUSD 109.85 Billion
Key Players
Denso Corporation
Hanon Systems
Valeo SA
MAHLE GmbH
Sanden Holdings
Marelli Holdings
Opportunities
  • Integrated Thermal-Management Platforms for BEV
  • Software-Defined Climate Personalization
  • Emerging-Market Production Expansion

Automotive HVAC Market Summary

The Automotive HVAC Market reached a valuation of USD 63.58 Billion in 2025 and is projected to grow from USD 67.15 Billion in 2026 to USD 109.85 Billion by 2035, expanding at a CAGR of 5.62% across the forecast period. This trajectory reflects the convergence of tighter passenger comfort regulations — particularly the EU's updated CO₂ and cabin-air-quality mandates — and accelerating fleet electrification programs that fundamentally reshape thermal management architectures. As global automakers commit over USD 600 billion to electrification through 2030 [1], HVAC systems sit at the center of the engineering challenge: balancing range preservation with passenger comfort.

The transformation in technology that is happening in the Automotive HVAC Market is huge. Electric compressor platforms, multi-zone automatic climate control, and integrated heat pump circuits specifically built for battery-electric drivetrains are replacing legacy belt-driven compressors and single-zone manual systems. China’s Ministry of Industry and Information Technology now mandates all new-energy cars sold domestically to pass thermal-management compliance testing [2], prompting vendors to invest in next-generation architectures.


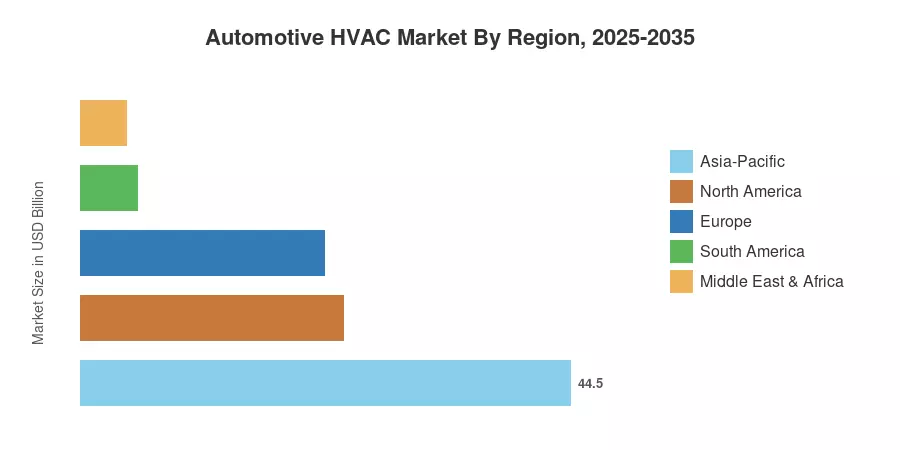
Asia-Pacific commands the dominant position in the Automotive HVAC Market, holding approximately 44.5% of global revenue in 2025, and the region continues to post the highest growth trajectory at a 5.99% CAGR through 2035. North America accounts for roughly 23.9% of global share, driven by strong pickup-truck and SUV production volumes, while Europe contributes around 22.2%, anchored by stringent Euro 7 emission and cabin filtration standards. The decade ahead will reward suppliers capable of delivering lightweight, refrigerant-efficient, and software-defined climate platforms across all vehicle segments.

Key Report Takeaways

• By Technology Type

  • Manual and semi-automatic HVAC systems represented 62.2% of the Automotive HVAC Market in 2025, reflecting their entrenchment across budget and mid-tier vehicle platforms.
  • Automatic HVAC systems are advancing at a 10.1% CAGR through 2035, propelled by the integration of cabin-sensor arrays and consumer preference for personalized comfort in the Automotive HVAC Market.

• By Vehicle

  • Passenger cars captured the largest vehicle-type share in the Automotive HVAC Market, while buses and coaches are expanding at the fastest rate among vehicle categories.


• By Component

  • Passenger cars captured the largest vehicle-type share in the Automotive HVAC Market, while buses and coaches are expanding at the fastest rate among vehicle categories.
  • Compressors held a 34.2% share of the component mix in 2025, remaining the highest-value individual component across the Automotive HVAC Market.

• By Region

  • Asia-Pacific dominated global revenue with a 44.5% share in 2025, while also posting the strongest regional CAGR through 2035.
  • North America and Europe together accounted for over 46% of the Automotive HVAC Market in 2025.

Market Size and Forecast (2021–2035)

Market Research Future estimates incorporate primary interviews with OEM procurement leads, Tier-1 supplier disclosures, trade association datasets, and macroeconomic production forecasts. Historical figures (2021–2024) rely on verified shipment and revenue data; forecast values (2026–2035) apply a calibrated compound growth model validated against regional production outlooks.
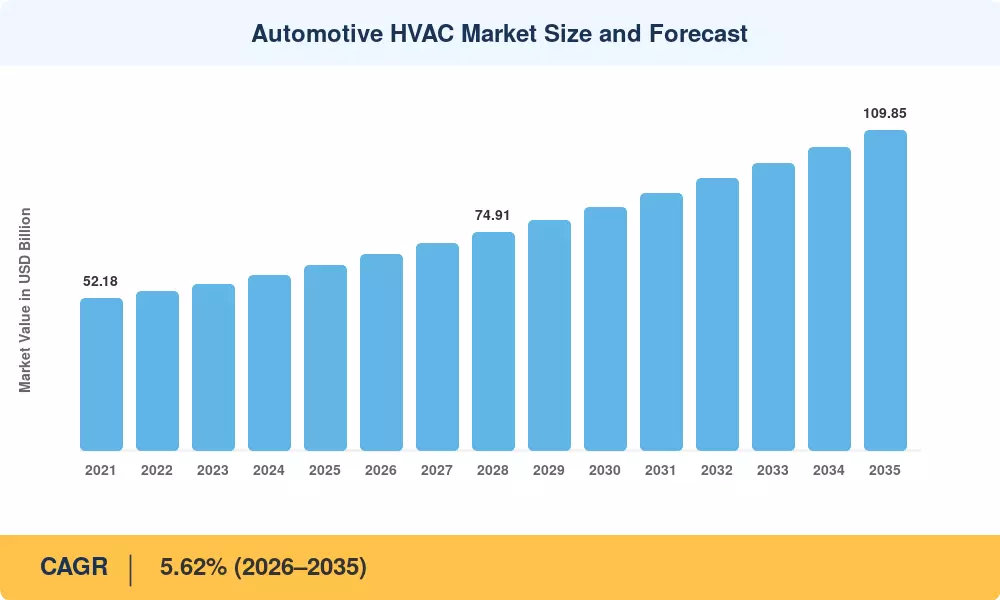
Automotive HVAC Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Global fleet electrification mandates +1.4% Global Long-term (≥4 yr)
Automatic climate-control mass-market diffusion +1.1% North America, Europe Medium-term (2–4 yr)
Tightening cabin air-quality and filtration regulations +0.8% Europe, China Short-term (≤2 yr)
Heat-pump adoption in BEV thermal management +0.9% Global Medium-term (2–4 yr)
Rising vehicle production in ASEAN and India +0.6% Asia-Pacific Long-term (≥4 yr)
Low-GWP refrigerant transition (HFO-1234yf, CO₂) +0.5% Europe, Japan Medium-term (2–4 yr)
Connected-vehicle HVAC pre-conditioning features +0.3% North America, Europe Long-term (≥4 yr)


Fleet Electrification Mandates

Government mandates are changing the Automotive HVAC Market rules. Together, the EU’s 2035 ICE phase-out, California’s Advanced Clean Cars II rule and China’s dual-credit strategy encompass markets accounting for more than 60% of worldwide light-vehicle production [1]. Electric vehicles call for fundamentally different thermal architectures, i.e., electric compressors, battery chillers, and cabin heat pumps instead of belt-driven units, resulting in a per-vehicle HVAC content increase of 25-40% above comparable ICE versions [12].


Automatic Climate-Control Diffusion

What was once a luxury-tier feature is now penetrating B- and C-segment vehicles worldwide. OEMs in the Automotive HVAC Market use multi-zone automatic systems as a low-cost differentiator.

Cabin Air-Quality Regulations

Regional regulatory frameworks are increasing focus on in-cabin air purity. While Euro 7 introduces vehicle non-exhaust emissions rules for brake and tire wear, standards like China’s GB/T 27630 enforce strict interior volatile organic compound (VOC) limits. Consequently, OEMs are expanding sensor-driven filtration modules, HEPA units, and active purification technologies across new vehicle architectures.

Heat-Pump Adoption in BEV Platforms

Heat pumps recover waste heat from the electric drivetrain and compress ambient thermal energy to warm the cabin, improving cold-weather range by 15–25% compared to resistive heaters [9]. This technology migration expands the addressable content per vehicle within the Automotive HVAC Market and diversifies supplier revenue toward higher-margin integrated thermal modules.

Restraints Impact Analysis

The restraint impacts below follow the same directional methodology as Section 4. Negative percentages indicate estimated drag on the overall CAGR.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High component cost for BEV thermal systems –0.6% Global Medium-term (2–4 yr)
Refrigerant regulatory fragmentation –0.4% Global Short-term (≤2 yr)
Semiconductor supply volatility –0.3% Global Short-term (≤2 yr)
Weight and packaging constraints in compact EVs –0.3% Asia-Pacific, Europe Long-term (≥4 yr)
Aftermarket cannibalization by sealed OEM modules –0.2% North America Long-term (≥4 yr)


BEV Thermal-System Cost Premiums

Compressor electrification, chiller loops, and heat-pump circuits add engineering complexity that Tier-1 suppliers must absorb or pass through. For price-sensitive segments in India and Southeast Asia, this cost gap slows adoption rates and constrains the Automotive HVAC Market expansion in the fastest-growing production corridors.

Refrigerant Regulatory Fragmentation

The global refrigerant landscape remains fractured. Europe mandates low-GWP alternatives under the F-Gas Regulation, Japan has adopted R-744 (CO₂) for several OEMs, and much of the developing world still relies on R-134a [10].

Semiconductor Supply Constraints

Automatic climate systems use microcontrollers, MEMS pressure sensors, and CAN-bus interface chips. The semiconductor crisis of 2021-2023 has shown that a lack of supply of a single node can shut down HVAC module manufacture lines for weeks [13]. Supply circumstances have improved, but the industry’s just-in-time strategy remains sensitive to geopolitical events and decisions on foundry allocations.


Automotive HVAC Market Opportunities

Integrated Thermal-Management Platforms for BEV

Automakers increasingly prefer a single-supplier thermal module combining cabin HVAC, battery cooling, and motor thermal circuits. This "super-system" approach roughly triples the conventional HVAC module value — and opens a high-margin opportunity for suppliers with cross-domain engineering capabilities.

Software-Defined Climate Personalization

Over-the-air (OTA) update platforms let automakers sell HVAC feature upgrades — fragrance diffusion profiles, air-purification modes, and energy-optimized comfort algorithms — as subscription services. This data-monetization model transforms the Automotive HVAC Market from a one-time hardware sale into a recurring software revenue stream.

Emerging-Market Production Expansion

India’s Production-Linked Incentive (PLI) strategy for automotive components and Indonesia’s EV battery investment roadmap are attracting tier-1 HVAC suppliers to set up local manufacturing [6]. These markets have labor cost advantages and rising local demand, making them well-positioned for early movers to gain share in the deepening Automotive HVAC Market in South and Southeast Asia.


Advanced Filtration and Air-Purification Modules

Post-pandemic consumer awareness of in-cabin air quality has elevated demand for HEPA, activated-carbon, and ionizer-equipped HVAC systems. The Automotive HVAC Market stands to benefit from OEMs marketing cabin health as a competitive differentiator, particularly in pollution-heavy urban corridors across China and India.

Low-GWP Refrigerant and CO₂-Based Systems

The regulatory sunset of high-GWP refrigerants creates a replacement cycle across millions of vehicles. Suppliers capable of delivering R-744 or HFO-1234yf-compatible compressors and heat exchangers will capture upgrade and retrofit revenue alongside OEM factory-fit demand [10].

Automotive HVAC Market Future Outlook

Electrification Supercycle and Thermal Integration

The global transition to electric drivetrains will remain the dominant structural force shaping the Automotive HVAC Market through 2035. IEA projections indicate that total electric vehicle sales share (BEVs plus PHEVs) is projected to reach ~40–45% by 2030 under Stated Policies (STEPS) and ~50% by 2035 in exploratory scenarios, making integrated thermal-management modules — combining cabin HVAC, battery thermal conditioning, and motor cooling — the default architecture for new platforms.

AI-Driven Cabin Comfort and Predictive Climate Control

Machine-learning algorithms that anticipate passenger thermal preferences based on biometric inputs, weather forecasts, and route data will redefine climate-system intelligence. By 2030, shifting differentiation in the Automotive HVAC Market from hardware spec sheets to software sophistication.

ESG Reporting and Sustainable Refrigerant Mandates

Corporate sustainability disclosures now include Scope 3 supply-chain emissions, pushing HVAC suppliers to explain refrigerant lifecycle impacts and choose low-GWP alternatives. The Kigali Amendment’s phasedown plan requires an 85% reduction in HFC consumption by 2036 [10], further hastening the migration to natural refrigerants throughout the Automotive HVAC Market.


Autonomous-Vehicle Cabin Redesign

Level 4 autonomous vehicles eliminate traditional forward-facing seating constraints, enabling lounge-style interiors where occupant comfort becomes the primary design objective. HVAC systems in these cabins must deliver personalized micro-climate zones without relying on dashboard vents, opening a new premium-content opportunity for the Automotive HVAC Market.

Regional Market Share Analysis

Region Metric Primary Investment Themes
Asia-Pacific 44.5% share (2025) BEV thermal management, local-content mandates
North America 23.9% share (2025) Pickup/SUV climate systems, EV transition
Europe 22.2% share (2025) Euro 7 compliance, low-GWP refrigerants
South America 5.2% share (2025) Compact-vehicle HVAC, import substitution
Middle East & Africa 4.2% share (2025) High-capacity cooling, fleet modernization
Total 100%

The Automotive HVAC Market follows global vehicle production regions closely, with Asia-Pacific anchoring nearly half of total revenue, followed by North America and Europe.


North America

Country Metric Key Driver
US 68.4% of regional share Full-size truck and SUV HVAC content
Canada 14.7% of regional share Cold-climate heat-pump demand
Mexico 16.9% of regional share Export-oriented assembly plants


North American demand within the Automotive HVAC Market is shaped by the region's preference for larger vehicles with multi-zone climate systems. The US Inflation Reduction Act's EV tax credits accelerate electric-compressor adoption, while Mexico's expanding role as a nearshoring production hub draws Tier-1 HVAC suppliers to Nuevo León and Guanajuato [15].

Europe

Country Metric Key Driver
Germany 5.85% CAGR (2026–2035) Premium OEM concentration
UK USD 2.38 Billion (2025) Post-Brexit EV strategy
France 5.52% CAGR (2026–2035) Renault/Stellantis electrification
Italy USD 1.62 Billion (2025) Compact-car HVAC optimization
Spain 5.48% CAGR (2026–2035) Battery-plant investment spillover
Nordic Countries USD 0.74 Billion (2025) Cold-climate heat-pump leadership
Russia 4.20% CAGR (2026–2035) Domestic-brand HVAC localization
Rest of Europe USD 2.65 Billion (2025) Mixed production recovery


European regulatory ambition drives the Automotive HVAC Market here. The F-Gas Regulation phase-down schedule and Euro 7 cabin filtration standards compel OEMs to re-engineer HVAC modules, while Germany's premium automakers lead global adoption of tri-zone and quad-zone automatic systems [8].

Asia-Pacific

Country Metric Key Driver
China 52.3% of regional share World's largest NEV production base
India 6.78% CAGR (2026–2035) PLI scheme, rising car ownership
Japan USD 4.15 Billion (2025) R-744 heat-pump innovation
South Korea 5.95% CAGR (2026–2035) Hyundai-Kia EV platform scale
ASEAN USD 2.42 Billion (2025) Assembly-hub expansion
Rest of Asia-Pacific 4.90% CAGR (2026–2035) Emerging-market motorization


Asia-Pacific anchors the Automotive HVAC Market through sheer production scale and aggressive electrification timelines. China alone produced over 30 million vehicles in 2024, with new-energy vehicles exceeding 40% of sales [2]. Indian Tier-1 suppliers such as Subros and Sanden Vikas expand local capacity to serve domestic OEMs as annual car sales push toward 5 million units.

South America

Country Metric Key Driver
Brazil 62.5% of regional share Flex-fuel fleet modernization
Argentina USD 0.58 Billion (2025) Light-commercial vehicle assembly
Rest of South America 4.85% CAGR (2026–2035) Import-substitution incentives


Brazil's ROTA 2030 automotive industrial policy incentivizes energy-efficient components, creating pull for upgraded HVAC modules in the Automotive HVAC Market across the Mercosur trade bloc [16].

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 34.8% of regional share Vision 2030 automotive localization
UAE 5.72% CAGR (2026–2035) Premium-vehicle import demand
South Africa USD 0.52 Billion (2025) Regional assembly hub
Egypt 5.15% CAGR (2026–2035) Domestic production ramp-up
Rest of MEA USD 0.64 Billion (2025) Fleet replacement cycles


Extreme ambient temperatures across the Middle East make high-capacity cooling systems essential. Saudi Arabia's push to localize automotive assembly under Vision 2030 is drawing HVAC suppliers to establish finishing and integration facilities within the kingdom [17].

Automotive HVAC Market By Region, 2025-2035

Automotive HVAC Market Segmentation

By Technology Type

Segment Metric Primary Demand Driver
Manual/Semi-automatic HVAC 62.2% share (2025) Budget and mid-tier vehicle platforms
Automatic HVAC 10.1% CAGR (2026–2035) Multi-zone personalization, sensor integration


Manual and semi-automatic systems retain the majority share in the Automotive HVAC Market because they remain standard-fit across A-, B-, and C-segment vehicles in price-sensitive regions such as India, ASEAN, and South America. Their engineering simplicity and lower bill-of-materials cost sustain volume dominance even as automatic systems gain ground.

Automatic HVAC systems are the fastest-growing technology segment in the Automotive HVAC Market, driven by falling sensor costs and OEM strategies to differentiate through cabin comfort. Dual- and tri-zone configurations now appear in vehicles priced below USD 25,000 in China, compressing the traditional luxury-only positioning.

By Vehicle Type

Segment Metric Primary Demand Driver
Passenger Cars 74.1% share (2025) Dominant global production volume
Light Commercial Vehicles USD 10.52 Billion (2025) Last-mile delivery fleet expansion
Buses and Coaches 7.04% CAGR (2026–2035) Urban transit electrification


Passenger cars anchor the Automotive HVAC Market by volume, though per-vehicle HVAC content is rising fastest in battery-electric models that require electric compressors and heat-pump circuits. Buses and coaches represent the fastest-growing vehicle segment, driven by municipal zero-emission fleet procurement mandates in Europe and China.

By Component

Segment Metric Primary Demand Driver
Compressor 34.2% share (2025) Core refrigerant-cycle component
Condenser USD 9.80 Billion (2025) Increased heat-rejection requirements
Evaporator 5.25% CAGR (2026–2035) Multi-zone cabin configurations
Electronic and Sensor Suites 7.29% CAGR (2026–2035) Smart climate control and diagnostics


Compressors remain the highest-value component in the Automotive HVAC Market, and the shift from mechanical to electric compressors is lifting average selling prices by 20–30%. Electronic and sensor suites are gaining share rapidly as automatic climate systems require temperature, humidity, solar-load, and particulate sensors.

By Propulsion Type

Segment Metric Primary Demand Driver
ICE Vehicles USD 28.85 Billion (2025) Legacy fleet dominance
Hybrid and Plug-In Hybrid Vehicles 6.45% CAGR (2026–2035) Transitional powertrain adoption
Battery Electric Vehicles 10.42% CAGR (2026–2035) Integrated thermal management demand


Battery-electric vehicles are the fastest-growing propulsion segment in the Automotive HVAC Market, commanding higher per-unit HVAC content due to heat-pump integration and battery thermal-management loops.

By Sales Channel

Segment Metric Primary Demand Driver
OEM Factory-Fit 76.3% share (2025) Vehicle-production-line integration
Aftermarket 6.47% CAGR (2026–2035) Retrofit and replacement cycles


OEM factory-fit installations dominate the Automotive HVAC Market because modern HVAC modules are deeply integrated into vehicle electrical and refrigerant architectures. The aftermarket channel grows faster in percentage terms, driven by replacement demand in aging fleets across South America and the Middle East.

Competitive Benchmarking

The Automotive HVAC Market exhibits medium concentration, with the top five suppliers accounting for an estimated 48–55% of global revenue. The Herfindahl-Hirschman Index sits in the 800–1,200 range, indicating a competitive but not fragmented landscape. Tier-1 thermal specialists compete alongside diversified automotive-component conglomerates, and recent M&A activity has consolidated several mid-tier players into larger platform groups.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Denso Corporation ~10–14% Electric compressors, integrated thermal modules Full-system thermal integration leader
Hanon Systems ~8–12% Heat pumps, compressors, fluid-transport lines BEV thermal-management specialist
Valeo SA ~7–10% Climate-control modules, cabin filtration Software-defined comfort innovator
MAHLE GmbH ~6–9% AC compressors, thermal management Electrification-focused component supplier
Sanden Holdings ~4–7% Scroll compressors, eco-friendly refrigerant systems CO₂ refrigerant technology pioneer
Marelli Holdings (Calsonic Kansei) ~3–6% Integrated HVAC units, heat exchangers Japanese OEM partnership depth
Gentherm Inc. ~2–4% Thermoelectric seat climate, battery thermal Micro-climate comfort specialist
BorgWarner Inc. ~2–4% Cabin heaters, coolant heaters, eFan modules Powertrain-to-thermal crossover
Dana Incorporated ~2–3% Battery and cabin thermal management Commercial-vehicle thermal focus
Subros Limited ~1–3% AC compressors, condensers, evaporators Indian-market HVAC leader


Recent News & Developments

  • Denso Corporation (October 2017): Announced a USD 1 billion investment to expand its Maryville, Tennessee manufacturing unit, turning the site into Denso's primary North American production center for electric vehicle systems, safety electronics, and advanced connectivity products.
  • Hanon Systems (January 2025): Hankook & Company Group completed its acquisition of a majority controlling stake in Hanon Systems, consolidating the world's second-largest automotive thermal management provider into a unified tire, battery, and thermal platform.
  • Valeo SA (October 2024): Unveiled Predict4Range at the Paris Motor Show, an AI-based software solution that optimizes BEV thermal management, battery pre-conditioning, and cabin climate energy consumption to maximize winter driving range and charging speed.
  • European Commission (May 2024): Enacted Euro 7 standards (Regulation 2024/1257), establishing new threshold limits for tailpipe emissions, brake particle emissions, tire abrasion, and battery durability standards across passenger cars, light commercial vehicles, and heavy-duty trucks.


Automotive HVAC Market Report Scope

Parameter Detail
Market Scope Global Automotive HVAC Market — systems, components, and aftermarket services
Study Period 2021–2035
CAGR (Forecast) 5.62% (2026–2035)
Market Size (2025) USD 63.58 Billion
Market Size (2035) USD 109.85 Billion
Fastest Growing Segments Automatic HVAC (by technology); Battery Electric Vehicles (by propulsion); Buses & Coaches (by vehicle type)
Companies Profiled Denso, Hanon Systems, Valeo, MAHLE, Sanden, Marelli, Gentherm, BorgWarner, Dana, Subros
Valuation Currency USD Billion

FAQs

How does HVAC system weight affect electric-vehicle driving range?
Lightweighting HVAC modules using aluminum alloys and structural polymers reduces overall vehicle mass, lowering battery energy consumption per mile and extending usable driving range on electric platforms.  
Which refrigerant transition poses the greatest procurement risk for fleet operators?
The R-134a to HFO-1234yf switch creates dual-inventory burdens and requires technician retraining. Fleet operators should negotiate OEM-backed service agreements that guarantee refrigerant supply continuity through 2030 [10].
What role do over-the-air updates play in Automotive HVAC Market differentiation?
OTA-enabled HVAC systems allow automakers to deploy comfort algorithms, energy-optimization profiles, and seasonal calibrations post-sale. This transforms climate control into a recurring software-revenue channel [11].
How do aftermarket HVAC retrofits compare in cost-effectiveness to OEM replacements?
Aftermarket replacement components reduce repair costs compared to OEM parts. Fleet managers must verify electronic control integration and low-GWP refrigerant compatibility before installation.
What cybersecurity risks exist in connected Automotive HVAC Market systems?
Connected climate modules share the vehicle's CAN bus, exposing potential attack vectors. ISO/SAE 21434 compliance and encrypted OTA channels are now baseline expectations for Tier-1 suppliers [13].
How does cabin pre-conditioning affect battery degradation in BEVs?
Grid-powered pre-conditioning adjusts cabin and battery temperatures before driving, conserving traction battery energy for propulsion while reducing high-current thermal stress during initial operation.
What due-diligence factors should investors evaluate in Automotive HVAC Market suppliers?
Key investment indicators include electric-compressor production capacity, low-GWP refrigerant platform readiness, and Tier-1 contract backlogs across high-voltage electric vehicle architectures.    
Author
Author Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author Co-Author Profile Sejal Akre LinkedIn Senior Research Analyst
She has over 5 years of rich experience, in market research and consulting providing valuable market insights to client. Hands on expertise in management consulting, and extensive knowledge in domain including ICT, Automotive & Transportation and Aerospace & Defense. She is skilled in Go-to market strategy, industry analysis, market sizing, in depth company profiling, competitive intelligence & benchmarking and value chain amongst others.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, automotive engineering journals, technical publications, and authoritative transportation organizations. Key sources included the US Environmental Protection Agency (EPA), National Highway Traffic Safety Administration (NHTSA), European Chemicals Agency (ECHA) refrigerant regulations, European Automobile Manufacturers' Association (ACEA), Society of Automotive Engineers (SAE International), International Organization of Motor Vehicle Manufacturers (OICA), Japan Automobile Manufacturers Association (JAMA), Automotive Research Association (ARA), Mobile Air Conditioning Society (MACS) Worldwide, Air-Conditioning, Heating, and Refrigeration Institute (AHRI), EU Eurostat Transport Database, International Energy Agency (IEA) Global EV Outlook, US Department of Transportation (DOT), Transport Canada, VDA (German Association of the Automotive Industry), China Association of Automobile Manufacturers (CAAM), and national transport ministry reports from key markets. These sources were used to collect vehicle production statistics, refrigerant regulatory frameworks, fuel efficiency standards, EV adoption trends, thermal management technology assessments, and competitive landscape analysis for conventional HVAC systems, heat pump technologies, and electric vehicle thermal management solutions.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consist of CEOs, CTOs, VPs of Engineering, global leaders of Thermal Systems, and directors of Product Development from Tier 1 HVAC manufacturers, compressor suppliers, and automotive thermal management solution providers. Demand-side sources included the heads of Procurement and HVAC commodity buyers from major OEMs (Original Equipment Manufacturers), fleet managers from commercial vehicle operators, directors of Aftermarket Services, and engineering leaders from electric vehicle manufacturers. The primary research validated market segmentation across fuel types and vehicle categories, confirmed technology roadmap timelines, and gathered insights on the adoption patterns of heat pump systems in EVs, refrigerant transition strategies (R-1234yf, CO2, R-744), pricing dynamics for compressors and heat exchangers, and supply chain strategies for thermal management components.

Primary Respondent Breakdown:

By Designation: C-level Primaries (40%), Director Level (32%), Others (28%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and vehicle production volume analysis. The methodology included:

Identification of over 50 critical Tier 1 and Tier 2 suppliers in North America, Europe, Asia-Pacific, and Latin America

Product mapping across conventional HVAC systems, heat pump technologies, ventilation systems, and thermal management systems for electric vehicles

Component-level analysis covering compressors, evaporators, condenser units, expansion valves, and electronic control modules

Analysis of reported and modeled annual revenues specific to automotive HVAC and thermal management portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (vehicle production volume × HVAC system ASP by region and fuel type) and top-down (supplier revenue validation) approaches to derive segment-specific valuations across passenger vehicles, commercial vehicles, and heavy-duty applications

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















