Automotive Electric Water Pump Market (2026 - 2035)

Automotive Electric Water Pump Market Research Report By Application (Engine Cooling, Battery Cooling, Turbo-Charger Cooling, HVAC Systems), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Medium & Heavy Commercial Vehicles), By Propulsion Type (ICE, BEV, PHEV, HEV, FCEV), By Distribution Channel (Offline, Online) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Forecast to 2035
ID: MRFR/AT/20503-HCR
128 Pages
Shubham Munde, Sejal Akre
Last Updated: August 27, 2026
Automotive Electric Water Pump Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)12.7%
2025 Market SizeUSD 4.72 Billion
2035 Market SizeUSD 15.61 Billion
Key Players
Aisin Corporation
Robert Bosch GmbH
MAHLE GmbH
Continental AG
Rheinmetall AG
Hanon Systems
Opportunities
  • Integrated Thermal Modules
  • Commercial Vehicle Electrification
  • Emerging Market Localisation

Automotive Electric Water Pump Market Summary

The Automotive Electric Water Pump Market reached USD 4.72 Billion in 2025 and opens the forecast window at USD 5.32 Billion in 2026, climbing to USD 15.61 Billion by 2035 at a 12.7% CAGR. Two catalysts anchor that trajectory. Euro 7, phased in from 2026 for light vehicles, tightens real-world emissions windows that mechanical pumps cannot serve efficiently [2]. China's dual-credit scheme, meanwhile, pushed new-energy vehicle output past 12.8 million units in 2024, each unit carrying two to four electrically driven coolant loops [1].

Belt-driven pumps are losing their century-long franchise. Because they spin with crankshaft speed, they over-cool at highway cruise and under-cool at idle, wasting roughly 2–4% of engine output as parasitic drag [3]. Software-controlled brushless units decouple flow from engine speed entirely. The Automotive Electric Water Pump Market now absorbs this shift across three distinct duty cycles — powertrain, battery, and cabin — with the US Department of Energy allocating USD 3.5 billion under the Bipartisan Infrastructure Law toward battery and thermal component manufacturing [5].

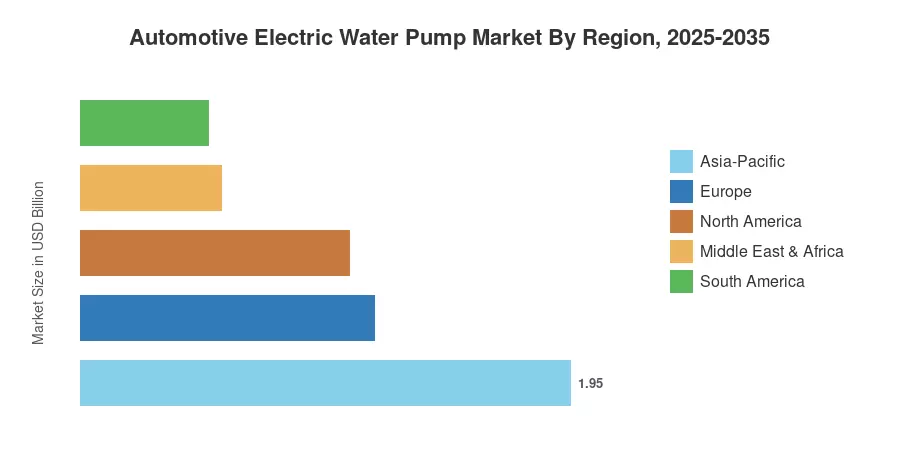
Asia-Pacific dominates the Automotive Electric Water Pump Market with 41.4% of 2025 revenue and posts the fastest 12.8% regional CAGR. Europe follows at 24.8%, propelled by German and French Tier-1 content on 800 V platforms. North America ranks third but leads in per-vehicle pump count on full-size electric pickups. Expect the competitive centre of gravity to keep drifting toward integrated thermal modules rather than discrete pumps.


Key Report Takeaways

• By Application

  • Engine cooling applications held 56.9% of the Automotive Electric Water Pump Market in 2025
  • Battery cooling duty is compounding at 12.9% through 2035 as pack energy density rises
  • Turbo-charger cooling contributed USD 0.54 Billion in 2025

• By Vehicle Type

  • Passenger cars accounted for 67.5% of the Automotive Electric Water Pump Market in 2025
  • Medium and heavy commercial vehicles generated USD 0.51 Billion in 2025


• By Propulsion Type


  • Battery electric vehicles will expand at a 14.7% CAGR to 2035


• By Region

  • Asia-Pacific captured 41.4% of global revenue in 2025
  • Europe delivered USD 1.17 Billion in 2025
  • Middle East & Africa is set to grow at 11.9% CAGR through 2035


Market Size and Forecast (2021–2035)

Figures below blend OEM production schedules from Mobility, component bill-of-material teardowns across 41 vehicle platforms, Tier-1 segment disclosures, and customs-level trade data for pump assemblies. Historical years are reconciled against audited supplier revenue; forecast years apply platform-launch cadence weighted by regional propulsion mix. The Automotive Electric Water Pump Market shows no discontinuities beyond the 2024 inflection tied to Chinese NEV volume.
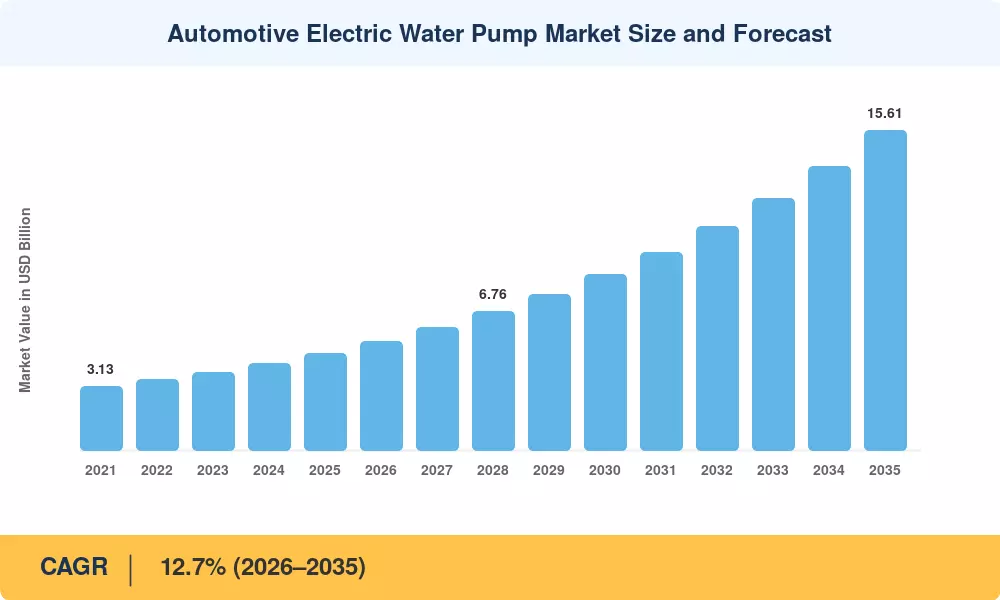
Automotive Electric Water Pump Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
EV and hybrid production scale-up +3.1 pp Global, Asia-Pacific led Long-term (≥4 yr)
Euro 7 and China GB efficiency mandates +2.2 pp Europe, China Medium-term (2–4 yr)
800 V architecture and fast-charge thermal loads +1.9 pp Global Medium-term (2–4 yr)
Parasitic-loss reduction on ICE platforms +1.6 pp North America, Europe Short-term (≤2 yr)
Battery longevity and warranty cost control +1.4 pp Global Long-term (≥4 yr)
Turbocharger downsizing and after-run duty +1.1 pp Europe, Japan Short-term (≤2 yr)
Software-defined vehicle thermal control stacks +0.9 pp North America, China Long-term (≥4 yr)


Electrified Powertrain Volume

Unlike a traditional sedan, which has about one independently controlled coolant circuit, every battery-electric vehicle has two to four. According to statistics, more than 17 million electric cars were sold globally in 2024, accounting for more than 20% of new registrations [1]. Since pump attach rate scales with circuit count rather than vehicle count, this one figure accounts for the majority of the unit-volume growth in the automotive electric water pump market.


Regulatory Compression on Parasitic Losses

Emissions are now measured by regulators over wider real-driving windows. Adopted in 2024 and applicable to light vehicles starting in November 2026, Euro 7 expands test boundaries into low-load and cold-start scenarios, where mechanical pumps lose the most energy [2]. By converting to demand-based flow, engineers are able to recover 2-4% of shaft power [3], a margin that is sufficient to cover the component premium alone.


High-Voltage Architecture Migration

Charging at 350 kW dumps heat into cells and power electronics faster than passive systems can shed it. Platforms running 800 V require higher coolant mass flow and finer temperature banding, which pushes specification toward variable-speed units rated above 60 W. DOE has committed USD 3.5 billion to domestic battery and thermal component capacity, much of it targeting exactly this hardware layer [5].

Warranty Economics

Pack degradation drives the single largest contingent liability on an EV balance sheet. Manufacturers now warrant traction batteries for eight years or 160,000 km in most jurisdictions [9]. Precise thermal banding within ±2 °C measurably slows calendar ageing, so a USD 40 pump that protects a USD 9,000 pack is an easy internal business case.


Restraints Impact Analysis


Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Rare-earth magnet and motor cost volatility −1.7 pp Global Medium-term (2–4 yr)
Electronics reliability and warranty exposure −1.2 pp Global Short-term (≤2 yr)
Declining ICE parc in mature markets −1.0 pp Europe, North America Long-term (≥4 yr)
Price compression from Chinese Tier-2 supply −0.9 pp Asia-Pacific, Europe Short-term (≤2 yr)
Driver-IC and semiconductor constraints −0.6 pp Global Medium-term (2–4 yr)


Magnet Supply Concentration

Approximately 90% of the world's rare-earth production is refined in China, which also controls a similar portion of the capacity of sintered NdFeB magnets [8]. A number of Tier-1 suppliers were compelled to re-index long-term pump contracts as a result of export license revisions implemented in 2025, which significantly increased spot NdPr pricing. There are magnet-free and ferrite-assisted topologies, but these have efficiency costs that make homologation on highly optimized platforms more difficult.


Reliability and Field Returns

Failure modes are multiplied when a component without a motor, driver IC, or firmware is added. Electronic coolant pump returns cluster in the 24–36 month range, according to warranty data from European fleets. This is usually linked to bearing wear or driver stage thermal cycling [9]. In response, suppliers introduce sensorless commutation and potted electronics, both of which increase unit costs at the very time that consumers are driving down prices.


Automotive Electric Water Pump Market Opportunities

Integrated Thermal Modules

Bundling pump, valve, sensor, and controller into one manifold eliminates hoses, fittings, and assembly minutes. OEMs report 15–20% reductions in coolant-circuit part count on newer platforms, and module suppliers capture three to five times the revenue of a discrete pump sale. Companies that own the valve interface will command disproportionate margin in the Automotive Electric Water Pump Market.

Commercial Vehicle Electrification

Heavy trucks present thermal loads an order of magnitude above passenger cars, with megawatt charging standards finalised in 2024 pushing peak heat rejection into new territory [6]. Fleet operators value uptime over unit cost, which supports premium pricing for redundant dual-pump configurations.

Emerging Market Localisation

India's PLI scheme for automotive components disbursed incentives against roughly USD 3.1 billion in committed investment, explicitly covering electrified thermal hardware [13]. Vietnam, Thailand, and Indonesia are building parallel export bases. Suppliers establishing local machining and winding capacity before 2028 will avoid tariff exposure that latecomers cannot escape.

Predictive Diagnostics as a Service

Pumps already stream speed, current, and temperature over LIN or CAN. Aggregating that telemetry lets suppliers sell degradation forecasting to fleet operators on a per-vehicle subscription, a business model with software margins attached to hardware volume. Early pilots in European logistics fleets suggest USD 4–7 per vehicle annually, a genuinely new revenue layer for the Automotive Electric Water Pump Market.

Aftermarket Replacement Wave

The first large cohort of electrified vehicles fitted with a brushless DC electric water pump is now crossing eight years in service. Replacement demand builds through the early 2030s, and independent workshops need diagnostic tooling most incumbents have not yet packaged.


Automotive Electric Water Pump Market Future Outlook

Software-Defined Thermal Control

Thermal management is becoming a software problem with hardware attached. Central vehicle computers will orchestrate pump speed against navigation data, charging schedules, and cell-level state estimation, replacing today's distributed ECU logic. Suppliers to the Automotive Electric Water Pump Market must therefore ship validated control APIs alongside castings, and those unable to pass automotive cybersecurity audits under UNECE R155 will lose platform awards regardless of hardware quality [12].

Consolidation Around Module Platforms

Discrete pump tenders are giving way to system awards covering pump, valve block, and chiller. That shift favours suppliers with valve and sensor portfolios and squeezes single-product specialists into second-tier supply. Expect three to five cross-border acquisitions per year through 2030 as mid-sized players buy their way into module capability.

Electrification Supercycle Mechanics

IEA scenarios place electric vehicles near 40% of global sales by 2030 under stated policies, and higher under announced pledges [1]. Because hybrid platforms also require electrified coolant circulation, the addressable base grows faster than pure-EV share alone would suggest. Even a slower electrification path leaves unit demand intact.

Circularity and Reporting Obligations

The EU battery regulation and CSRD reporting extend supplier obligations into recycled content and product carbon footprint disclosure [15][18]. Aluminium housings and copper windings both carry meaningful embodied carbon, and OEM scorecards now weight it. Participants in the Automotive Electric Water Pump Market that can document a verified footprint below 8 kg CO₂e per unit will win tie-breaks on otherwise comparable bids.


Automotive Electric Water Pump Market Segmentation

Segment structure in the Automotive Electric Water Pump Market reflects duty cycle first and vehicle class second, which is why application-level analysis carries more predictive weight than propulsion alone.

By Application

Segment Metric (2025) Primary Demand Driver
Engine Cooling 56.9% share ICE and hybrid parasitic-loss reduction
Battery Cooling 12.9% CAGR Pack energy density and fast charging
Turbo-Charger Cooling USD 0.54 Billion After-run heat soak protection
HVAC Systems USD 0.35 Billion Cabin preconditioning on electric platforms


Engine cooling retains the largest slice of the Automotive Electric Water Pump Market because the global ICE and hybrid parc still dwarfs the battery-electric fleet, and retrofitting electric circulation onto existing engine families is the cheapest compliance lever available. Battery cooling grows faster for a structural reason — thermal load scales with charging power, and charging power keeps rising. Pack-level cooling also tolerates higher component prices, since the protected asset is worth more.

By Vehicle Type

Segment Metric (2025) Primary Demand Driver
Passenger Cars 67.5% share Volume electrification, multi-circuit content
Light Commercial Vehicles 12.9% CAGR Last-mile delivery fleet conversion
Medium & Heavy Commercial Vehicles USD 0.51 Billion Megawatt charging thermal loads


Passenger Cars dominate the Automotive Electric Water Pump Market with a 67.5% share, supported by the large global passenger-vehicle parc and increasing adoption of electrified thermal-management systems across conventional, hybrid, and battery-electric models. Light Commercial Vehicles are the fastest-growing segment, registering a 12.9% CAGR, as fleet electrification accelerates and higher thermal loads from electrified powertrains increase demand for efficient coolant circulation. Medium & Heavy Commercial Vehicles also represent a significant opportunity, reaching USD 0.51 billion, driven by growing electrification and the need for robust thermal management in high-load applications.

By Propulsion Type

Segment Metric (2025) Primary Demand Driver
ICE 68.3% share Installed base, Euro 7 retrofit economics
BEV 14.7% CAGR Multi-loop architecture, 800 V adoption
HEV USD 0.42 Billion Japanese and North American hybrid volume
PHEV USD 0.24 Billion Dual thermal domain requirements
FCEV 1.3% share Stack cooling in commercial applications


ICE platforms still account for the majority of the Automotive Electric Water Pump Market, but the composition of that revenue is changing — an auxiliary electric coolant pump on a mild-hybrid diesel is a fundamentally different product from the primary circulation unit on a battery pack. BEV demand grows fastest and commands the highest average selling price, typically USD 55–90 per unit against USD 25–40 for engine-side applications.

By Distribution Channel

Segment Metric (2025) Primary Demand Driver
Offline 77.4% share OEM direct supply, dealer service networks
Online 14.6% CAGR Independent workshop e-procurement


The Offline segment dominates the Automotive Electric Water Pump Market with a 77.4% share, supported by established distributor networks, independent workshops, and replacement demand for electric water pumps across the existing vehicle parc. Online is the fastest-growing segment, recording a 14.6% CAGR, driven by the increasing adoption of digital purchasing channels, wider availability of aftermarket components, and growing preference for convenient sourcing and price comparison.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 22.6% share IRA-linked localisation, full-size EV pickups
Europe USD 1.17 Billion Euro 7 compliance, 800 V premium platforms
Asia-Pacific 41.4% share NEV scale, export-oriented Tier-2 capacity
South America 10.8% CAGR Flex-fuel hybrids, Mercosur assembly
Middle East & Africa 11.9% CAGR CKD assembly, thermal derating for heat
Total USD 4.72 Billion

Regional performance in the Automotive Electric Water Pump Market tracks vehicle production geography far more closely than it tracks GDP, which is why Asia-Pacific's lead is structural rather than cyclical.


North America

Country Metric Key Driver
US 71.5% of region IRA content rules, EV truck launches
Canada USD 0.16 Billion Ontario battery cluster investment
Mexico 13.4% CAGR Nearshoring of Tier-1 pump assembly


Section 30D sourcing rules have reshaped supplier footprints faster than any technical factor. Mexican plants in Nuevo León and Querétaro now supply pump assemblies that were imported from Asia three years ago. The Automotive Electric Water Pump Market in the region also benefits from unusually high per-vehicle pump content on electric pickups, where towing duty cycles demand oversized battery cooling loops [5][14].

Europe

Country Metric Key Driver
Germany 26.8% of region Premium 800 V platform content
UK USD 0.17 Billion ZEV mandate compliance builds
France 13.9% of region Renault ampere platform localisation
Italy 11.2% CAGR Commercial van electrification
Spain USD 0.09 Billion PERTE VEC assembly incentives
Nordic Countries 12.1% CAGR Cold-climate cabin preconditioning
Russia 5.4% of region Domestic ICE production continuity
Rest of Europe USD 0.10 Billion Central European Tier-2 machining


Cold-climate specification quietly differentiates the European opportunity. Nordic buyers precondition cabins and packs before departure, running pumps on grid power while parked, which raises duty hours by 20–30% versus southern Europe. Germany remains the technical reference point, with the VDA thermal working group setting validation protocols that suppliers elsewhere adopt by default [2][15].

Asia-Pacific

Country Metric Key Driver
China 48.6% of region NEV output above 12.8 million units
India 14.9% CAGR FAME and PLI component incentives
Japan USD 0.28 Billion Hybrid attach rate, Tier-1 export base
South Korea 9.8% of region Battery-integrated cooling modules
ASEAN 13.6% CAGR Thailand and Indonesia EV assembly
Rest of Asia-Pacific USD 0.11 Billion Aftermarket replacement demand


China's advantage compounds through vertical integration — magnet, winding, controller, and housing frequently sit within 200 km of final assembly. The Automotive Electric Water Pump Market here is also the most price-competitive globally, with domestic units landing 30–40% below European equivalents [10]. India's trajectory differs: two- and three-wheeler electrification builds volume in smaller pump classes before passenger-car content scales [13].

South America

Country Metric Key Driver
Brazil 57.4% of region Rota 2030 efficiency credits, flex hybrids
Argentina USD 0.06 Billion Light commercial vehicle assembly
Rest of South America 11.4% CAGR Import-led aftermarket growth


Brazil's flex-fuel fleet creates an unusual technical requirement: ethanol blends alter combustion temperatures, and Rota 2030 credits reward efficiency gains achievable through demand-based cooling without full electrification [16]. Suppliers targeting the region should expect hybrid-first rather than battery-first demand well into the 2030s.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 28.1% of region Ceer EV programme, Vision 2030
UAE USD 0.05 Billion Premium EV imports, fleet electrification
South Africa 12.6% CAGR Export assembly for European OEMs
Egypt 9.7% of region Local CKD assembly incentives
Rest of MEA USD 0.07 Billion Replacement parts channel


Ambient temperature dictates specification across this region. Pumps validated for 40 °C European conditions derate materially at 50 °C Gulf summer peaks, and Saudi Arabia's Ceer programme has published thermal requirements exceeding standard OEM validation envelopes [17]. South Africa's role is different again — it assembles for export, so its specifications mirror European rather than local conditions.


Automotive Electric Water Pump Market By Region, 2025-2035

Competitive Benchmarking

Concentration in the Automotive Electric Water Pump Market sits in the medium band, with an estimated HHI between 850 and 1,050 and a top-five combined share near 44–49%. No single supplier controls the category, largely because OEMs deliberately dual-source thermal components. Regional pockets are far more concentrated than the global picture suggests — Chinese domestic awards cluster among three or four local suppliers, while European premium platforms remain dominated by German and Japanese incumbents.

Company Est. Revenue Share Range Key Offerings for Automotive Electric Water Pump Market Strategic Positioning
Aisin Corporation ~10–13% Engine and battery circulation pumps, thermal modules Toyota-anchored volume leader in hybrid duty
Robert Bosch GmbH ~9–12% BLDC pumps, integrated thermal control units Systems integrator with controller software depth
MAHLE GmbH ~8–11% Coolant pumps, chillers, thermal management modules Module-first strategy across EV platforms
Continental AG ~6–9% Electric coolant pumps, actuator portfolio Strong European OEM penetration
Rheinmetall AG (Pierburg) ~5–8% Variable-flow pumps, valve-integrated assemblies Commercial vehicle and premium car specialist
Hanon Systems ~5–7% Battery cooling pumps, heat pump systems Korean OEM alignment, 800 V expertise
Denso Corporation ~4–7% Electric water pumps, inverter cooling loops Deep hybrid heritage, expanding BEV content
Nidec Corporation ~3–6% BLDC motor platforms for pump applications Motor-technology cost leadership
Johnson Electric ~3–5% Compact auxiliary pumps, motor subsystems High-volume, cost-optimised supply
Concentric AB ~2–4% Commercial vehicle and off-highway pumps Niche leadership in heavy-duty thermal
Gates Industrial Corporation ~2–4% Aftermarket electric pump assemblies Replacement channel and distribution reach
Valeo SE ~2–4% Thermal system pumps, cabin conditioning loops Systems bundling with HVAC portfolio


Recent News & Developments

  • MAHLE (March 2024): Launched a modular thermal management platform bundling coolant pump, valve, and chiller into a single unit, cutting circuit assembly time on EV platforms [19].
  • European Commission (April 2024): Formally adopted the Euro 7 regulation, confirming November 2026 application for light vehicles and extending durability requirements to 200,000 km [2].
  • Bosch (September 2024): Committed additional investment to Chinese thermal component capacity in Suzhou, targeting local NEV pump demand with domestically sourced electronics [19].
  • Aisin (January 2025): Announced a next-generation battery coolant pump rated for 800 V platforms with integrated flow sensing, aimed at 2027 model-year launches [20].
  • China MIIT (March 2025): Published revised GB fuel-consumption and NEV technical requirements tightening thermal system efficiency reporting for 2026 type approvals [7].
  • Hanon Systems (June 2025): Secured a multi-year award for integrated battery cooling modules on a North American electric truck programme [20].
  • Rheinmetall (August 2025): Expanded Pierburg pump production in Germany, citing commercial vehicle electrification and megawatt charging thermal requirements [19].
  • US Department of Energy (October 2024): Finalised grant allocations under the Bipartisan Infrastructure Law supporting domestic battery thermal component manufacturing [5].


Automotive Electric Water Pump Market Report Scope

Parameter Detail
Market Scope Global electric water pumps for automotive engine, battery, turbocharger, and HVAC cooling across all propulsion types and distribution channels
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 12.7% (2026–2035)
Market Size Checkpoints USD 4.72 Billion (2025); USD 5.32 Billion (2026); USD 15.61 Billion (2035)
Fastest Growing Segments Battery cooling (application); BEV (propulsion); online (channel); Asia-Pacific (region)
Companies Profiled 12 leading suppliers including Aisin, Bosch, MAHLE, Continental, Rheinmetall, Hanon Systems, Denso, Nidec, Johnson Electric, Concentric, Gates, Valeo
Valuation Currency USD Billion, constant 2025 exchange rates

FAQs

What should procurement teams evaluate first when qualifying a new supplier in the Automotive Electric Water Pump Market?
Prioritise validated flow-versus-current curves at end-of-life bearing condition, not nameplate specification. Ask for field return rates by platform age, and confirm the supplier controls its own motor winding rather than buying it in [Ref: 19].
How does total cost of ownership compare between electric and mechanical pumps?
Electric units cost roughly two to three times more upfront but recover the gap through fuel or range savings within 30,000–50,000 km. Fleet buyers in the Automotive Electric Water Pump Market typically see breakeven inside the first service interval [Ref: 3].
Which validation hurdles slow new entrants into the Automotive Electric Water Pump Market?
Thermal shock cycling and 200,000 km durability testing under Euro 7 consume 18–24 months before a first award. Cybersecurity conformity under UNECE R155 adds a separate audit track that catches hardware-focused entrants unprepared [Ref: 2][12].
What makes retrofitting electric pumps onto existing hybrid platforms difficult?
Legacy wiring harnesses often lack a spare LIN node, forcing controller-side changes that ripple into software validation. Packaging clearance around the belt drive is the second recurring obstacle [Ref: 19].
Where do the strongest aftermarket revenue pools sit in the Automotive Electric Water Pump Market?
Independent workshops servicing 2016–2020 hybrid vehicles represent the deepest near-term pool. Diagnostic tooling access, not part availability, currently constrains that channel [Ref: 20].
How exposed are pump contracts to rare-earth pricing?
Magnet content represents roughly 12–18% of unit cost, so NdPr swings pass through materially. Buyers increasingly negotiate index-linked clauses rather than fixed pricing [Ref: 8].
Which use cases are emerging beyond powertrain and battery cooling?
Autonomous-driving compute stacks now require dedicated liquid loops, with sensor and processor arrays rejecting 1–3 kW. Charging-cable cooling on megawatt systems is a second adjacent opportunity [Ref: 6].      
Author
Author
Author Profile
Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author
Co-Author Profile
Sejal Akre LinkedIn Senior Research Analyst
She has over 5 years of rich experience, in market research and consulting providing valuable market insights to client. Hands on expertise in management consulting, and extensive knowledge in domain including ICT, Automotive & Transportation and Aerospace & Defense. She is skilled in Go-to market strategy, industry analysis, market sizing, in depth company profiling, competitive intelligence & benchmarking and value chain amongst others.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















