Automated Storage and Retrieval System Market (2025 - 2035)

Automated Storage and Retrieval System Market Size, Share and Research Report By Type (Load Based ASRS, Shuttle And Bot-Based ASRS, Carousel Based, Vertical Lift Module (VLM) ASRS), By Industry Vertical (Automotive, Metals And Machinery, Food And Beverages, Chemicals, Healthcare, Semiconductor And Electronics, Retail And E-Commerce, Aviation, Others) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast Till 2035
ID: MRFR/SEM/2599-CR 200 Pages Aarti Dhapte, Shubham Munde Last Updated: September 11, 2026
Automated Storage and Retrieval System Market
Market Size
Forecast Period2025-2035
CAGR (2025-2035)9.10%
2025 Market SizeUSD 11.30 Billion
2035 Market SizeUSD 27.00 Billion
Key Players
Daifuku Co., Ltd.
Dematic
SSI Schaefer
Swisslog
Murata Machinery
Kardex Group
Opportunities
  • Micro-Fulfillment Centers in Urban Retail
  • Cold-Chain Pharmaceutical and Life-Sciences Automation
  • Emerging Market Expansion in Southeast Asia and the Middle East

Automated Storage and Retrieval System Market Summary

The Automated Storage and Retrieval System Market reached USD 11.30 Billion in 2025 and is projected to grow from USD 12.33 Billion in 2026 to USD 27.00 Billion by 2035, expanding at a 9.10% CAGR through the forecast period. Chronic labor shortages across warehouse and distribution operations — compounded by 5–7% annual wage inflation in logistics roles across North America and Europe — have pushed capital-intensive automation from a "nice-to-have" into a boardroom priority [1]. Government incentive programs such as the EU's Digital Decade initiative and the U.S. Inflation Reduction Act's manufacturing provisions are accelerating warehouse modernization capital expenditure [2].

Technology convergence is redefining what an automated storage and retrieval system can deliver. Legacy fixed-aisle crane installations are being augmented — and in some greenfield facilities replaced — by cube-based robotic platforms and AI-driven routing algorithms that cut unplanned downtime by up to 28% . A single mid-size distribution center retrofit averaging USD 8–15 million now yields cycle-time reductions of 35–40% for high-mix SKU profiles, according to industry benchmark data [4]. The Automated Storage and Retrieval System Market benefits directly from the convergence of predictive maintenance analytics and real-time inventory orchestration.

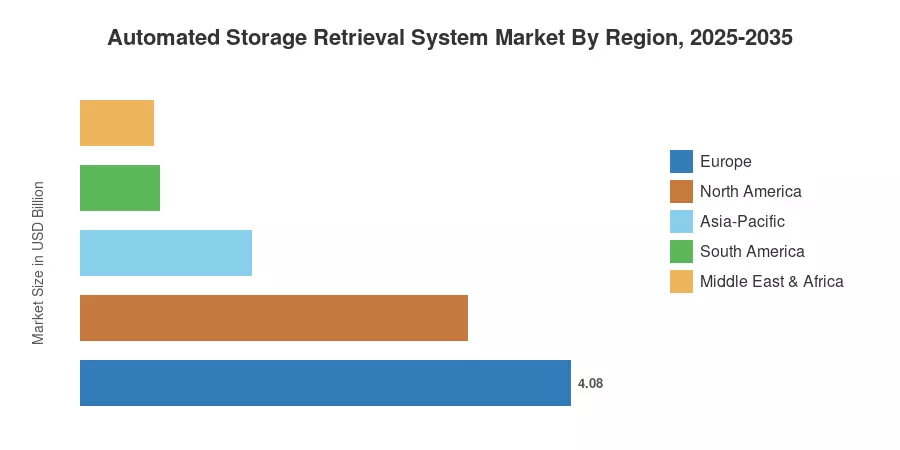
Europe commanded roughly 36.1% of global revenue in 2025, driven by Germany's Industrie 4.0 investments and stringent warehouse-safety directives. Asia-Pacific is the fastest-growing region at a projected 12.60% CAGR, fueled by China's e-commerce infrastructure buildout and India's National Logistics Policy. North America held the second-largest share at approximately 28.5%, anchored by fulfillment center expansion across the U.S. Sunbelt states [5]. The Automated Storage and Retrieval System Market is poised for sustained double-digit expansion in emerging economies through the decade.


Key Report Takeaways

• By Product Type

  • Fixed-aisle crane systems held approximately 34.8% of the Automated Storage and Retrieval System Market in 2025, reflecting their dominance in heavy-pallet manufacturing environments.
  • Cube-based and robotic storage platforms are forecast to register a 12.89% CAGR through 2035, driven by e-commerce fulfillment density requirements.

• By Load Type

  • Unit-load solutions accounted for 38.6% of the Automated Storage and Retrieval System Market share in 2025.
  • Mini-load tote systems represent the fastest-growing load category at 11.96% CAGR, addressing the shift toward small-parcel, high-velocity order profiles.

• By Application

  • Storage and buffering captured 42.1% of the Automated Storage and Retrieval System Market in 2025.
  • Goods-to-person order picking is advancing at a 14.88% CAGR, underpinned by labor-substitution economics.

• By End-User Industry

  • Manufacturing-automotive held a 24.6% share of the Automated Storage and Retrieval System Market in 2025.
  • E-commerce and retail is registering the highest forecast CAGR of 14.25%, reflecting the omnichannel fulfillment imperative.

• By Region

  • Europe contributed 36.1% of Automated Storage and Retrieval System Market revenue in 2025.
  • Asia-Pacific is the fastest-growing regional segment at 12.60% CAGR to 2035.


Automated Storage and Retrieval System Market Size and Forecast (2021–2035)

Market sizing draws on primary interviews with warehouse automation OEMs, system integrators, and end-user procurement teams across 22 countries. Secondary validation incorporates trade-body shipment data, customs statistics, and public filings. All figures are expressed in constant 2025 USD.
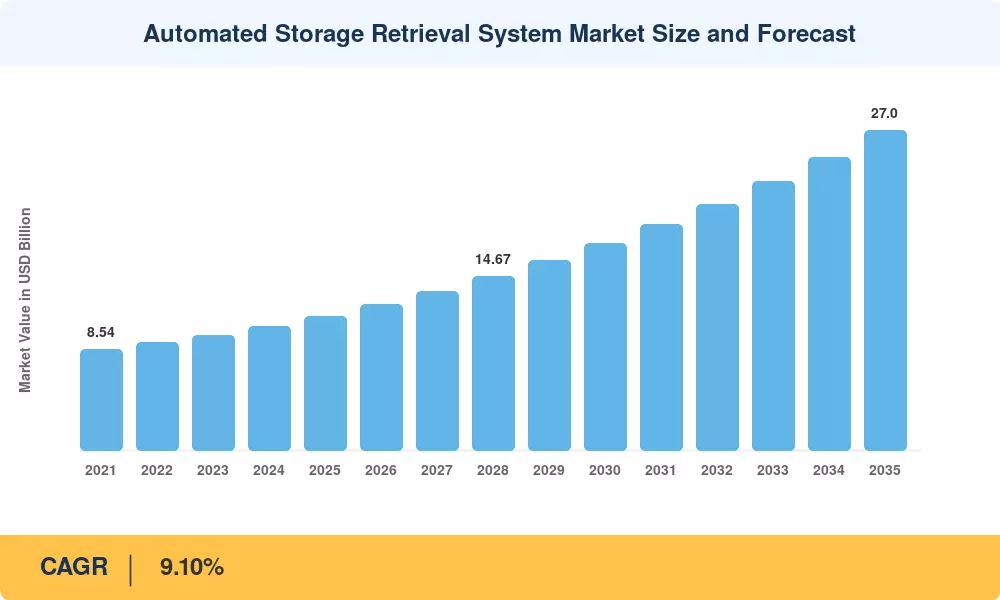
Automated Storage Retrieval System Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
E-commerce volume growth and omnichannel fulfillment +2.2% Global Long-term (≥4 yr)
Chronic warehouse labor shortages and wage inflation +1.8% North America, Europe Short-term (≤2 yr)
AI-driven routing and predictive maintenance integration +1.5% Global Medium-term (2–4 yr)
Real-estate cost escalation favoring vertical density +1.1% Asia-Pacific, Europe Medium-term (2–4 yr)
Government incentives for manufacturing automation +0.9% North America, Europe, Asia-Pacific Short-term (≤2 yr)
Cold-chain and pharmaceutical traceability mandates +0.7% North America, Europe Long-term (≥4 yr)


E-Commerce Volume Growth and Omnichannel Fulfillment

Global B2C e-commerce sales exceeded USD 6.3 trillion in 2024, and industry associations anticipate a further 10–12% compound growth until 2030 [8]. According to research, there is a need for about 1.2 million square feet of automated distribution capacity for every additional billion dollars in online gross merchandise value. The Automated Storage and Retrieval System Market is positioned as a crucial infrastructure layer for retailers switching from store-centric replenishment to distributed micro-fulfillment models thanks to this structural tailwind. Order-cycle windows are compressed to levels that manual warehouse operations just cannot maintain due to same-day and next-day delivery commitments.


Chronic Warehouse Labor Shortages

Over 490,000 vacant warehouse and transportation positions were reported by the U.S. Bureau of Labor Statistics in Q3 2024, while the logistics industry vacancy rate in Europe reached 4.7%, a five-year high [1]. In many high-wage regions, the payback calculation for capital-intensive Automated Storage and Retrieval System Market projects has changed from approximately seven years to less than four years due to annual wage inflation of 5-7% in logistics professions. Operators who put off automation risk labor-cost penalties that worsen their margins every quarter.


AI-Driven Routing and Predictive Maintenance

Modern Automated Storage and Retrieval System Market platforms now embed machine-learning algorithms that dynamically re-sequence pick orders based on real-time demand signals and equipment telemetry . Early adopters report unplanned downtime reductions of 25–30% and throughput gains exceeding 18% within the first twelve months of deployment. Predictive maintenance analytics, powered by vibration-sensor data and digital-twin modeling, extend crane and shuttle service intervals by an average of 22%, reducing total cost of ownership and strengthening the business case for system-level upgrades.

Real-Estate Cost Escalation

Industrial land prices in Tier-1 logistics corridors across Shanghai, Rotterdam, and Los Angeles have risen 35–50% since 2020 [18]. Vertical storage density offered by the Automated Storage and Retrieval System Market can compress the same inventory volume into 40–60% less floor space compared with conventional racking. This space-utilization advantage turns automation capex into a real-estate arbitrage opportunity, especially in urban micro-fulfillment sites where rental costs exceed USD 15 per square foot annually.


Restraints Impact Analysis

Restraint impact percentages are directional estimates and are not linearly deductible from gross growth; they reflect net dampening effects identified through expert scoring and sensitivity analysis.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High upfront capital expenditure and long ROI horizons −1.4% Global (especially SMEs) Short-term (≤2 yr)
Integration complexity with legacy warehouse infrastructure −0.9% North America, Europe Medium-term (2–4 yr)
Skilled-technician shortage for system commissioning −0.7% Global Long-term (≥4 yr)
Cybersecurity risks in connected warehouse networks −0.5% North America, Europe Medium-term (2–4 yr)
Supply-chain bottlenecks for key automation components −0.4% Global Short-term (≤2 yr)


High Upfront Capital Expenditure

Depending on the system type, throughput requirements, and integration scope, a full-scale Automated Storage and Retrieval System Market installation in a 500,000-square-foot distribution center may cost between $20 and $40 million [20]. The project funding and balance-sheet headroom required to absorb such expenditures are often unavailable to small and mid-size operators, which make up around 55% of the world's warehouse capacity. The adoption of robotics-as-a-service and equipment-as-a-service models is still below 8% of new deployments worldwide, despite their emergence as partial solutions.


Integration Complexity with Legacy Infrastructure

Compared to greenfield benchmarks, brownfield installations might have deployment times that are 30–50% longer due to siloed warehouse management software designs, uneven floor tolerances, and old racking incompatibilities [21]. The market for automated storage and retrieval systems is confronted with a paradox: the facilities that require automation the most are sometimes the most difficult to automate. Although middleware and API-layer solutions are getting better, original project budgets are still increased by 12–18% due to total integration costs.


Skilled-Technician Shortage

System commissioning, calibration, and ongoing maintenance demand specialized mechatronic and controls-engineering talent that remains in critically short supply [22]. Industry estimates suggest fewer than 35,000 certified automation technicians operate globally, against projected demand for 60,000 by 2030. This skills gap extends lead times, inflates service contracts, and constrains the pace at which new Automated Storage and Retrieval System Market installations can go live.


Automated Storage and Retrieval System Market Opportunities

Micro-Fulfillment Centers in Urban Retail

Dense urban environments offer a compelling runway for compact automated systems embedded inside or adjacent to retail stores. The Automated Storage and Retrieval System Market can address last-mile delivery economics by enabling sub-two-hour fulfillment windows from automated back-of-store or basement-level modules. Grocery chains in the U.S. and Europe have piloted over 120 micro-fulfillment sites since 2022, each generating 3–5× the pick rate of manual operations [17].

Cold-Chain Pharmaceutical and Life-Sciences Automation

Stricter GDP (Good Distribution Practice) and FDA 21 CFR Part 211 traceability mandates are pushing pharmaceutical distributors toward temperature-controlled automated retrieval systems that maintain audit-ready chain-of-custody records [19]. This vertical represents a premium-priced sub-segment of the Automated Storage and Retrieval System Market, with system ASPs 25–40% above ambient-temperature equivalents.

Emerging Market Expansion in Southeast Asia and the Middle East

Southeast Asian economies — particularly Vietnam, Indonesia, and Thailand — are experiencing annual warehouse construction growth exceeding 14%, driven by foreign direct investment in export manufacturing. The Automated Storage and Retrieval System Market stands to benefit as greenfield facilities in these regions increasingly specify automation from the outset rather than retrofitting later. Saudi Arabia's NEOM and logistics-zone initiatives present parallel opportunities in the Middle East.

Data Monetization and Digital-Twin Services

Operators running large Automated Storage and Retrieval System Market fleets generate terabytes of operational telemetry daily. Packaging this data into benchmarking-as-a-service and digital-twin simulation products creates a recurring-revenue stream for OEMs and integrators. Early movers have reported 8–12% margin uplift on service contracts that bundle analytics dashboards with hardware maintenance agreements .

Robotics-as-a-Service (RaaS) and Subscription Models

RaaS converts prohibitive capex into predictable monthly opex, lowering the entry barrier for SMEs that dominate third-party logistics. The Automated Storage and Retrieval System Market is beginning to mirror the trajectory of industrial robotics, where leasing and subscription penetration climbed from 4% to 15% between 2020 and 2025 [20].


Automated Storage and Retrieval System Market Future Outlook

Autonomous Warehouse Operations

By the early 2030s, fully lights-out warehouse operations will move from pilot to production scale. The Automated Storage and Retrieval System Market will converge with autonomous mobile robots, computer-vision picking systems, and AI-orchestrated task allocation to create self-optimizing distribution centers that require minimal human intervention [15]. The International Federation of Robotics projects global warehouse-robot density to triple between 2025 and 2032.

Platform Economics and Software-Defined Warehousing

Hardware commoditization will shift competitive differentiation toward software platforms that orchestrate multi-vendor automation fleets under a single control layer. The Automated Storage and Retrieval System Market will increasingly resemble an enterprise-software market, where recurring SaaS and analytics revenues comprise 20–30% of total contract value by 2030 . Interoperability standards such as VDA 5050 will accelerate this transition.

Sustainability-Linked Financing and ESG Mandates

The EU Corporate Sustainability Reporting Directive (CSRD) and SEC climate-disclosure rules will compel warehouse operators to quantify and reduce Scope 2 and Scope 3 emissions. Energy-efficient shuttle and cube-based systems that reduce per-pick electricity consumption by 35–50% compared with conventional forklift operations will attract sustainability-linked loan pricing advantages [16]. The Automated Storage and Retrieval System Market stands to benefit from green-bond and ESG-fund allocation as warehouse decarbonization gains priority.

Modular and Scalable System Architectures

Demand for phased deployment — where operators install a starter system and scale capacity in modular increments — will reshape how OEMs design and sell solutions. The Automated Storage and Retrieval System Market will see growing adoption of "automation-ready" building shells that pre-wire structural, electrical, and data infrastructure for future expansion [17]. This approach reduces initial capex risk and shortens time-to-value for operators uncertain about demand trajectories.


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 28.5% share (2025) Fulfillment-center expansion, cold-chain pharma
Europe 36.1% share (2025) Industrie 4.0, sustainability mandates
Asia-Pacific 12.60% CAGR (2026–2035) E-commerce infrastructure, greenfield builds
South America USD 0.66 Billion (2025) Food and beverage, nearshoring
Middle East & Africa USD 0.61 Billion (2025) Logistics-zone mega-projects, oil & gas diversification
Total USD 11.30 Billion (2025)

The Automated Storage and Retrieval System Market exhibits distinct regional growth profiles shaped by labor economics, real-estate dynamics, and regulatory environments.


North America

Country Key Metric Key Driver
US 74.2% of regional share Mega-DC expansion in Sunbelt corridor
Canada 10.28% CAGR Cold-chain grocery automation
Mexico USD 0.21 Billion (2025) Nearshoring-driven manufacturing logistics


Fulfillment-center square footage under construction in the United States exceeded 350 million square feet in 2024, with a disproportionate share specifying automated retrieval infrastructure from day one [5]. Canada's investment in cold-chain capacity is accelerating as large grocery retailers deploy automated tote and shuttle systems to cope with online grocery penetration that surpassed 12% nationally. Mexico's emerging role as a nearshoring destination for automotive and electronics manufacturers is generating first-time Automated Storage and Retrieval System Market demand along the Monterrey–Guadalajara industrial corridor.

Europe

Country Key Metric Key Driver
Germany 26.8% of regional share Automotive and Industrie 4.0 programs
UK 9.85% CAGR Post-Brexit labor-substitution automation
France USD 0.52 Billion (2025) Pharmaceutical distribution modernization
Italy 7.9% of regional share Food and beverage automation
Spain 8.72% CAGR Third-party logistics expansion
Nordic Countries USD 0.38 Billion (2025) Sustainability-driven warehouse design
Russia 4.1% of regional share Import-substitution manufacturing
Rest of Europe 10.4% of regional share Mixed industrial modernization


Germany anchors the European Automated Storage and Retrieval System Market, with Industrie 4.0 grants channeling over EUR 2 billion annually into factory and warehouse digitization [12]. The UK's post-Brexit labor constraints have compressed automation payback periods below three years for many logistics operators, spurring a wave of retrofit investments across the Midlands distribution belt. Southern European markets are growing from a smaller base but benefit from EU Recovery Fund allocations earmarked for supply-chain resilience.

Asia-Pacific

Country Key Metric Key Driver
China 38.5% of regional share E-commerce mega-warehouses
India 14.18% CAGR National Logistics Policy, organized retail growth
Japan USD 0.58 Billion (2025) Labor-scarcity automation in aging-workforce economy
South Korea 9.52% CAGR Semiconductor and electronics supply chains
ASEAN USD 0.31 Billion (2025) FDI-driven greenfield manufacturing
Rest of Asia-Pacific 5.7% of regional share Mixed industrial growth


China's Automated Storage and Retrieval System Market growth is anchored by the world's largest e-commerce ecosystem, where leading platforms operate distribution centers exceeding 1 million square feet each [11]. India's National Logistics Policy, targeting a reduction in logistics costs from 14% to 8% of GDP by 2030, is catalyzing first-generation automated storage investments across organized retail and pharmaceutical cold chains. Japan's acute demographic challenge — with warehouse-workforce availability declining at 2% annually — makes it a natural premium market for high-density automation solutions.

South America

Country Key Metric Key Driver
Brazil 62.3% of regional share Food and beverage, retail modernization
Argentina 8.15% CAGR Agricultural export logistics
Rest of South America USD 0.11 Billion (2025) Mining and industrial growth


Brazil dominates the South American Automated Storage and Retrieval System Market, where large food and beverage conglomerates are automating distribution centers to serve a consumer market of over 210 million people. Economic volatility and currency fluctuation remain headwinds, but multi-year leasing structures are mitigating capex risk for regional adopters.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 31.5% of regional share Vision 2030 logistics mega-projects
UAE 10.35% CAGR Free-zone distribution hub expansion
South Africa USD 0.08 Billion (2025) Retail and mining supply chains
Egypt 9.10% CAGR Industrial corridor development
Rest of MEA 18.2% of regional share Mixed infrastructure modernization


Saudi Arabia's Vision 2030 logistics initiatives — including the NEOM industrial city and the Riyadh integrated logistics zone — represent multi-billion-dollar catalysts for the Automated Storage and Retrieval System Market in the region. The UAE continues to function as a regional distribution hub, with free-zone operators investing heavily in automated storage to support re-export trade volumes.


Automated Storage Retrieval System Market By Region, 2025-2035

Automated Storage and Retrieval System Market Segmentation

By Product Type

Segment Key Metric Primary Demand Driver
Fixed-Aisle Crane Systems 34.8% share (2025) Heavy-pallet manufacturing and distribution
Shuttle-Based Systems 10.72% CAGR High-throughput e-commerce fulfillment
Vertical Lift Modules (VLM) USD 1.24 Billion (2025) Space-constrained facilities and parts management
Cube-Based and Robotic Storage 12.89% CAGR Dense SKU environments and omnichannel retail
Others (Carousel, Hybrid) USD 0.68 Billion (2025) Specialized kitting and pharmaceutical applications


Fixed-aisle crane systems remain the backbone of the Automated Storage and Retrieval System Market, particularly in automotive and heavy-industry settings where pallet loads exceed 1,000 kg. These systems offer unmatched vertical reach — some installations exceed 40 meters — and deliver deterministic cycle times critical for just-in-sequence manufacturing supply. However, their fixed-rail infrastructure limits reconfigurability, pushing greenfield operators toward shuttle-based or cube-based alternatives when SKU velocity and order complexity are high.

Cube-based and robotic storage platforms represent the fastest-expanding product category within the Automated Storage and Retrieval System Market. Their grid architecture enables storage densities four to five times greater than conventional selective racking, making them attractive for urban micro-fulfillment and space-constrained brownfield conversions. As these platforms mature, integration with pick-and-place robotics is extending their applicability beyond tote-level items into heavier payloads.

By Load Type

Segment Key Metric Primary Demand Driver
Unit Load 38.6% share (2025) Pallet-based manufacturing and wholesale distribution
Pallet Load Shuttle USD 1.52 Billion (2025) High-throughput cold-chain and beverage logistics
Mini Load 11.96% CAGR Small-parcel e-commerce order fulfillment
Mid Load 8.45% CAGR Mixed-case retail replenishment
Tote / Carton and Others USD 0.94 Billion (2025) Pharmaceutical and electronics component handling


Unit-load systems dominate the Automated Storage and Retrieval System Market by addressing the largest volume segment: full-pallet storage and retrieval in manufacturing, wholesale, and cold-chain environments. Mini-load tote systems are capturing the fastest growth trajectory as parcel sizes shrink and order frequency climbs in direct-to-consumer channels.

By Application

Segment Key Metric Primary Demand Driver
Storage and Buffering 42.1% share (2025) Core inventory management across all verticals
Goods-To-Person Order Picking 14.88% CAGR Labor-substitution in high-velocity fulfillment
Kitting and Sequencing USD 0.79 Billion (2025) Just-in-sequence automotive and electronics assembly
Others (Consolidation, Returns) 7.62% CAGR Reverse logistics and returns processing


Storage and buffering remain the foundational application for the Automated Storage and Retrieval System Market, serving as the inventory backbone for every sector from automotive to grocery. Goods-to-person order picking is rapidly closing the gap, driven by the economic imperative to reduce labor touches per order in high-velocity fulfillment environments where accuracy requirements exceed 99.9%.

By End-User Industry

Segment Key Metric Primary Demand Driver
Manufacturing — Automotive 24.6% share (2025) JIS/JIT production logistics
Manufacturing — General Industrial USD 1.87 Billion (2025) Heavy-parts storage and tool crib automation
E-Commerce and Retail 14.25% CAGR Omnichannel fulfillment infrastructure
Food and Beverage 9.18% CAGR Cold-chain compliance and perishable velocity
Pharmaceutical and Healthcare USD 0.92 Billion (2025) GDP compliance and serialization mandates
Others (3PL, Aerospace, etc.) 8.90% CAGR Third-party logistics expansion


Manufacturing-automotive remains the largest single end-user of the Automated Storage and Retrieval System Market, leveraging fixed-aisle cranes and shuttle systems for just-in-sequence parts delivery to assembly lines. E-commerce and retail are the fastest-growing end-user vertical, as online order volumes and same-day delivery expectations create irreversible demand for high-density automated fulfillment infrastructure.


Competitive Benchmarking

The Automated Storage and Retrieval System Market exhibits medium concentration, with the top five players accounting for an estimated 38–44% of global revenue. The Herfindahl-Hirschman Index sits in the moderate range (~800–1,100), reflecting a mix of large diversified conglomerates and specialized automation pure-plays. Competition intensifies around software capabilities and lifecycle-service contracts rather than hardware alone.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Daifuku Co., Ltd. ~9–12% Unit-load cranes, shuttle systems, airport logistics Global scale leader with automotive and airport verticals
Dematic (KION Group) ~7–10% Multishuttle, integrated supply-chain software Full-stack integrator with strong European base
SSI Schaefer ~6–9% Modular shuttle, VLM, and racking solutions Broad portfolio from manual racking to full automation
Swisslog (KUKA) ~5–8% AutoStore grid integration, pharmacy automation Robotics parentage with pharmaceutical specialization
Murata Machinery (Muratec) ~4–7% Stacker cranes, clean-room automation Semiconductor and electronics niche dominance
Kardex Group ~3–5% Vertical lift modules, automated storage towers Specialist in compact, space-saving retrieval
AutoStore ~4–6% Cube-based robotic grid storage Pure-play cube-storage innovator with rapid scaling
Mecalux ~3–5% Pallet shuttle, automated warehouses, Easy WMS Cost-competitive solutions with integrated WMS
Bastian Solutions (Toyota) ~2–4% Custom integration, goods-to-person systems Toyota-backed integrator with lean-logistics heritage
Honeywell Intelligrated ~3–5% Sortation, conveyor, and integrated ASRS Broad material-handling portfolio with IoT analytics
KNAPP AG ~2–4% OSR Shuttle, pharmacy and healthcare automation Healthcare and fashion logistics specialist


Recent News & Developments


  • Dematic (September 2024): Secured a EUR 85 million contract with a major European grocery retailer to deploy an integrated multishuttle and goods-to-person system across three distribution centers [8].
  • SSI Schaefer (June 2024): Announced a strategic partnership with a leading WMS software provider to deliver pre-integrated automation-and-software bundles, reducing commissioning timelines by 25% [21].
  • Swisslog (February 2024): Expanded its AutoStore integration portfolio with a new cold-chain variant capable of operating at −25°C for frozen-food distribution [19].
  • KNAPP AG (October 2023): Unveiled the Open Shuttle Fork, an autonomous mobile robot designed to seamlessly interface with fixed-aisle crane systems in hybrid warehouse environments [15].
  • Mecalux (July 2023): Commissioned a fully automated 140,000-pallet-position clad-rack warehouse in Poland for a multinational FMCG company, one of the largest single-site installations in Central Europe [12].


Automated Storage and Retrieval System Market Report Scope

Parameter Detail
Market Scope Global Automated Storage and Retrieval System Market covering product type, load type, application, end-user industry, and geography
Study Period 2021–2035
CAGR (2026–2035) 9.10%
Market Size — 2025 (Base Year) USD 11.30 Billion
Market Size — 2035 (Forecast Endpoint) USD 27.00 Billion
Fastest Growing Segment E-Commerce and Retail (14.25% CAGR by end-user); Goods-To-Person Order Picking (14.88% CAGR by application)
Companies Profiled 11 (Daifuku, Dematic, SSI Schaefer, Swisslog, Murata Machinery, Kardex, AutoStore, Mecalux, Bastian Solutions, Honeywell Intelligrated, KNAPP)
Valuation Currency USD Billion

FAQs

What is the typical payback period for a mid-size automated storage and retrieval system installation?
Most mid-size deployments (200,000–500,000 sq ft) achieve payback within 3–5 years depending on labor-cost geography and shift structure [13]. Facilities running three shifts in high-wage regions often recoup investment in under three years.
How do cube-based robotic systems differ from fixed-aisle cranes in operational flexibility?
Cube-based grids allow dynamic bin reallocation without physical reconfiguration, while fixed-aisle cranes operate on rail-mounted paths with rigid lane assignments [14]. Cube systems suit high-SKU-count environments; cranes excel with heavy uniform pallets.
What cybersecurity measures should warehouse operators prioritize when deploying connected Automated Storage and Retrieval System Market infrastructure?
Operators should implement network segmentation between OT and IT domains, enforce encrypted communication protocols, and conduct quarterly penetration testing [23]. Zero-trust architecture is emerging as the preferred framework for new deployments.
How are sustainability mandates influencing Automated Storage and Retrieval System Market purchasing decisions?
EU CSRD reporting requirements and SEC climate-disclosure rules now factor into RFP scoring criteria for warehouse automation [16]. Energy-efficient shuttle systems consuming 35–50% less electricity per pick receive favorable sustainability-linked loan terms.
What role do system integrators play versus OEM direct sales in the Automated Storage and Retrieval System Market?
Independent integrators handle approximately 40% of global deployments, offering multi-vendor orchestration that OEM-direct channels cannot match [22]. They add value through site-specific engineering and cross-platform software integration.
How is the adoption of digital twins reshaping maintenance strategies for automated storage systems?
Digital twins enable predictive maintenance by simulating wear patterns and forecasting component failures weeks in advance [3]. Operators using twin-based maintenance report 20–25% reductions in unplanned downtime and extended equipment lifecycles.
What financing structures are available for operators that cannot fund full Automated Storage and Retrieval System Market capex upfront?
Robotics-as-a-service, operating leases, and gain-sharing contracts let operators convert capex into monthly opex [20]. Gain-sharing ties vendor payments to throughput improvements, aligning incentives between buyer and supplier.    
Author
Author Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Co-Author Co-Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed engineering journals, automation industry publications, and authoritative industrial organizations. Key sources included the Occupational Safety and Health Administration (OSHA), International Organization for Standardization (ISO) - specifically ISO 3691-1 for industrial trucks and ISO 13849 for safety controls, European Committee for Standardization (CEN) - EN 528 for rail-dependent storage and retrieval equipment, Material Handling Industry (MHI), Robotic Industries Association (RIA), Association for Advancing Automation (A3), International Federation of Robotics (IFR), EU Eurostat Industrial Production Database, US Census Bureau - Manufacturing and Trade Inventories and Sales, Bureau of Labor Statistics (BLS) - Manufacturing and Warehouse Employment Data, World Economic Forum (WEF) - Future of Jobs Report, National Institute of Standards and Technology (NIST) - Smart Manufacturing Standards, European Logistics Association (ELA), Japan Industrial Robot Association (JIRA), VDMA (German Engineering Federation) - Material Handling and Intralogistics Division, Intermodal Association of North America (IANA), American Society of Mechanical Engineers (ASME), and national statistics bureaus from key manufacturing economies including China's National Bureau of Statistics (NBS), Japan's Ministry of Economy, Trade and Industry (METI), and Germany's Federal Statistical Office (Destatis). These sources were used to collect equipment installation statistics, safety compliance data, automation adoption rates, labor cost trends, warehouse capacity utilization metrics, and market landscape analysis for unit load AS/RS, mini-load AS/RS, vertical lift modules (VLM), carousel-based systems, shuttle systems, and autonomous mobile robot (AMR) technologies.


Primary Research

To gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research phase. Regulatory compliance officers, heads of product development, vice presidents of engineering, and commercial directors from AS/RS manufacturers, system integrators, and component suppliers were examples of supply-side sources. Supply chain directors, warehouse operations managers, logistics automation leads, procurement heads from e-commerce fulfillment centers, automakers, food and beverage distribution centers, pharmaceutical warehousing facilities, and third-party logistics (3PL) providers were examples of demand-side sources. In addition to confirming product development timelines and gathering information on technology integration challenges, total cost of ownership models, and return on investment (ROI) dynamics, primary research validated market segmentation across type (load-based, shuttle/bot-based, carousel, VLM), industry vertical (automotive, metals/machinery, food/beverage, chemicals, healthcare, semiconductor/electronics, retail/e-commerce, aviation), and regional adoption patterns.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (34%), Others (38%)

By Region: North America (32%), Europe (29%), Asia-Pacific (34%), Rest of World (5%)


Market Size Estimation

Global market valuation was derived through revenue mapping and system installation volume analysis. The methodology included:

Identification of 55+ key manufacturers and system integrators across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Product mapping across unit load AS/RS, mini-load AS/RS, vertical lift modules (VLM), horizontal and vertical carousels, shuttle-based systems, and autonomous mobile robots

Analysis of reported and modeled annual revenues specific to AS/RS hardware, software (warehouse management systems, warehouse control systems), and service/maintenance portfolios

Coverage of manufacturers representing 72-78% of global market share in 2024

Extrapolation using bottom-up (system installations × ASP by configuration and country) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations

Integration of end-user procurement data from Fortune 500 companies across automotive, retail/e-commerce, and pharmaceutical verticals

Cross-validation against material handling equipment association shipment reports and regional automation spending surveys

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















