Automated Plate Readers Market (2026 – 2035)

Automated Plate Readers Market Size, Share and Research Report By Technology (Fixed Automated Plate Readers, Mobile Automated Plate Readers, Portable Automated Plate Readers), By End User (Healthcare Institutions, Research Laboratories, Pharmaceutical Companies, Educational Institutions), By Application (Drug Discovery, Clinical Diagnostics, Genomic Research), By Detection Method (Fluorescence Detection, Luminescence Detection, Absorbance Detection) andBy Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa)- Industry Forecast Till 2035
ID: MRFR/SEM/41127-HCR 200 Pages Aarti Dhapte, Aarti Dhapte Last Updated: September 22, 2026
Automated Plate Readers Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)11.6%
2025 Market SizeUSD 0.92 Billion
2035 Market SizeUSD 2.76 Billion
Key Players
Thermo Fisher Scientific
Danaher Corporation
Agilent Technologies
Revvity
Tecan Group
BMG LABTECH
Opportunities
  • Emerging-Market Laboratory Build-Out
  • Data Monetisation and Instrument-as-a-Service
  • Cell and Gene Therapy Quality Control

Automated Plate Readers Market Summary

The Automated Plate Readers Market reached USD 0.92 billion in 2025 and begins the forecast window at USD 1.03 billion in 2026, advancing to USD 2.76 billion by 2035 at an 11.6% CAGR. Two funding catalysts anchor that trajectory. The U.S. National Institutes of Health obligated roughly USD 47.1 billion in extramural research support in fiscal 2024, a meaningful share of which flows into assay instrumentation and core-facility refresh cycles [1]. In parallel, the European Commission's Horizon Europe health cluster committed close to EUR 8.2 billion across its 2021–2027 envelope, sustaining procurement of detection platforms across academic and translational laboratories [2].

Detection hardware is changing shape. Standalone absorbance-only instruments tethered to a single workstation are giving way to incubated, gas-controlled multimode systems that sit inside robotic workcells and stream results directly into electronic laboratory notebooks. Pharmaceutical R&D spending of approximately USD 276 billion in 2024 underwrites that replacement cycle, with high-throughput screening groups prioritising kinetic and label-free capability over raw read speed [3].

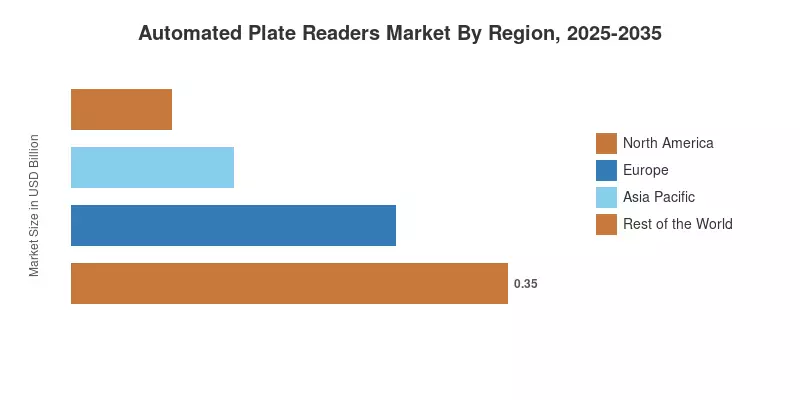
North America holds 38.5% of 2025 revenue on the strength of its biopharma and contract research base. Asia Pacific expands fastest at a 14.2% CAGR as Chinese and Indian discovery capacity scales, while Europe retains roughly 28.0% on regulated diagnostics demand. Through 2035, the Automated Plate Readers Market will be shaped less by detection physics than by how cleanly instruments integrate into automated, data-governed laboratory workflows.

Key Report Takeaways

The Automated Plate Readers Market is summarised below across its two canonical segmentation dimensions and its regional structure.

• By Product Type

  • Multimode Microplate Readers command 59.0% of 2025 revenue, reflecting buyer preference for consolidated absorbance, fluorescence and luminescence detection on one deck
  • Dedicated Microplate Readers (Single-mode Readers) post the faster 12.4% CAGR as low-cost satellite units multiply inside automated workcells

• By Application

  • Drug Discovery accounts for 36.5% of 2025 revenue, the largest single application pool in the Automated Plate Readers Market
  • Clinical Diagnostics grows fastest at a 13.6% CAGR on immunoassay volume expansion and decentralised testing networks
  • Genomics and Proteomics Research contributed USD 0.22 billion in 2025

• By Region

  • North America leads with 38.5% share, supported by federal research funding and a dense contract research organisation base
  • Asia Pacific is the growth engine at a 14.2% CAGR through 2035
  • Europe generated USD 0.26 billion in 2025

Market Size and Forecast (2021–2035)

Historical values were reconstructed from instrument vendor segment disclosures, customs and trade data for laboratory optical instruments, and installed-base surveys of pharmaceutical, academic and hospital laboratories. Forecast values apply a bottom-up build of unit shipments, average selling prices by detection class, and service and consumable attach rates, then reconcile against top-down research-expenditure indicators. Currency is constant 2025 U.S. dollars.
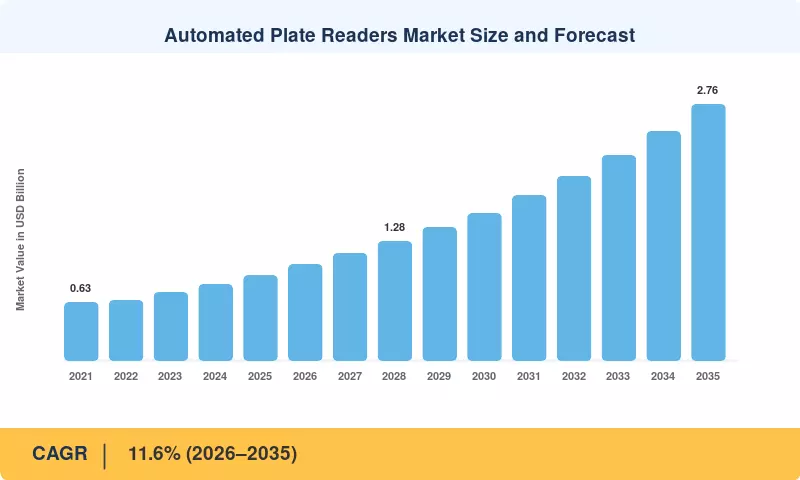
Automated Plate Readers Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Biopharmaceutical R&D expenditure expansion +2.4 Global Medium-term (2–4 yr)
High-throughput screening automation +1.9 North America, Europe Medium-term (2–4 yr)
Clinical diagnostics volume growth +1.7 Asia Pacific, Europe Long-term (≥4 yr)
Public research funding programmes +1.3 North America, Europe, Asia Pacific Short-term (≤2 yr)
Migration to multimode detection +1.2 Global Medium-term (2–4 yr)
Contract research capacity build-out +1.1 Asia Pacific Long-term (≥4 yr)
Software and data-analytics attach +0.9 Global Long-term (≥4 yr)


Biopharmaceutical R&D Expenditure Expansion

The single largest demand pool for detection instruments is still the approximately USD 276 billion spent on pharmaceutical research worldwide in 2024 [3]. Because binding kinetics, potency, and cytotoxicity all require different read modes, large-molecule and cell-therapy pipelines employ a disproportionately larger amount of plate-based assay capacity than small-molecule programs. A mid-size discovery site commissions six to twelve incubated multimode units, with sponsors replacing a ten-year-old absorbance fleet typically budgeting between USD 45,000 and USD 90,000 per unit.


High-Throughput Screening Automation

Instruments are being combined into scheduler-driven workcells by screening groups. Laboratories using integrated systems process two to three times as many plates per full-time equivalent as manual benches, according to industry automation studies [5]. The 20–30% price premium for readers with robot-compatible stackers, barcode tracking, and open scheduling drivers is justified by this productivity differential. The majority of competitive tenders above USD 250,000 now include automation-ready specs.


Clinical Diagnostics Volume Growth

Hospital and reference laboratories are the fastest-expanding buyer group. The World Health Organization estimates that laboratory results inform a majority of clinical decisions, yet diagnostic capacity remains thin across lower-middle-income settings [6]. ELISA-based infectious disease, allergy and autoimmune panels run almost entirely on microplate formats, and each new accredited laboratory adds one to three readers at commissioning, plus a validated backup unit.

Public Research Funding Programmes

Federal and supranational grants convert directly into instrument orders. NIH extramural obligations of approximately USD 47.1 billion in fiscal 2024 fund core facilities that refresh detection hardware on five-to-seven-year cycles [1]. Horizon Europe's health cluster adds close to EUR 8.2 billion through 2027 [2]. Shared-instrumentation grant mechanisms specifically underwrite capital items above USD 50,000, a bracket that captures most incubated multimode platforms.

Migration to Multimode Detection

Buyers increasingly refuse to purchase single-purpose optics. Vendor product roadmaps show filter-and-monochromator hybrid designs displacing fixed-filter units across mid-range price bands. Consolidating four detection modes into one chassis cuts bench footprint by roughly 40% and removes duplicate service contracts. The trade-off is sensitivity: dedicated luminometers still outperform hybrids by a measurable margin on low-signal reporter assays, which sustains a residual single-mode installed base.

Contract Research Capacity Build-Out

Asia Pacific contract research and manufacturing organisations continue to add discovery-services capacity, with regional CRO revenue growing at a double-digit pace through 2024 [8]. New sites in Hyderabad, Suzhou and Singapore specify Western-branded readers to satisfy sponsor audit requirements, which raises average selling prices above the regional norm. Each greenfield discovery-services building typically commissions eight to twenty plate-reading channels within its first eighteen months.

Software and Data-Analytics Attach

Instrument value is migrating into software. Vendors now license curve-fitting, 21 CFR Part 11 audit trails, and cloud data management as recurring modules, and laboratory informatics adoption has climbed steadily across regulated sites. Annual software and service attach can add 12–18% to lifetime instrument revenue. Open interface standards such as SiLA 2 make that attach defensible, because they let a reader join a scheduler without proprietary middleware.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High capital cost of multimode systems −1.6 Global Medium-term (2–4 yr)
Instrument interoperability fragmentation −1.2 Global Long-term (≥4 yr)
Long replacement cycles and refurbished supply −0.9 North America, Europe Medium-term (2–4 yr)
Component and supply chain constraints −0.7 Global Short-term (≤2 yr)
Clinical validation and regulatory burden −0.6 Europe Long-term (≥4 yr)


High Capital Cost of Multimode Systems

A single-mode absorbance device costs between USD 8,000 and USD 25,000, while fully specified incubated multimode readers range from USD 60,000 to USD 120,000. It is common for academic departments with flat grant allocations to purchase shared access through a core facility or postpone the upgrading. This deferral limits penetration in price-sensitive niches and lengthens decision cycles from months to many funding rounds.


Instrument Interoperability Fragmentation

Vendor-specific drivers are still required to connect readings to scheduling software. Implementations of laboratory informatics frequently go over schedule, with integration effort accounting for a greater portion of project expenses than software licensing. Middleware maintenance becomes an ongoing expense when a website operates three reader brands. In response, suppliers are consolidated by buyers, slowing additional unit sales throughout the installed base.


Long Replacement Cycles and Refurbished Supply

Well-maintained plate readers remain serviceable for a decade or more, and a liquid secondary market keeps certified refurbished units circulating at 40–60% of new-instrument pricing [13]. Academic and start-up buyers increasingly source there. Every refurbished placement removes a new-unit sale while still generating service revenue, compressing hardware growth without materially reducing total installed capacity.

Component and Supply Chain Constraints

Photomultiplier tubes, monochromator gratings and precision motion components have limited qualified supplier bases. Semiconductor and optical component lead times, although improved from their 2022 peaks, remain above pre-2020 norms for specialised detection parts [14]. Extended lead times push delivery beyond fiscal-year grant deadlines, which occasionally forces buyers to reallocate capital rather than carry the order.

Clinical Validation and Regulatory Burden

Instruments entering accredited diagnostic workflows require documented installation, operational, and performance qualification. Under the European In Vitro Diagnostic Regulation, laboratories must evidence that reading conditions match the assay manufacturer's validated parameters, and transitional deadlines have been repeatedly extended to accommodate capacity shortfalls [9]. Validation labour commonly adds USD 6,000–15,000 per instrument, deterring incremental purchases in hospital settings.

Automated Plate Readers Market Opportunities

Emerging-Market Laboratory Build-Out

India, Indonesia, Vietnam and Brazil are commissioning diagnostic and research laboratories faster than they are training instrument service engineers. That gap creates an opening for vendors offering ruggedised mid-range readers bundled with remote diagnostics and local spare-parts depots. India's Department of Biotechnology and comparable national programmes have prioritised research infrastructure spending, and procurement increasingly favours suppliers with in-country service coverage over headline specifications [10]. Pricing between USD 18,000 and USD 35,000 addresses the largest unmet band.

Data Monetisation and Instrument-as-a-Service

Recurring revenue models remain underexploited. Subscription bundles combining hardware access, consumables, cloud analytics and guaranteed uptime convert a lumpy capital decision into an operating line item, which suits CROs managing variable project loads. Vendors piloting these structures report materially higher retention than transactional accounts. Anonymised, aggregated assay-performance data also supports benchmarking services that laboratories will pay for separately.

Cell and Gene Therapy Quality Control

Release testing for advanced therapies demands potency, sterility-adjacent and viability assays under tightly controlled temperature and gas conditions. Regulatory approvals for cell and gene therapies have accelerated since 2023, and each commercial product carries a validated QC assay panel [11]. Readers with integrated CO₂ and O₂ control, low-volume optics and full audit trails address a segment where willingness to pay is set by batch value rather than by capital budget.

Label-Free and High-Content Detection Modules

Upgrade paths matter more than replacement. Modular architectures that let a laboratory add time-resolved FRET, AlphaScreen or brightfield imaging to an existing chassis capture incremental spend without a new capital approval. Module attach also lengthens platform life, strengthening the service annuity. Vendors that publish transparent module pricing shorten the sales cycle considerably against competitors requiring a full quotation process.

AI-Assisted Assay Optimisation

Machine-learning models trained on historical plate data can flag edge effects, predict Z-factor degradation and recommend gain settings before a screening campaign runs. Laboratories adopting analytics-led quality control report meaningful reductions in repeated plates. Embedding these functions in instrument software creates a differentiated attach point and raises switching costs, which directly benefits incumbent share within the Automated Plate Readers Market.

Automated Plate Readers Market Future Outlook

Autonomous Laboratory Operations

Self-driving laboratories move from demonstration to production during this window. Closed-loop systems that design, execute, and interpret assay cycles without human intervention require readers that expose full instrument state through an API, not just a results file. Several national research agencies have funded autonomous experimentation testbeds since 2023, and the architectural pattern is spreading into industrial discovery [5]. Vendors that treat the reader as a networked node rather than a terminal device will capture a disproportionate share of these builds.

Platform Economics and Consumable Attach

Hardware margins compress as detection specifications converge. Value shifts toward microplates, reagent kits, validated assay protocols and software subscriptions, where gross margins run substantially above instrument sales. Analyst coverage of laboratory instrumentation consistently identifies recurring revenue as the primary determinant of valuation multiples in this category [20]. Expect more co-development agreements between reader manufacturers and assay kit suppliers, structured to lock protocol compatibility at the point of validation.

Decentralised and Near-Patient Diagnostics

Testing continues migrating out of centralised reference laboratories. Compact readers that meet full regulatory documentation standards while fitting a clinic bench address a buyer that did not exist a decade ago. WHO diagnostic capacity assessments continue to identify substantial unmet testing demand outside tertiary hospitals, particularly across lower-middle-income health systems [6]. Instruments combining small footprint, connectivity and audit-ready data handling will define the competitive frontier in this application.

Sustainability and Laboratory Energy Reporting

Laboratories consume several times the energy per square metre of standard office space, and institutional carbon commitments are pushing procurement teams to score instruments on power draw and standby behaviour [21]. Certification frameworks assessing laboratory sustainability practices have expanded across university and pharmaceutical estates. Manufacturers responding with LED excitation sources, low-standby electronics and take-back programmes gain measurable tender advantage, particularly in Europe where these criteria are formally weighted.

Regional Market Share Analysis

Region Metric (2025 / 2026–2035) Primary Investment Themes
North America 38.5% share Federal grant-funded core facilities; CRO automation; cell therapy QC
Europe USD 0.26 Billion IVDR-compliant diagnostics; Horizon Europe infrastructure; sustainability retrofits
Asia Pacific 14.2% CAGR Discovery-services capacity; domestic biotech scale-up; hospital laboratory expansion
Rest of the World 9.0% share Public health laboratory networks; national diagnostic programmes
Total USD 0.92 Billion (100%) —

Regional performance in the Automated Plate Readers Market tracks the geography of pharmaceutical research, accredited diagnostic capacity, and public science funding rather than general economic size.


North America

Country Metric Key Driver
US 78.0% of region NIH-funded core facility refresh and biopharma screening capacity [1]
Canada USD 0.045 Billion CIHR and provincial genomics programme investment [15]
Mexico 11.5% CAGR Clinical laboratory network modernisation [6]


North America's lead rests on concentration rather than breadth. Roughly a third of global pharmaceutical R&D is executed within a few U.S. clusters, and shared-instrumentation grant mechanisms specifically fund capital items above USD 50,000 [1]. Canadian demand is steadier and more academic in character, anchored by federally supported genomics platforms [15]. Mexico's growth comes from a different source entirely: accreditation of private diagnostic chains under national quality frameworks, which requires validated readers at every commissioned site.

Europe

Country Metric Key Driver
Germany 24.0% of region Pharmaceutical and Fraunhofer institute instrumentation demand [2]
UK USD 0.046 Billion Catapult network and biotech cluster procurement [16]
France 10.9% CAGR France 2030 health innovation funding [2]
Italy 8.5% of region Hospital diagnostic laboratory consolidation [9]
Spain 6.5% of region Regional public health laboratory upgrades [9]
Nordic Countries USD 0.019 Billion Academic core facility renewal [2]
Russia 3.0% of region Domestic pharmaceutical substitution programmes [17]
Rest of Europe 11.5% of region Central European CRO expansion [8]


Regulation shapes European demand more than funding does. The In Vitro Diagnostic Regulation pushed diagnostic laboratories to document instrument qualification in detail, and repeated transitional extensions have spread that compliance spending across several budget years [9]. Germany's industrial pharmaceutical base sustains the largest single national pool, while the UK's concentration of small biotechnology firms favours mid-range multimode purchases over flagship systems [16]. Sustainability certification is emerging as a tender criterion, with energy consumption and packaging now scored in several national framework agreements.

Asia Pacific

Country Metric Key Driver
China 34.0% of region Domestic biotech and CRO discovery capacity [8]
India 15.9% CAGR Biotechnology infrastructure programmes and diagnostic chains [10]
Japan USD 0.048 Billion Established pharmaceutical R&D base [17]
South Korea 9.0% of region Biosimilar and cell therapy manufacturing QC [11]
ASEAN 13.8% CAGR Public health laboratory network investment [6]
Rest of Asia-Pacific 7.5% of region Academic research funding growth [18]


Growth here is additive rather than replacement-driven. China's discovery-services sector continues to commission new laboratory floor space, and sponsor audit requirements keep specifications aligned with Western brands even where domestic alternatives exist [8]. India combines research infrastructure funding with rapid private diagnostic chain expansion, producing the region's highest country-level growth rate [10]. Japan behaves like a mature market, with steady service-led revenue and long replacement intervals. South Korean demand increasingly originates from biologics quality control rather than discovery.

Rest of the World

Country Metric Key Driver
Brazil 22.0% of region ANVISA-regulated diagnostic laboratory accreditation [6]
Argentina USD 0.006 Billion Public university research procurement [18]
Saudi Arabia 13.1% CAGR Vision 2030 health sector localisation [19]
UAE 9.5% of region Reference laboratory and precision medicine investment [19]
South Africa USD 0.007 Billion Infectious disease surveillance capacity [6]
Egypt 12.4% CAGR National screening programme expansion [6]
Rest of South America 8.0% of region Regional diagnostic network upgrades [18]
Rest of Middle East & Africa 14.0% of region Donor-funded public health laboratories [6]


Public health procurement dominates this composite region. Gulf states are funding reference laboratories and precision medicine centres under national transformation programmes, and those tenders favour turnkey packages that bundle instruments, validation and multi-year service [19]. African demand remains heavily donor-influenced, with infectious disease surveillance networks specifying robust absorbance and fluorescence units rather than premium platforms [6]. Brazilian growth follows accreditation rather than research spending, as private laboratory groups standardise equipment across acquired sites.

Automated Plate Readers Market By Region, 2025-2035

Automated Plate Readers Market Segmentation

By Product Type

The Automated Plate Readers Market divides along detection architecture, with buyers weighing consolidation against per-mode sensitivity.

Segment Metric (2025 / 2026–2035) Primary Demand Driver
Dedicated Microplate Readers (Single-mode Readers) 12.4% CAGR Low-cost satellite units in automated workcells
Multimode Microplate Readers 59.0% share Detection consolidation and bench footprint reduction


Multimode Microplate Readers lead on revenue because a single chassis covering absorbance, fluorescence and luminescence eliminates duplicate service contracts and frees roughly 40% of bench space. Dedicated Microplate Readers (Single-mode Readers) nonetheless grow faster in unit and value terms, driven by workcell designs that deploy several inexpensive absorbance-only units in parallel rather than queuing plates through one premium instrument. Dedicated luminometers also retain a sensitivity advantage on low-signal reporter assays that hybrids have not closed.

By Application

Application mix within the Automated Plate Readers Market reflects where assay volume, not headcount, is concentrated.

Segment Metric (2025 / 2026–2035) Primary Demand Driver
Drug Discovery 36.5% share High-throughput screening and lead optimisation volume
Genomics and Proteomics Research USD 0.22 Billion Nucleic acid quantification and protein assay workflows
Clinical Diagnostics 13.6% CAGR ELISA-based panel volume and laboratory accreditation
Other Applications 10.0% share Food safety, environmental and agricultural testing


Drug Discovery remains the revenue anchor, absorbing the highest-specification instruments because screening campaigns amortise capital cost across millions of wells. Clinical Diagnostics expands fastest as accredited laboratories multiply and immunoassay panels shift toward automated reading. Genomics and Proteomics Research sustains steady mid-range demand for quantification workflows, while Other Applications — food safety, environmental and agricultural testing — contributes a small but durable base that is largely insulated from pharmaceutical funding cycles.

Competitive Benchmarking

Concentration in the Automated Plate Readers Market is moderate to low. The top five suppliers hold an estimated 50–58% of global revenue, and a Herfindahl-Hirschman Index in the 850–1,000 range places the category below conventional concentration thresholds. Three structural features sustain that fragmentation: specialist manufacturers compete effectively on detection sensitivity against diversified conglomerates, the installed base turns over slowly, and open plate formats limit technical lock-in. Competition therefore centres on service network depth, software capability and assay-kit partnerships rather than on optics alone.

Company Est. Revenue Share Range Key Offerings for Automated Plate Readers Market Strategic Positioning
Thermo Fisher Scientific ~13–16% Multimode and absorbance readers, integrated assay kits Scale leader; bundles instruments with reagents and informatics
Danaher Corporation (Molecular Devices) ~11–14% Multimode platforms, imaging cytometry, automation integration Premium discovery segment; strong workcell integration
Agilent Technologies (BioTek) ~9–12% Multimode readers with imaging, incubated systems Combines detection and imaging; broad mid-market coverage
Revvity ~8–11% High-sensitivity multimode systems, proprietary assay chemistries Differentiated through chemistry-instrument pairing
Tecan Group ~6–9% Multimode readers, liquid handling and workcell integration Automation-first positioning; OEM partnership depth
BMG LABTECH ~5–7% Dedicated and multimode readers, ultra-fast detection Specialist focus; sensitivity and speed leadership
Berthold Technologies ~3–5% Luminescence and multimode detection systems Niche strength in low-light detection applications
Bio-Rad Laboratories ~3–5% Absorbance readers, ELISA workflow systems Clinical and immunoassay workflow orientation
Merck KGaA ~2–4% Reader platforms bundled with life science reagents Reagent-led channel access
Hamamatsu Photonics ~2–3% Detection modules, plate reading subsystems Component and OEM supply position
Promega Corporation ~1–3% Luminescence-optimised readers and assay systems Assay-anchored instrument placement


Recent News & Developments

Recent activity in the Automated Plate Readers Market has concentrated on software capability, automation compatibility and regulatory timelines.

  • Revvity (May 2023): Completed its corporate rebrand from PerkinElmer's life sciences and diagnostics business, sharpening portfolio focus on detection instrumentation and assay chemistry [17].
  • European Commission (July 2024): Extended In Vitro Diagnostic Regulation transitional provisions, giving diagnostic laboratories additional time to complete instrument and assay qualification and spreading validation spend across budget cycles [9].
  • Agilent Technologies (March 2024): Expanded its multimode reader line with enhanced imaging and incubation capability, targeting live-cell kinetic workflows in discovery laboratories.
  • Tecan Group (September 2024): Announced deeper scheduler integration between its detection platforms and third-party robotic handlers, addressing the interoperability barrier cited by automation buyers [5].
  • BMG LABTECH (June 2024): Released enhanced detection modules for existing multimode chassis, reinforcing the upgrade-rather-than-replace commercial model.
  • Molecular Devices (February 2025): Introduced expanded cloud-based data management and audit-trail functionality aimed at regulated clinical and QC environments.
  • U.S. National Institutes of Health (October 2024): Continued shared-instrumentation grant awards for capital items above USD 50,000, sustaining core-facility detection hardware refresh [1].
  • Thermo Fisher Scientific (April 2025): Extended assay kit and reader co-validation programmes, tightening the link between consumable pull-through and instrument placement [20].

Automated Plate Readers Market Report Scope

Parameter Detail
Market Scope Global Automated Plate Readers Market, covering dedicated single-mode and multimode microplate reading instruments, associated software and service revenue
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 11.6% (2026–2035)
Market Size Checkpoints USD 0.92 Billion (2025); USD 1.03 Billion (2026); USD 1.59 Billion (2030); USD 2.76 Billion (2035)
Fastest Growing Segments Dedicated Microplate Readers (Single-mode Readers) by product type; Clinical Diagnostics by application; Asia Pacific by geography
Companies Profiled Thermo Fisher Scientific, Danaher Corporation (Molecular Devices), Agilent Technologies (BioTek), Revvity, Tecan Group, BMG LABTECH, Berthold Technologies, Bio-Rad Laboratories, Merck KGaA, Hamamatsu Photonics, Promega Corporation
Valuation Currency Constant 2025 U.S. dollars (USD)

FAQs

How should procurement teams evaluate total cost of ownership in the Automated Plate Readers Market?
Service contracts, light-source replacement, and validation labour typically add 18–24% to list price across a seven-year instrument life. Request documented uptime guarantees and qualification support in writing before signing [17].
What integration challenges arise when connecting readers to laboratory automation systems?
Driver compatibility with scheduling software remains the main obstacle. Confirm that the vendor publishes an open API, supports SiLA 2, and has validated plate-handling robots from at least two independent suppliers .
Which detection mode should buyers prioritise in the Automated Plate Readers Market?
Fluorescence intensity covers most screening requirements at moderate cost. Time-resolved FRET and luminescence justify their premium only for high-value binding or reporter assays, so match the mode to assay volume rather than to specification breadth .
How do in vitro diagnostic regulations affect clinical deployment of these instruments?
Instruments used in accredited diagnostic workflows require documented performance validation and traceable calibration records. Under the European framework, laboratories must retain evidence that reading conditions meet the assay manufacturer's stated parameters [9].
Which emerging use cases are expanding demand beyond traditional screening?
Cell and gene therapy release testing, organoid viability panels, and environmental toxicity assays are the fastest-growing non-traditional workloads. Each requires kinetic reading under controlled temperature and gas, pushing buyers toward incubated multimode platforms [11].
How costly is supplier switching in the Automated Plate Readers Market?
Switching costs are moderate: assay protocols and data formats are vendor-specific, but standardised plate geometry limits hard lock-in. Most laboratories consolidate on one platform per site while retaining a second supplier for specialised detection .
What should investors monitor over the next three years?
Consumable and service attach rates, not instrument unit volumes, determine margin durability in this category. Reagent-kit partnerships and software subscription uptake are the clearest leading indicators of vendor pricing power [20].
Author
Author Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Co-Author Co-Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.



















