Automated Barriers Bollards Market (2026 - 2035)

Automated Barriers and Bollards Market Research Report Information By Product Type (Barriers and Bollards), By Control Mechanism (Push Button, Remote Controlled, RFID/Smart-Card, Loop Detectors, and Others (Biometric and Mobile-App Control)), By End-User Sector (Residential Buildings, Commercial Buildings, and Others (Tourism Districts, Education, Healthcare, and Government)), And By Region (North America, Europe, Asia-Pacific, and Rest of the World) – Market Forecast Till 2035.
ID: MRFR/PCM/39730-HCR 111 Pages Snehal Singh Last Updated: November 06, 2026
Automated Barriers Bollards Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.05%
2025 Market SizeUSD 21.20 Billion
2035 Market SizeUSD 31.53 Billion
Key Players
FAAC Group
CAME S.p.A.
Nice S.p.A.
Hörmann Group
BFT
Automatic Systems
Opportunities
  • Emerging-Market Urban Infrastructure
  • Data Services and Barrier-as-a-Service Models
  • Solar-Powered and Off-Grid Bollards

Automated Barriers Bollards Market Summary

The global Automated Barriers Bollards Market was valued at USD 21.20 Billion in 2025. It is projected to reach USD 22.06 Billion in 2026 and USD 31.53 Billion by 2035, a CAGR of 4.05% over 2026–2035. Two catalysts anchor this outlook. First, the UK Terrorism (Protection of Premises) Act 2025 places protective-security duties on venues that hold 200 or more people [6]. Second, the USD 1.2 trillion US Infrastructure Investment and Jobs Act is funding transport hubs, ports and federal facilities whose vehicle access points are being rebuilt [8].

A steady replacement cycle sits beneath the headline growth. Manual swing arms, fixed concrete blocks and hand-lifted posts are being replaced by motorised barriers and by hydraulic or electromechanical bollards tested to ASTM F2656 and ISO 22343-1:2023 [1][2]. Buyers now set crash ratings, cycle duty and network connectivity in the same tender. The EU has also allocated EUR 1.9 billion through its Internal Security Fund for 2021–2027, and part of it supports the protection of public spaces.

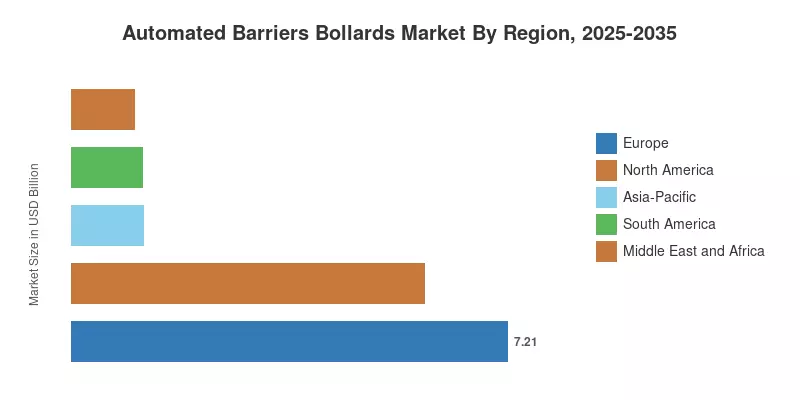
Within the Automated Barriers Bollards Market, Europe is the dominant region with a 34.0% share, supported by dense urban centres and mature hostile-vehicle guidance. Asia-Pacific is the fastest-growing region at a 5.6% CAGR. North America is second-largest at a 27.5% share, backed by federal security spending. Over the forecast decade, demand will shift toward connected, crash-rated systems that also serve as traffic-management assets.

Key Report Takeaways

• By Product Type

  • Barriers lead the Automated Barriers Bollards Market with a 57.0% share in 2025, reflecting their high throughput at parking, toll and logistics gates.
  • Bollards are the faster-growing product type, expanding at a 5.1% CAGR as city centres pedestrianise and adopt permanent crash-rated protection.

• By Control Mechanism

  • Remote Controlled systems hold a 46.1% share, favoured where operators manage many entry points from one control room.
  • Loop Detectors grow at a 5.3% CAGR, the fastest among control mechanisms, as sites cut staffing at vehicle entrances.
  • Push Button systems account for USD 2.75 Billion in 2025, concentrated in residential and small commercial sites.

• By End-User Sector

  • Commercial Buildings capture a 46.0% share of the Automated Barriers Bollards Market, driven by office, retail and industrial security budgets.
  • Others, covering campuses, hospitals, tourism districts and government sites, expand at a 5.5% CAGR.

• By Region

  • Europe holds a 34.0% share of the Automated Barriers Bollards Market, the largest of any region
  • Asia-Pacific posts the highest regional growth at a 5.6% CAGR
  • North America captures a 27.5% share, anchored by federal and critical-infrastructure demand

Market Size and Forecast (2021–2035)

Market Research Future sized the Automated Barriers Bollards Market bottom-up, from installed units and average selling prices by product type, control mechanism and end-user sector. The estimates were cross-checked against company disclosures, public tender records and trade data. Historical values for 2021–2024 reflect reported shipments and completed projects, and forecast values project the 2026–2035 growth path from the 2025 base.
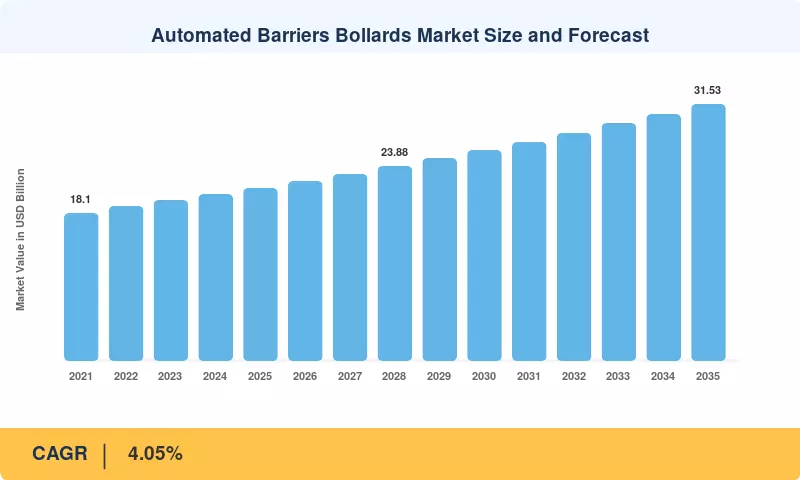
Automated Barriers Bollards Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Impact percentages below are directional estimates of each driver's contribution to the Automated Barriers Bollards Market CAGR. They overlap and interact, so they should not be added together to reproduce the headline growth rate.

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Hostile vehicle mitigation regulation and protective-security law +1.0% Europe, North America Short term (≤2 yr)
Public infrastructure and transport hub investment +0.8% North America, Asia-Pacific Medium term (2–4 yr)
Smart-city programmes and urban pedestrianisation +0.7% Asia-Pacific, Europe, Middle East and Africa Long term (≥4 yr)
Growth in automated parking and toll operations +0.6% Global Medium term (2–4 yr)
Harmonised crash-test standards +0.4% Global Short term (≤2 yr)
Gulf giga-projects and major event venues +0.4% Middle East and Africa Medium term (2–4 yr)
Labour savings from unattended entry points +0.3% North America, Europe Long term (≥4 yr)

Hostile Vehicle Mitigation Regulation and Protective-Security Law

Legislation is turning voluntary guidance into obligation across the Automated Barriers Bollards Market. The UK Terrorism (Protection of Premises) Act 2025 sets a standard tier for venues holding 200–799 people and an enhanced tier for 800 or more, and the enhanced tier must document physical measures [6]. National guidance on hostile vehicle mitigation already points designers toward tested barriers and bollards [5]. As a result, venue operators, local authorities and stadium owners are budgeting for certified equipment instead of temporary blocks. That shortens procurement cycles and favours suppliers with full test portfolios.

Public Infrastructure and Transport Hub Investment

Capital programmes are now reaching the gate. The US Infrastructure Investment and Jobs Act authorised USD 1.2 trillion in spending, including roughly USD 25 billion for airports and USD 17 billion for ports [8]. Every rebuilt terminal, port gate and rail interchange needs controlled vehicle entry, and federal security criteria push owners toward crash-rated systems [20]. These projects run on multi-year timelines. Orders placed in 2024–2026 will therefore turn into installations well into the forecast period.

Smart-City Programmes and Urban Pedestrianisation

Cities are closing streets to traffic, and they need retractable control points that still let emergency and delivery vehicles through. India's Smart Cities Mission covered 100 cities with central support of INR 48,000 crore, and the ASEAN Smart Cities Network links 26 pilot cities across the region [24]. Retractable bollards suit these schemes because they sit flush with the road when lowered. Solar-powered units also avoid trenching in heritage districts, which cuts civil-works cost.

Growth in Automated Parking and Toll Operations

Parking operators are replacing staffed booths with ticketless, plate-recognition entry, but every lane still needs a barrier arm. The UN projects that 68% of the world's population will live in urban areas by 2050 [12], so parking structures, mixed-use developments and private toll roads keep getting built. Barrier arms in these settings cycle thousands of times a day. Operators therefore choose high-duty motors and predictive maintenance, which gives incumbents recurring replacement and service revenue.

Harmonised Crash-Test Standards

Converging standards are simplifying specifications in the Automated Barriers Bollards Market. ISO 22343-1:2023 and ISO 22343-2:2023 put vehicle security barrier testing and application guidance under one international framework [2][3]. They sit alongside ASTM F2656, whose M30 rating corresponds to a 6,800 kg vehicle at 30 mph [1]. Manufacturers can now test once and sell in more jurisdictions. This lowers certification cost per product and lets mid-sized suppliers bid for international tenders that once went only to the largest players.

Gulf Giga-Projects and Major Event Venues

Public investment has been focused on new cities, leisure areas, and sports facilities as part of Saudi Vision 2030 [11]. At the design stage, large, purpose-built sites require integrated perimeter systems, which frequently combine automatic barriers at service entrances with high-security bollards. Over the next ten years, the monarchy also intends to host international athletic events, which raises the need for stadiums and fan zones. Each project has a large volume. When it comes to delivery and post-purchase assistance, suppliers who have regional assembly or distribution partners have an advantage.

Labour Savings From Unattended Entry Points

Rising wages for security staff are pushing site owners to automate gates. Power-operated barriers must meet EN 12453 force and safety limits [22], and buyers now treat these as a baseline rather than an obstacle. With compliant detection in place, one control room can supervise dozens of lanes. Logistics parks and hospitals see the fastest payback because they run around the clock. At these sites, removing even one guard post per shift can recover the equipment cost within a few years.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High installed cost of crash-rated systems -0.6% Global, especially emerging markets Medium term (2–4 yr)
Civil works and underground utility conflicts -0.4% Europe, North America Long term (≥4 yr)
Maintenance burden of hydraulic units -0.3% Global Medium term (2–4 yr)
Machinery safety compliance and liability -0.3% Europe Short term (≤2 yr)
Price competition from low-cost uncertified products -0.2% Asia-Pacific, Middle East and Africa Medium term (2–4 yr)

High Installed Cost of Crash-Rated Systems

Certified bollards are significantly more expensive than decorative posts after foundations, drainage, and controls are taken into account. According to US defense standards, barriers must be selected against a specific threat vehicle and speed [20], and deeper foundations—which require more concrete and excavation—are required for higher ratings. In emerging markets, municipal buyers frequently postpone projects or purchase unproven goods. Premium automated systems are therefore still uncommon outside of capital cities and high-value locations.

Civil Works and Underground Utility Conflicts

City streets are packed with pipes, cables, and sewers, and retractable bollards require a hole for the mechanism. There are shallow-mount choices, according to national guidance; however, they might require broader arrays or have lower ratings [5]. The duration of urban schemes can be doubled by utility studies, road closures, and diversions. By including this risk in their bids, contractors increase project budgets and encourage some councils to use permanent bollards rather than automated ones.

Maintenance Burden of Hydraulic Units

Hydraulic bollards provide high lift force, but they suffer from fluid leaks, seal wear and cold-weather problems. EN 12453 requires periodic safety checks on power-operated equipment [22]. Owners without service contracts face downtime when units fail in the raised or lowered position. Facility managers now often ask for lifetime cost data before they buy. Electromechanical designs solve part of the problem, but they move demand from one drive type to another rather than adding volume.

Machinery Safety Compliance and Liability

Automated barriers and bollards count as machinery. Regulation (EU) 2023/1230 applies from January 2027 and updates requirements for safety functions and software [21]. Manufacturers must revise technical files, risk assessments and conformity documentation. Small installers carry more liability if a lowered bollard injures a cyclist or pedestrian. Compliance costs fall hardest on regional players, which could slow product refreshes in Europe during 2026–2027.

Price Competition From Low-Cost Uncertified Products

In price-led tenders, uncertified barrier arms and bollards sell at a steep discount. Where tenders do not require ISO 22343 or an equivalent standard [2], procurement teams cannot easily compare tested and untested equipment. This squeezes margins for certified suppliers and slows the shift to rated products. Enforcement and buyer education are improving, but the price gap will remain through the medium term.

Automated Barriers Bollards Market Opportunities

Emerging-Market Urban Infrastructure

Vehicle entry control is required from the beginning of the construction of metro systems, airports, and new administrative districts in India, Indonesia, Vietnam, and Egypt[24]. Barrier arms and electromechanical bollards can be assembled locally to keep costs within municipal budgets. Before international companies localize, suppliers can gain market share by combining entry-level certified items with regional service networks.

Data Services and Barrier-as-a-Service Models

Connected units in the Automated Barriers Bollards Market log every vehicle event, fault code and cycle count. Operators can sell occupancy data to parking apps, or offer subscriptions that bundle hardware, monitoring and maintenance for a monthly fee. This turns one-off sales into recurring income and shows suppliers directly when units need replacing.

Solar-Powered and Off-Grid Bollards

Tourism districts, parks and heritage zones often have no grid power where control is needed. Solar-powered bollards with battery storage need no trenching and can be moved when street layouts change. This product line fits the Others end-user category, which is growing faster than residential and commercial demand.

Retrofit of First-Generation Hydraulic Installations

Many hydraulic bollards installed in the 2000s and 2010s are reaching end of life. Replacing them with networked electromechanical units cuts maintenance costs and meets newer standards [1][2]. Retrofit work depends less on construction cycles and gives suppliers with installed-base records predictable demand.

Event and Temporary Rapid-Deployment Systems

Premises-security law covers events as well as permanent buildings [6]. Crash-tested barriers that deploy in hours open a rental and service market for festivals, marathons and fan zones. Rental fleets also introduce buyers to certified products, and some of those rentals can turn into permanent orders.

Automated Barriers Bollards Market Future Outlook

AI-Enabled Vehicle Recognition and Autonomous Gate Control

Entry points across the Automated Barriers Bollards Market are shifting from push-button and remote control to automatic decisions based on plate recognition, vehicle classification and booking data. Loop detectors and camera analytics will increasingly trigger barriers with no human input. By the early 2030s, many commercial sites will run unattended lanes under remote supervision. Supplier value will shift toward software, integration and the cybersecurity of control systems [21].

Electromechanical Replacement of Hydraulic Drives

Electromechanical bollards use no hydraulic fluid, start reliably in cold weather and draw less standby power. As first-generation hydraulic fleets age, owners will switch drive types when they replace them [22]. This shift favours manufacturers that design their own motors and controllers. It will raise average selling prices slightly while lowering lifetime cost.

Urbanisation and the Car-Light City

Urban populations will keep growing, with 68% of people expected to live in cities by 2050 [12]. The World Bank estimates that cities already generate more than 80% of global GDP [13]. Car-free zones, low-emission districts and delivery windows all need controllable access. Retractable bollards will serve as traffic-policy tools as much as security devices, so transport departments, not just security teams, will start buying them.

Sustainability and Whole-Life Reporting

Public buyers are adding embodied-carbon and energy criteria to tenders. Solar-powered bollards, low-standby controllers and recyclable steel housings help suppliers score well on these criteria. Corporate owners that report under sustainability disclosure rules will ask for product carbon data. Suppliers that can document materials and energy use across the product life will benefit [21].

Regional Market Share Analysis

Region Key Metric (2025) Primary Investment Themes
North America 27.5% share Federal facility security, airports and ports, parking automation
Europe 34.0% share Protective-security law, pedestrianised city centres, retrofits
Asia-Pacific 5.6% CAGR Smart cities, metro and airport construction, gated housing
South America USD 1.17 Billion Commercial real estate, toll roads, private security
Middle East and Africa 4.9% CAGR Giga-projects, event venues, critical infrastructure
Total USD 21.20 Billion –

Regional demand in the Automated Barriers Bollards Market follows security regulation, urban density and infrastructure budgets. Europe leads on share, North America on spend per site, and Asia-Pacific on growth.

North America

Country Key Metric (2025) Key Driver
United States 81.0% share of region Federal security criteria and infrastructure funding
Canada USD 0.62 Billion Transit and campus security upgrades
Mexico 8.4% share of region Industrial parks and nearshoring logistics hubs

The United States dominates regional demand because federal buildings, embassies and military installations must meet defined vehicle-barrier criteria [20]. These specifications have spread to stadiums, data centres and corporate campuses. Infrastructure funding for airports and ports adds a multi-year pipeline [8]. In Canada, demand centres on transit stations and university campuses. Mexico is gaining from industrial parks built for nearshored manufacturing, where truck gates need high-cycle barriers.

Europe

Country Key Metric (2025) Key Driver
Germany 21.5% share of region Industrial sites and Christmas-market protection
UK USD 1.30 Billion Protective-security legislation and national guidance
France 14.0% share of region Urban pedestrianisation and major event security
Italy USD 0.72 Billion Home base of leading gate-automation manufacturers
Spain 7.5% share of region Tourism districts and coastal promenades
Nordic Countries USD 0.50 Billion Cold-climate electromechanical systems
Russia 5.0% share of region Government and industrial facility security
Rest of Europe USD 1.23 Billion EU-funded public-space protection

Europe's leadership in the Automated Barriers Bollards Market rests on a long history of responding to vehicle attacks and a dense manufacturing base. The UK combines tested-product guidance [5] with new statutory duties [6], which makes it the region's most structured specification market. Germany and France spend heavily on protecting festive markets and closing city centres to traffic. The EU's public-space protection agenda also channels funds to member states. Italy is home to several of the largest automation manufacturers, so its export influence far exceeds its domestic demand.

Asia-Pacific

Country Key Metric (2025) Key Driver
China 38.0% share of region Smart parking and new urban districts
India USD 0.83 Billion Smart Cities Mission and airport expansion
Japan 16.0% share of region Parking automation and event venues
South Korea USD 0.44 Billion Smart-city pilots and apartment complexes
ASEAN 12.5% share of region ASEAN Smart Cities Network projects
Rest of Asia-Pacific USD 0.57 Billion Australian public-space security programmes

Asia-Pacific grows fastest in the Automated Barriers Bollards Market because new construction still outpaces retrofit. China's large parking stock and plate-recognition rollout create volume demand for barrier arms. India's Smart Cities Mission funded command centres and controlled-access zones across 100 cities. Japan and South Korea prefer compact, high-reliability units for dense residential sites. ASEAN cities are adding retractable bollards under coordinated smart-city plans [24], and domestic manufacturers compete hard on price.

South America

Country Key Metric (2025) Key Driver
Brazil 52.0% share of region Gated communities and commercial security
Argentina USD 0.20 Billion Toll roads and logistics terminals
Rest of South America 30.9% share of region Mining sites and urban parking in Chile, Colombia and Peru

Brazil leads South American demand because high private-security spending pays for automated entry at condominiums, shopping centres and corporate parks. Argentina's market depends on toll concessions and port terminals, but currency volatility delays purchases of imported equipment. Chile, Colombia and Peru add demand from mining sites and growing urban parking. Buyers across the region put cost and robustness first, which favours barrier arms over premium crash-rated bollards [13].

Middle East and Africa

Country Key Metric (2025) Key Driver
Saudi Arabia 27.0% share of region Vision 2030 giga-projects and sports venues
UAE USD 0.33 Billion Airports, hotels and government complexes
South Africa 13.5% share of region Estate security and commercial parks
Egypt USD 0.14 Billion New Administrative Capital construction
Rest of Middle East and Africa 27.7% share of region Oil and gas facilities and embassy security

Saudi Arabia drives regional growth because Vision 2030 projects specify integrated perimeter systems at the design stage [11]. The UAE has a mature base of high-security installations at airports, hotels and government buildings. South Africa's strong estate-security culture keeps demand for barrier arms steady, and Egypt's new capital city generates government orders. Oil and gas facilities across the Gulf and North Africa add demand for high-rated anti-ram perimeter protection.

Automated Barriers Bollards Market By Region, 2025-2035

Automated Barriers Bollards Market Segmentation

By Product Type

The Automated Barriers Bollards Market by product type splits into Barriers and Bollards, which meet different site needs.

Segment Key Metric (2025) Primary Demand Driver
Barriers 57.0% share High-throughput parking, toll and logistics gates
Bollards 5.1% CAGR Crash-rated perimeter protection in pedestrian areas

Barriers hold the majority because almost every parking lane, toll booth and truck gate needs a fast-cycling arm linked to ticketing or plate recognition. Bollards grow faster because city centres and public venues need protection that blends into the streetscape and stays out of pedestrians' way. High-security bollards can stop a 7.5-tonne vehicle at 48 km/h [19]. Smart-city schemes are also adding solar-powered units in tourism districts where power is limited.

By Control Mechanism

In the Automated Barriers Bollards Market, the control mechanism sets labour cost, audit capability and how well a system links to wider security systems.

Segment Key Metric (2025) Primary Demand Driver
Push Button USD 2.75 Billion Simple operation at residential and small commercial sites
Remote Controlled 46.1% share Centralised management of multiple entry points
RFID/Smart-Card 4.4% CAGR Credential-based entry with audit trails
Loop Detectors 5.3% CAGR Unattended, high-traffic lanes
Others 7.6% share Biometric and mobile-app control in premium sites

Remote Controlled systems lead because operators of campuses, government sites and commercial complexes want to run many gates from one control room. Loop Detectors grow fastest as owners remove staff from entry lanes and rely on embedded sensors to detect vehicles. RFID/Smart-Card systems grow steadily on demand for audit trails, and Push Button remains a reliable choice for small sites. Proprietary encrypted radio protocols help remote systems work where urban radio bands are crowded [16].

By End-User Sector

End-user demand in the Automated Barriers Bollards Market depends on how each sector weighs security against cost.

Segment Key Metric (2025) Primary Demand Driver
Residential Buildings USD 5.85 Billion Gated communities and premium apartment complexes
Commercial Buildings 46.0% share Office, retail and industrial security budgets
Others 5.5% CAGR Tourism districts, education, healthcare and government

Commercial Buildings lead because offices, retail centres and industrial sites have larger security budgets and connect barriers to building management and access platforms. Others are the fastest-growing sector, covering tourism districts, universities, hospitals and government facilities that are adopting automated entry for safety and traffic flow. Residential Buildings remain stable, but cost and customisation needs keep adoption mostly to gated communities and premium developments.

Competitive Benchmarking

The Automated Barriers Bollards Market is moderately concentrated. The top five suppliers hold an estimated 30–38% of revenue, and the HHI is estimated at roughly 900–1,100, a moderately fragmented structure. Italian and German gate-automation groups lead in barrier arms and residential systems, while specialist UK and US firms lead in crash-rated bollards. Below the top tier, hundreds of regional installers and low-cost manufacturers compete on price.

Company Est. Revenue Share Range Key Offerings for Automated Barriers and Bollards Strategic Positioning
FAAC Group ~8–11% Automatic barriers, hydraulic and electromechanical bollards, parking systems Broad portfolio with Magnetic Autocontrol barrier brand; global distribution
CAME S.p.A. ~7–10% Road barriers, high-security bollards, parking management Integrated entrance automation across residential to high-security [19]
Nice S.p.A. ~5–8% Road barriers, bollards, connected home and building automation Smart-home ecosystem and acquisitive growth [15]
Hörmann Group ~4–7% Barriers, bollards, industrial doors and gates Strong European industrial and commercial channel [16]
BFT (Somfy Group) ~2–4% Barriers, automatic bollards, gate operators Residential and light-commercial focus backed by Somfy [17]
Automatic Systems ~2–4% Road barriers, entrance control, high-security bollards Specialist in vehicle and pedestrian entrance control
ATG Access ~2–4% Crash-rated bollards, rapid-deploy and shallow-mount systems High-security specialist within Hill & Smith
Delta Scientific ~2–4% Crash-rated bollards, wedge barriers, beam barriers Leading US supplier to government and defence sites [23]
Avon Barrier ~1–3% Crash-tested bollards, road blockers, barriers UK perimeter security specialist
Frontier Pitts ~1–3% Barriers, bollards, rising kerb systems, gates UK manufacturer with tested HVM portfolio
Macs Automated Bollard Systems ~1–2% Automatic and security bollards, road blockers UK bollard specialist serving urban schemes

Recent News & Developments

  • National Protective Security Authority (March 2023): The UK formed the National Protective Security Authority from the former Centre for the Protection of National Infrastructure, consolidating physical-security guidance, including vehicle barrier advice used by specifiers [5]
  • European Union (June 2023): Regulation (EU) 2023/1230 on machinery was published, setting new safety obligations for powered barriers and bollards that apply from January 2027 [21]
  • UK Government (September 2024): The Terrorism (Protection of Premises) Bill was introduced to Parliament, signalling statutory duties that venue owners began budgeting for ahead of enactment [6]
  • Ministry of Housing and Urban Affairs, India (March 2025): The Smart Cities Mission reached its extended completion deadline, with finished projects including controlled-access zones and command centres across participating cities
  • Hill & Smith PLC (March 2025): The group published its 2024 annual results, covering its roads and security businesses, which include crash-rated barrier specialist ATG Access
  • UK Parliament (April 2025): The Terrorism (Protection of Premises) Act 2025 received Royal Assent, creating standard and enhanced protective-security tiers for public venues and events [6]

Automated Barriers Bollards Market Report Scope

Parameter Details
Market Scope The Automated Barriers Bollards Market covers barriers and bollards, including control mechanisms, sold through direct, distributor and installer channels to residential, commercial and other end users.
Study Period 2021–2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 21.20 Billion
Market Size in 2035 USD 31.53 Billion
CAGR (2026–2035) 4.05%
Fastest Growing Segments Others (5.5% CAGR); Loop Detectors (5.3% CAGR); Bollards (5.1% CAGR)
Regions Covered North America, Europe, South America, Asia Pacific, Middle East and Africa and ROW
Companies Profiled FAAC Group, CAME S.p.A., Nice S.p.A., Hörmann Group, BFT, Automatic Systems, ATG Access, Delta Scientific, Avon Barrier, Frontier Pitts, Macs Automated Bollard Systems
Valuation Currency USD Billion
Methodology 350+ primary expert interviews; bottom-up market sizing; top-down validation; data triangulation; scenario-based forecasting; real-time project tracking

FAQs

Which crash rating should buyers specify in the Automated Barriers Bollards Market?
Match the rating to the realistic threat vehicle and approach speed found in a site survey [20]. Over-specifying adds foundation depth and cost without improving protection where run-up distance is short.
Are electromechanical or hydraulic bollards better for cold climates?
Electromechanical bollards generally perform better because they avoid fluid thickening and seal failures at low temperatures [22]. Hydraulic units need heaters and more frequent servicing in sub-zero conditions.
How do procurement teams compare PAS 68, ASTM F2656 and ISO 22343 ratings?
Each standard uses different vehicle classes and speeds, so ratings are not directly interchangeable [4]. Request the full test report, including vehicle mass, speed and penetration distance, rather than relying on the rating code alone.
What integration challenges affect the Automated Barriers Bollards Market?
Legacy control panels in the Automated Barriers Bollards Market often lack open protocols, which complicates links to video management and plate-recognition software [9]. Specifying open, documented interfaces at tender stage avoids costly gateway hardware later.
Can shallow-mount bollards replace deep-foundation units?
Shallow-mount systems suit sites with buried utilities and can be installed faster [5]. They often need wider arrays or carry lower ratings, so engineers should confirm tested performance for the specific layout.
Where are investors finding value in the Automated Barriers Bollards Market?
Service contracts and retrofit work in the Automated Barriers Bollards Market offer steadier returns than new-build projects tied to construction cycles . Firms with large installed bases and certified test portfolios command premium valuations.
How do rapid-deployment barriers differ from permanent systems?
Rapid-deployment barriers rest on the surface and can be installed in hours for events [6]. They trade some long-term durability for flexibility, making rental and short-term contracts their main commercial model.
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















