Asia-Pacific Warehouse Automation Market Summary
The Asia-Pacific Warehouse Automation Market was valued at USD 15.15 Billion in 2025 and is projected to open the forecast window at USD 18.55 Billion in 2026 before reaching USD 71.10 Billion by 2035, expanding at a 16.1% CAGR across 2026–2035. Two catalysts anchor that trajectory. China's Ministry of Industry and Information Technology extended its smart logistics guidance in 2024 with capital subsidies covering up to 20% of qualifying equipment spend for certified facilities [3], while India's PM Gati Shakti master plan committed more than USD 1.3 trillion to multimodal infrastructure corridors that require mechanised inland nodes to function [13].
Operators across the region are retiring a specific generation of assets: fixed pick-to-light walls, manually driven forklifts, and batch-mode warehouse control layers written against on-premise ERP instances. Replacing them are dense mobile robot fleets, shuttle-based storage grids, and real-time execution software that arbitrates tasks against live order flow. Japan's Ministry of Economy, Trade and Industry estimated in 2024 that domestic logistics operators would need to lift labour productivity by 30% before 2030 simply to preserve current service levels under tightening driver-hour rules [5].
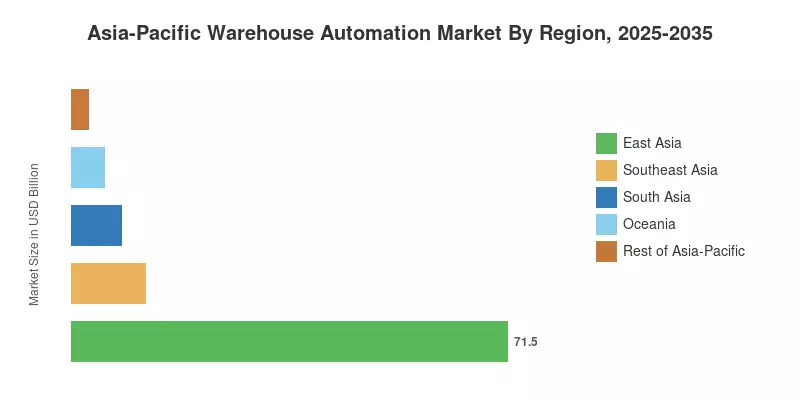
East Asia holds the dominant position with 71.5% of 2025 revenue, propelled by Chinese parcel volumes and Japanese retrofit programmes. South Asia is the fastest-growing sub-region at a 17.3% CAGR, and Southeast Asia ranks second in growth as Singapore, Indonesia and Vietnam build regional distribution capacity for cross-border e-commerce. Through 2035, the Asia-Pacific Warehouse Automation Market will shift from throughput-led justification toward density and energy-per-order economics.
Key Report Takeaways
• By Component
- Hardware retained 63.8% of Asia-Pacific Warehouse Automation Market revenue in 2025, anchored by mobile robot fleets and shuttle storage.
- Services are the fastest-expanding component line at a 16.7% CAGR across 2026–2035 as integration and predictive maintenance contracts lengthen.
• By End-User
- Food and Beverage led all verticals with 21.5% share of the Asia-Pacific Warehouse Automation Market in 2025
- Groceries post the highest vertical growth rate at a 17.5% CAGR, driven by cold-chain compliance and sub-hour delivery promises.
• By Warehouse Function
- Distribution Centers accounted for 38.5% of 2025 revenue as regional master hubs absorbed the largest single deployments.
- Micro-Fulfillment Centers register a 17.2% CAGR, the fastest of any function.
• By Warehouse Size
- Large facilities above 250,000 sq ft captured 43.5% share in 2025
- Small sites below 50,000 sq ft grow at a 16.7% CAGR as inner-city rents push operators toward vertical storage
• By Country
- China contributed 52.9% of Asia-Pacific Warehouse Automation Market revenue in 2025
- India records the fastest national growth at a 17.3% CAGR through 2035
• By Region
- East Asia held 71.5% of regional revenue in 2025
- South Asia is the fastest-growing sub-region, while Southeast Asia generated USD 1.83 billion in 2025
Market Size and Forecast (2021–2035)
Historical values for 2021–2024 were reconstructed from installed-base tracking of automated equipment shipments, integrator contract awards, and audited segment disclosures in vendor annual reports. Forecast values apply a bottom-up build across five component lines and seven end-user verticals, cross-checked against parcel volume growth, warehouse construction starts, and equipment lead-time data. The 2026 step-change reflects the conversion of pilot installations commissioned during 2024–2025 into full-scale rollouts, together with the first tranche of subsidised Chinese cold-chain retrofits reaching revenue recognition.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



