Artificial Lift System Market (2026 - 2035)

Artificial Lift System Market Research Report By Type (Rod Lift, Electrical Submersible Pump, Gas Lift, Progressing Cavity Pump, Plunger Lift, Hydraulic Pumping), By Mechanism (Pump Assisted, Gas Assisted), By Application (Onshore, Offshore), By Well Type (Horizontal, Vertical) - Forecast to 2035
ID: MRFR/EnP/21091-HCR 100 Pages Chitranshi Jaiswal Last Updated: October 16, 2026
Artificial Lift System Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.4%
2025 Market SizeUSD 9.60 Billion
2035 Market SizeUSD 16.26 Billion
Key Players
SLB
Baker Hughes
Halliburton
Weatherford International
NOV Inc.
ChampionX
Opportunities
  • Outcome-Based Lift Contracting
  • Emerging-Market Brownfield Access
  • Downhole Data Monetization

Artificial Lift System Market Summary

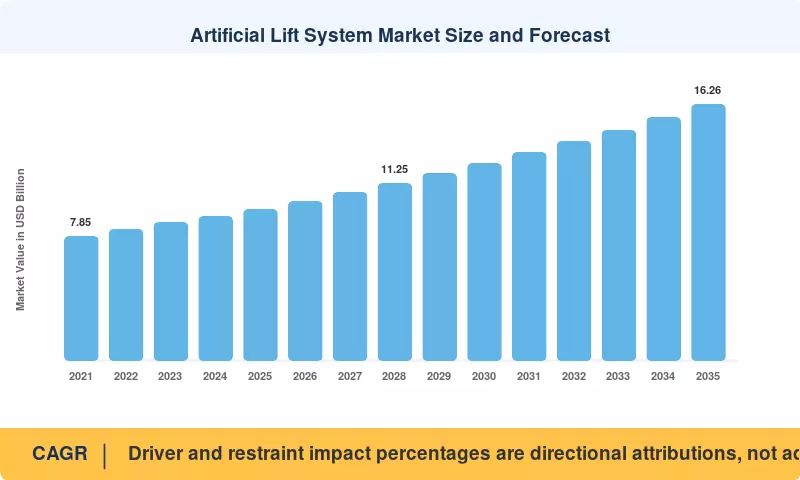
The Artificial Lift System Market closed the 2025 base year at USD 9.60 billion and enters the forecast window at USD 10.12 billion in 2026. On a 5.4% compound growth rate through 2035, the Artificial Lift System Market reaches USD 16.26 billion by the end of the decade. Two catalysts anchor that trajectory: the persistent 8–12% annual base decline across mature onshore basins reported by the U.S. Energy Information Administration , and roughly USD 570 billion in annual upstream capital spending that the International Energy Agency tracks globally, a growing share of which is redirected toward production optimization rather than new exploration [1].

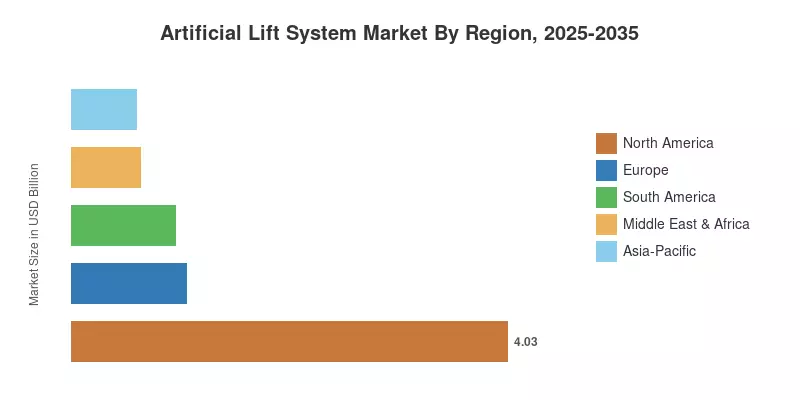
North America holds 42% of 2025 revenue, built on more than 900,000 producing wells that almost all require assistance. Middle East & Africa grows fastest at 6.7% as national oil companies push brownfield redevelopment across Kuwait, Oman, and the UAE. Asia-Pacific ranks third, driven by China's tight-oil programs and India's Mumbai High revitalization. Through 2035, the Artificial Lift System Market shifts from equipment supply toward outcome-based production management.


Key Report Takeaways

• By Technology

  • Rod lift retains 34% of 2025 revenue in the Artificial Lift System Market, sustained by low-rate stripper wells across Texas, Oklahoma, and Alberta
  • Electrical submersible pumps contributed roughly USD 3.07 billion in 2025, the largest single-technology dollar pool
  • Progressing cavity systems expand at 6.1% CAGR on heavy-oil and coalbed methane demand

• By Sector

  • Onshore applications account for 82% of installed value across the Artificial Lift System Market
  • Offshore lift grows at 6.4% CAGR as subsea boosting moves into deepwater Brazil and West Africa
  • Horizontal wells represent 58% of new lift installations globally

• By Region

Market Size and Forecast (2021–2035)

Sizing blends bottom-up equipment shipment tracking with top-down reconciliation against operator capital disclosures. Well-count baselines come from national regulators; unit pricing is triangulated across supplier order books and tender awards. Historical revenue for the Artificial Lift System Market is deflated to constant 2025 dollars, then re-inflated using regional producer price indices.
Artificial Lift System Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Mature field decline and secondary recovery mandates +1.1 North America, Middle East Long-term (≥4 yr)
Unconventional well lift conversions +0.9 North America Medium-term (2–4 yr)
National oil company brownfield redevelopment +0.8 Middle East, South America Long-term (≥4 yr)
Digital lift optimization and remote monitoring +0.7 Global Medium-term (2–4 yr)
Permanent magnet motor and VSD efficiency gains +0.5 Global Short-term (≤2 yr)
Gas well deliquification on aging shale gas assets +0.4 North America, Asia-Pacific Medium-term (2–4 yr)
Subsea boosting and deepwater deployment +0.4 South America, West Africa Long-term (≥4 yr)


Decline Curves Are the Structural Engine

A long-term compound annual growth rate expansion of +1.1% is driven by secondary recovery mandates and mature field decline in fundamental producing regions such as the Middle East and North America . Operators must use long-term asset management as a key driver of the demand for specialized oilfield equipment in order to stabilize production when legacy assets run out.


Unconventional Wells Change Lift Economics

Over the course of a single well's life, shale operators usually operate three or four lift regimes: natural flow, gas lift, ESP, and rod. Failure frequency was the biggest swing variable, with Permian Basin operators reporting an average lift-related opex of USD 4.10 per barrel in 2024 [4]. A significant amount of wallet share is obtained by vendors who shorten the ESP-to-rod transition.


Digital Optimization Converts Capex into Contracts

Automated production platforms deployed across roughly 40,000 wells have demonstrated 15–20% reductions in unplanned deferrals [9]. Operators increasingly buy uptime rather than pumps, which pulls software and analytics revenue into equipment budgets and lifts blended margins for suppliers.

Efficiency Regulation Reaches the Wellsite

The U.S. Department of Energy's integral horsepower motor rules and comparable EU ecodesign tiers push surface drive replacement on a defined schedule [3]. Permanent magnet motors cut wellsite power draw by 8–15% versus legacy induction units, a saving that matters most where grid tariffs exceed USD 0.09/kWh.


Restraints Impact Analysis

Restraint weightings reflect estimated drag on the headline growth rate under a mid-case commodity scenario. They are directional and interact with one another; a sustained price shock would amplify several simultaneously rather than adding them in sequence.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Oil price volatility and capex cyclicality −0.9 Global Short-term (≤2 yr)
Workover and intervention cost inflation −0.6 North America Medium-term (2–4 yr)
Energy transition capital reallocation −0.5 Europe, Global Long-term (≥4 yr)
Power availability at remote wellsites −0.4 Middle East & Africa, Asia-Pacific Medium-term (2–4 yr)
Skilled field technician shortage −0.3 North America, Europe Medium-term (2–4 yr)


Price Sensitivity Remains Unresolved

Upstream budgets still track the strip. When WTI dipped below USD 65 in mid-2024, several independents deferred lift optimization programs by two quarters even though payback periods were unchanged . Discretionary retrofit spending, roughly a fifth of annual demand, is the first line cut.

Intervention Costs Erode the Business Case

Rig-assisted ESP replacement in West Texas ranged from USD 220,000 to USD 340,000 in 2024, up materially from 2021 levels [4]. Higher pull costs favor longer-run-life equipment, but they also push marginal wells toward shut-in rather than repair, shrinking the addressable installed base.

Capital Competes with Decarbonization Mandates

European majors have committed a rising share of capital to low-carbon lines, and the UK Energy Profits Levy has depressed North Sea reinvestment since 2022 [6]. That reallocation caps European growth well below the global average and shifts vendor focus toward Gulf and Latin American tenders.


Artificial Lift System Market Opportunities

Outcome-Based Lift Contracting

Operators are shifting from purchase orders to per-barrel-lifted service agreements. Vendors absorbing failure risk earn recurring revenue and lock in multi-year installed-base access, a model already piloted across roughly 6,000 wells in the Middle East .

Emerging-Market Brownfield Access

Nigeria's divested onshore assets, Colombia's heavy-oil belt, and Indonesia's mature Rokan block all require large-scale lift retrofits with limited incumbent lock-in. These geographies represent the clearest white space in the Artificial Lift System Market for challenger suppliers [15].

Downhole Data Monetization

Sensor-equipped completions generate continuous pressure, temperature, and vibration telemetry that most operators still discard. Suppliers building failure-prediction models across pooled fleet data can license benchmarking insights back to customers, creating margin uncoupled from steel [9].

Gas Deliquification in Late-Life Assets

As reservoir pressure decreases, mature Haynesville and Marcellus wells load more liquids. The number of qualified wells increases annually, and low-cost plunger lift gas well deliquification restores rates for a portion of an ESP install .


Electrification and Grid-Connected Wellsites

Converting diesel-powered surface equipment to grid or solar-hybrid power simultaneously lowers operational costs and scope 1 emissions. Utilities are entering into ten-year supply agreements, and thousands of pads are already covered by Permian electrification schemes [12].


Artificial Lift System Market Future Outlook

Autonomous Production Operations

Closed-loop control — where downhole data adjusts drive frequency without human intervention — moves from pilot to standard specification. Early deployments show 3–6% production uplift on comparable well sets [9]. By the early 2030s, expect autonomous setpoint management to be a tender requirement rather than a differentiator.

Fleet Economics and Run-Life Competition

Suppliers now compete on mean time between failures more than on unit price. A run-life improvement from 14 to 22 months changes lifetime cost of ownership by more than 30% on a typical unconventional well [4]. That metric increasingly determines award decisions across the Artificial Lift System Market.

Wellsite Electrification

The International Energy Agency projects continued growth in electrified upstream operations as grid access expands into producing basins [1]. Replacing diesel prime movers with grid-connected drives lowers both emissions intensity and fuel exposure, and utilities are signing long-dated supply contracts to underwrite it.

Methane and Emissions Disclosure

Regulations including U.S. EPA subpart OOOOb and the EU methane import standard tighten reporting on venting and equipment leaks [3][6]. Lift equipment sits directly in scope through casing gas handling, and vendors offering verified emissions performance gain preferential access to European-bound barrels.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 42% share Shale lift conversions, electrification, failure reduction
Europe USD 1.06 Billion North Sea life extension, Caspian tie-backs
Asia-Pacific 6.2% CAGR Tight oil, CBM, offshore redevelopment
South America USD 0.96 Billion Pre-salt boosting, heavy-oil recovery
Middle East & Africa 6.7% CAGR Brownfield programs, capacity expansion
Total USD 9.60 Billion —

Geographic demand within the Artificial Lift System Market tracks well count, well age, and fiscal terms more closely than it tracks headline production volume.


North America

Country Metric Key Driver
United States 81% of region Permian and Bakken lift conversions
Canada USD 0.63 Billion Heavy oil and SAGD lift demand
Mexico 5.9% CAGR Pemex shallow-water redevelopment


Scale defines this region. More than 900,000 producing wells exist across the U.S. alone, of which the vast majority operate below 15 barrels per day and depend on mechanical assistance . Operators have consolidated supplier lists aggressively since 2023, favoring vendors that bundle equipment, monitoring, and field service under one accountability line.

Europe

Country Metric Key Driver
Norway 34% of region Johan Sverdrup-era water injection support
United Kingdom USD 0.21 Billion Late-life field extension
Romania 6.0% CAGR Black Sea and onshore redevelopment


Fiscal policy shapes outcomes more than geology here. The UK levy has suppressed discretionary intervention spending, while Norway's investment allowances continue to support platform upgrades [6]. Central and Eastern European operators, meanwhile, are retrofitting Soviet-era beam units with modern drives at attractive returns.

Asia-Pacific

Country Metric Key Driver
China 46% of region Changqing and Daqing tight-oil programs
India 6.8% CAGR Mumbai High and Rajasthan redevelopment
Indonesia USD 0.19 Billion Rokan block production recovery


Energy security drives procurement across the region. China's national producers have committed to sustained domestic output targets, requiring dense lift deployment in low-permeability reservoirs [15]. India's ONGC continues to tender multi-year lift service packages tied to offshore field revitalization.

South America

Country Metric Key Driver
Brazil 58% of region Pre-salt and Campos Basin revitalization
Argentina 7.1% CAGR Vaca Muerta unconventional scale-up
Colombia USD 0.14 Billion Heavy-oil progressing cavity demand


Argentina is the standout. Vaca Muerta output has climbed steadily as pipeline capacity opened, and the well profile there mirrors the Permian closely enough that lift vendors transfer playbooks directly [14]. Brazil's demand skews toward high-specification subsea boosting rather than conventional surface equipment.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 31% of region Capacity maintenance and gas expansion
United Arab Emirates 7.2% CAGR Production capacity target programs
Nigeria USD 0.16 Billion Divested onshore asset rehabilitation


Contracting structure distinguishes this region. National oil companies increasingly award five- to ten-year framework agreements covering supply, installation, and run-life guarantees, which rewards incumbents with local manufacturing footprints . Kuwait and Oman have both expanded ESP fleets substantially since 2023.


Artificial Lift System Market By Region, 2025-2035

Artificial Lift System Market Segmentation

By Type

Technology mix within the Artificial Lift System Market reflects productivity more than geography.

Segment Metric (2025) Primary Demand Driver
Rod Lift 34% share Stripper well population
Electrical Submersible Pump USD 3.07 Billion High-volume and offshore wells
Gas Lift 16% share Deviated wells and sandy fluids
Progressing Cavity Pump 6.1% CAGR Heavy oil and CBM
Plunger Lift USD 0.48 Billion Liquid-loaded gas wells
Hydraulic Pumping 4.9% CAGR Remote and high-temperature wells


Rod lift endures because it is cheap, serviceable by local crews, and well matched to sub-20 bpd production. ESP demand grows faster in dollar terms, since unit prices run five to ten times higher and offshore specifications carry premium pricing. A hydraulic jet pump lift system remains a niche solution, valuable where sand and deviation defeat rotating equipment but rarely deployed at fleet scale.

By Mechanism

Segment Metric (2025) Primary Demand Driver
Pump Assisted 79% share Broad applicability across well types
Gas Assisted 5.8% CAGR Offshore and high-GOR reservoirs


Pump-assisted systems dominate the Artificial Lift System Market by installed count and revenue alike. Gas-assisted methods grow faster where associated gas is abundant and compression infrastructure already exists, which describes most offshore platforms and much of the Middle East.

By Application

Segment Metric (2025) Primary Demand Driver
Onshore 82% share Sheer well density
Offshore 6.4% CAGR Subsea boosting and deepwater tie-backs


Onshore volume anchors the Artificial Lift System Market, but offshore carries better margins. Deepwater boosting projects in Brazil and Angola involve engineered systems with multi-year qualification cycles, high barriers to entry, and correspondingly durable pricing.

By Well Type

Segment Metric (2025) Primary Demand Driver
Horizontal 58% share Unconventional completion growth
Vertical USD 4.03 Billion Legacy conventional inventory


Horizontal wells command a dominant 58% share driven by unconventional completion growth, whereas vertical applications represent a USD 4.03 billion market sustained by legacy conventional inventory.


Competitive Benchmarking

Concentration is moderate. The top five suppliers hold an estimated 48–54% of global revenue, implying an HHI in the 750–900 range — competitive at the global level but considerably tighter within specific technology pools, where ESP supply in particular has consolidated since 2023. Regional specialists retain meaningful share in rod lift and plunger applications, where service proximity outweighs brand.

Company Est. Revenue Share Range Key Offerings for Artificial Lift System Market Strategic Positioning
SLB ~14–18% ESP systems, gas lift, production software Broadest portfolio post-consolidation
Baker Hughes ~11–14% ESP, PCP, automated production platforms Digital-led differentiation
Halliburton ~8–11% ESP, intelligent completions, optimization Integrated well-service bundling
Weatherford International ~7–10% Rod lift, gas lift, ESP, plunger systems Multi-technology breadth
NOV Inc. ~5–8% Rod lift, PCP, hydraulic systems Manufacturing depth
ChampionX ~5–8% Rod lift, ESP, digital monitoring Production chemistry adjacency
Borets International ~3–6% ESP systems and drives Cost-competitive ESP supply
Levare International ~2–4% ESP systems and services Middle East field concentration
Novomet ~2–4% ESP, permanent magnet motors Efficiency-focused engineering
Dover Corporation ~2–4% Rod lift components, pumping units Component and aftermarket supply


Recent News & Developments

  • SLB (July 2025): Completed its acquisition of ChampionX following regulatory clearances, materially consolidating global artificial lift and production chemistry supply [18].


  • Baker Hughes (March 2024): Expanded deployment of its automated field production platform with multiple North American independents, targeting deferral reduction [9].
  • U.S. EPA (March 2024): Finalized subpart OOOOb standards covering methane emissions from production equipment, bringing casing gas handling into compliance scope [3].


  • Halliburton (2025): Extended its production solutions portfolio with additional ESP monitoring and optimization capability for unconventional operators [11].
  • Petrobras (2025): Progressed Campos Basin revitalization tenders including subsea boosting scope for mature deepwater assets [8].


Artificial Lift System Market Report Scope

Report Attribute/Metric Details
Market Scope Global Artificial Lift System Market equipment, components, software, and associated services
Study Period 2021-2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 9.60 Billion
Market Size in 2035 USD 16.26 Billion
CAGR (2026–2035) 5.4%
Fastest Growing Segments Progressing Cavity Pump (type); Offshore (application); Middle East & Africa (region)
Regions Covered North America, Europe, South America, Asia Pacific, Middle East and Africa and ROW
Companies Profiled SLB, Baker Hughes, Halliburton, Weatherford, NOV, ChampionX, Borets, Levare, Novomet, Dover
Valuation Currency USD Billion
Methodology 350+ primary expert interviews; bottom-up market sizing; top-down validation; data triangulation; scenario-based forecasting; real-time project tracking

FAQs

What should a buyer prioritize when evaluating vendors in the Artificial Lift System Market?
Weight demonstrated run-life on analog wells above unit price. Request field-verified mean-time-between-failure data for your specific fluid and deviation profile, not fleet averages [4].
How do warranty and run-life guarantees typically work?
Most suppliers offer pro-rated credit if a unit fails before a contracted threshold, commonly 12 to 18 months. Guarantees usually exclude sand, scale, and operator-induced damage, so failure attribution language matters more than headline terms .
When does converting from ESP to rod lift make financial sense?
Conversion usually pays off once declining rates fall below roughly 150 barrels per day and ESP failure frequency rises. Timing depends on workover cost and available rig scheduling [4].
What integration challenges arise when adding monitoring to existing installations?
Legacy drives often lack open communication protocols, forcing gateway hardware and custom mapping. Power quality at remote sites also disrupts telemetry more often than operators anticipate [9].
Does the Artificial Lift System Market face meaningful supply chain risk?
Specialty magnet materials and high-temperature elastomers carry concentrated sourcing exposure. Lead times for large-frame motors have stretched during demand peaks, so early ordering protects project schedules [19].
How does the Artificial Lift System Market treat aftermarket versus original equipment revenue?
Aftermarket parts and repair typically generate steadier margins than new equipment sales. Suppliers with dense regional service networks capture that recurring stream more reliably than pure manufacturers .
What regulatory nuance most affects procurement in the Middle East?
In-country value requirements increasingly govern award decisions, obliging suppliers to localize manufacturing or assembly. Vendors without regional facilities face scoring penalties regardless of technical merit .    
Author
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.