Air Circuit Breaker Market (2026 - 2035)

Air Circuit Breaker Market Size, Share & Growth Analysis Report By Type (Drawout, Fixed), By Pole Configuration (3-Pole, 4-Pole), By End-User Application (Industrial, Commercial, Utilities, Others) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) – Industry Growth & Forecast to 2035
ID: MRFR/EnP/31774-HCR 100 Pages Chitranshi Jaiswal Last Updated: September 17, 2026
Air Circuit Breaker Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.2%
2025 Market SizeUSD 4.18 Billion
2035 Market SizeUSD 7.62 Billion
Key Players
ABB
Schneider Electric
Siemens
Eaton
Mitsubishi Electric
Legrand
Opportunities
  • Smart-Building Integration and Energy Management
  • Emerging-Market Electrification
  • Retrofit and Replacement Cycles in Mature Economies

Air Circuit Breaker Market Summary

The global Air Circuit Breaker Market stood at an estimated USD 4.18 billion in 2025 and is projected to reach USD 7.62 billion by 2035, expanding at a CAGR of 6.2% during the 2026–2035 forecast window. This growth trajectory reflects accelerating investment in low-voltage switchgear upgrades across industrial and commercial facilities worldwide, driven by tightening electrical safety codes and aggressive grid modernization programs. Governments from the U.S. Department of Energy to India's Bureau of Energy Efficiency have earmarked over USD 28 billion collectively for power distribution infrastructure overhauls through 2030, and air circuit breakers sit at the core of every new or retrofitted switchboard rated above 800 A [3].

The market for air circuit breakers is changing due to a major technological shift. Once the industry norm, microprocessor-based electronic trip unit platforms with customizable protection curves, energy metering, and communication bus connectivity are gradually replacing legacy thermal-magnetic trip units. More than 60% of new ACB LV 4000A-class frames are currently shipped by major OEMs with Modbus TCP or IEC 61850 interfaces, allowing facility operators to use zone selective interlock schemes that can reduce fault-clearing times by up to 50% [4]. Recent updates to the IEC 61439 and UL 1066 standards have strengthened the criteria for arc-flash performance, forcing end users to replace outdated drawout air circuit breaker assemblies with more contemporary fixed or withdrawable devices that include integrated motor protection release capabilities [5].

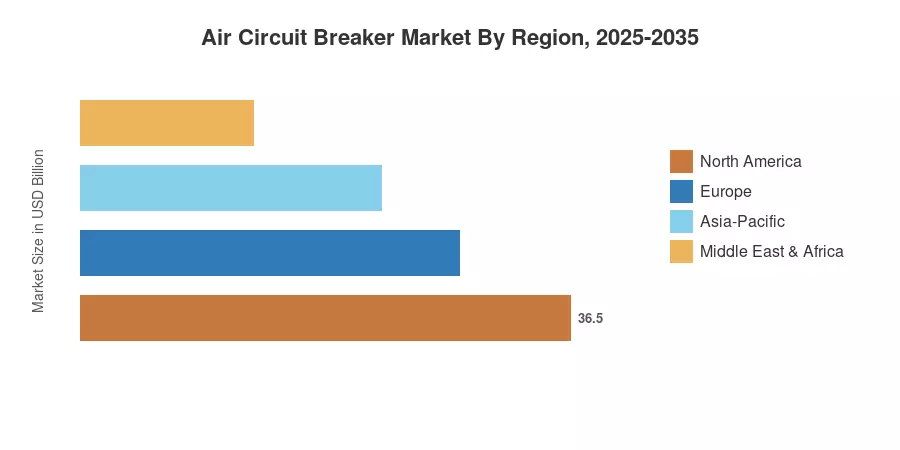
With a revenue share of over 42%, Asia-Pacific dominates the air circuit breaker market thanks to significant industrial developments in China and India. At 7.4%, which is significantly higher than the global average, the area also has the quickest CAGR. Data center construction and NEC code-cycle upgrades are the main drivers of North America's roughly 24% share, while EU energy-efficiency rules drive Europe's roughly 22% share. Demand for 3-pole 4-pole setups is predicted to treble current installation volumes in emerging nations by 2035


Key Report Takeaways

• By Technology / Type

  • Drawout air circuit breaker frames account for the largest type share at roughly 58% of global revenue, preferred for critical power distribution infrastructure where maintenance downtime must be minimized
  • Electronic trip unit adoption is growing at a CAGR of 7.8%, the fastest among protection-technology sub-segments, as digital communication and zone selective interlock capabilities become standard specifications
  • Fixed-mount ACBs hold approximately USD 1.75 billion in 2025 revenue, favored in cost-sensitive commercial and light-industrial installations

• By Application / Sector

  • The industrial sector leads the Air Circuit Breaker Market with a 45% share, driven by the expansion of manufacturing, petrochemical, and mining facilities requiring motor protection release functions
  • Data centers and commercial buildings represent the fastest-growing application vertical at a 7.1% CAGR, as hyperscale operators specify ACB LV 4000A frames for main distribution boards

• By Geography

  • Asia-Pacific dominates the Air Circuit Breaker Market at 42% share, with China alone contributing USD 0.94 billion in 2025
  • North America records a CAGR of 5.9%, supported by the U.S. Infrastructure Investment and Jobs Act allocations for grid resilience
  • Europe holds approximately 22% share, led by Germany and the U.K. under revised EN 61439 mandates

Market Size and Forecast (2021–2035)

Market sizing relies on a bottom-up methodology combining OEM shipment data, distributor sell-through figures, and national import-export databases for low-voltage switchgear assemblies. The Air Circuit Breaker Market forecast applies regression analysis against leading indicators including industrial capex indices, commercial construction permits, and utility grid investment plans published by the IEA and World Bank.
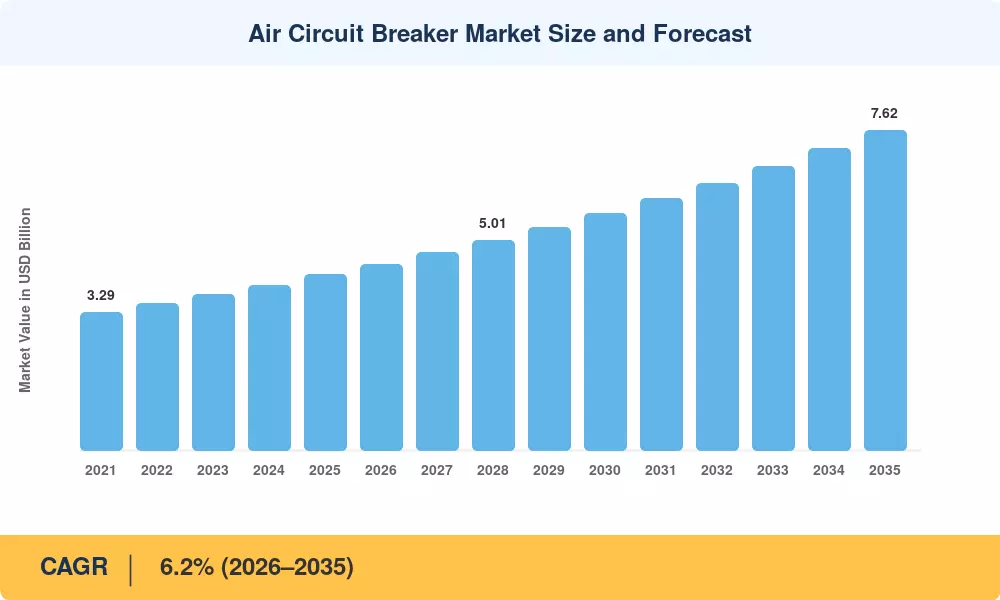
Air Circuit Breaker Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Industrial capacity expansion in APAC ~22% Asia-Pacific Long-term (≥4 yr)
Data-center power density escalation ~18% Global Medium-term (2–4 yr)
Electrical safety code tightening (NEC, IEC) ~16% North America, Europe Short-term (≤2 yr)
Grid modernization & low-voltage switchgear upgrades ~14% Global Long-term (≥4 yr)
Electronic trip unit & IoT integration demand ~12% Global Medium-term (2–4 yr)
Renewable energy integration (solar, wind farms) ~10% Europe, APAC Long-term (≥4 yr)
Electrification of transport infrastructure ~8% Europe, North America Medium-term (2–4 yr)


Industrial Capacity Expansion in Asia-Pacific

China's 14th Five-Year Plan earmarked over RMB 1.2 trillion (≈USD 168 billion) for advanced manufacturing infrastructure, while India's Production Linked Incentive scheme has attracted USD 32 billion in committed industrial investment across semiconductors, EV batteries, and pharmaceuticals [8]. Every new factory floor above 500 kVA demand requires main and tie-breaker ACBs rated 1600 A–4000 A. This structural expansion sustains demand for drawout air circuit breaker assemblies and motor protection release functions across the region, making industrial capex the single largest driver of the Air Circuit Breaker Market through 2035.

Data-Center Power Density Escalation

Global data-center electricity consumption is projected to reach 1,050 TWh by 2030, per the IEA . Rack densities above 30 kW now demand ACB LV 4000A-rated main distribution switchboards with electronic trip unit protection and zone selective interlock coordination to limit arc-flash incident energy below 1.2 cal/cm². North American hyperscale operators alone are expected to invest USD 150 billion in new facility construction between 2025 and 2030 .

Electrical Safety Code Tightening

The 2026 NEC code cycle introduces expanded arc-energy reduction requirements under Article 240.87, mandating zone selective interlock or active arc-flash mitigation on all breakers above 1200 A in commercial occupancies [5]. Parallel revisions to IEC 61439-2 Edition 3 require type-tested assemblies to demonstrate enhanced short-circuit withstand at higher prospective fault levels. These regulatory shifts compel facility owners to replace legacy thermal-magnetic ACBs with modern electronic trip unit frames—accelerating replacement cycles in the Air Circuit Breaker Market.

Grid Modernization Programs

The U.S. DOE Grid Resilience and Innovation Partnerships (GRIP) program has allocated USD 10.5 billion toward low-voltage switchgear and distribution upgrades across 58 projects . Similar programs exist in the EU (TEN-E regulation) and India (RDSS scheme, USD 40 billion). These initiatives create a direct pipeline for power distribution infrastructure projects specifying 3-pole 4-pole air circuit breakers in utility substations and municipal switchboards.

Restraints Impact Analysis

Restraint ~% Negative Impact Geographic Relevance Impact Timeline
High upfront cost vs. MCCBs ~−1.4% Price-sensitive emerging markets Short-term (≤2 yr)
Lengthy procurement & lead times ~−0.9% Global Short-term (≤2 yr)
Skilled labor shortage for installation ~−0.7% North America, Europe Medium-term (2–4 yr)
Competition from solid-state breakers ~−0.5% North America, Europe Long-term (≥4 yr)
Commodity price volatility (copper, steel) ~−0.4% Global Medium-term (2–4 yr)


Cost Differential with MCCBs

A drawout air circuit breaker frame rated at 1600 A typically costs 4–6× more than an equivalent MCCB, creating a significant barrier in price-sensitive verticals such as residential high-rises and small commercial buildings. In markets like Southeast Asia and Sub-Saharan Africa, MCCBs dominate installations below 2000 A. This cost gap limits the addressable opportunity for the Air Circuit Breaker Market in lower-tier construction segments, though total cost of ownership arguments (maintenance, selectivity, longevity) partially offset the premium.

Solid-State Circuit Breaker Competition

Silicon-carbide-based solid-state breakers can interrupt fault currents in under 1 millisecond—roughly 30× faster than conventional ACBs [15]. While still prohibitively expensive for most applications (USD 8,000–15,000 per pole for LV ratings), defense and aerospace programs are funding rapid development. Eaton, ABB, and Siemens each have active R&D programs targeting commercial solid-state LV breakers by 2030, which could erode the high-end segment of the Air Circuit Breaker Market.

Skilled Labor Shortage

The U.S. Bureau of Labor Statistics projects a 6% shortfall in qualified electricians through 2032 [14]. Commissioning a drawout air circuit breaker panel with electronic trip unit programming and zone selective interlock configuration requires specialized training that many installation firms lack. This bottleneck can delay project timelines by 4–8 weeks, dampening near-term replacement demand in North America and Western Europe.

Air Circuit Breaker Market Opportunities

Smart-Building Integration and Energy Management

Building energy management systems (BEMS) are expected to grow at 12% CAGR through 2032. ACBs equipped with electronic trip unit modules and embedded power-quality metering can serve as edge data nodes, feeding real-time load and harmonic data into BEMS platforms. OEMs that offer open-protocol ACB LV 4000A frames with BACnet or MQTT connectivity can capture premium pricing of 15–20% above standard units

Emerging-Market Electrification

Sub-Saharan Africa's electrification rate reached 51% in 2024, leaving approximately 590 million people without grid access [17]. Large-scale grid extension and mini-grid programs funded by the World Bank (USD 5.4 billion committed through 2030) will require switchgear including low-voltage switchgear assemblies with air circuit breakers for distribution substations. The Air Circuit Breaker Market stands to benefit from first-time infrastructure builds in Nigeria, Kenya, Tanzania, and Ethiopia

Retrofit and Replacement Cycles in Mature Economies

Over 35% of installed ACB inventory in North America and Europe is older than 15 years, approaching end-of-life [18]. Manufacturers like ABB and Schneider Electric offer drop-in retrofit kits that allow operators to replace legacy trip units with modern electronic trip unit modules without changing the switchboard enclosure. This retrofit opportunity represents an estimated USD 1.1 billion addressable segment through 2030 in the Air Circuit Breaker Market

Predictive Maintenance and Data Monetization

Cloud-connected ACBs with embedded current, temperature, and contact-wear sensors can enable predictive maintenance algorithms that reduce unplanned downtime by 25–30% [4]. OEMs can monetize this capability through subscription-based digital service models—charging USD 200–500 per breaker per year for analytics dashboards and automated maintenance scheduling. This recurring-revenue model represents a new business layer for the Air Circuit Breaker Market

EV Charging Infrastructure

The global EV charging station installed base is projected to exceed 30 million units by 2030 . High-power DC fast-charging stations (150–350 kW) require upstream ACB protection rated at 1600 A or above with motor protection release and 3-pole 4-pole configurations. Each charging hub typically specifies 2–4 ACB frames, creating a growing incremental demand channel for power distribution infrastructure projects

Air Circuit Breaker Market Future Outlook

AI-Driven Predictive Protection

By 2030, an estimated 40% of new ACBs above 1600 A will ship with embedded AI inference chips capable of detecting incipient faults through waveform anomaly recognition [4]. These electronic trip unit systems will learn facility-specific load signatures and automatically adjust protection curves—moving beyond static zone selective interlock coordination toward adaptive, self-optimizing protection networks. The IEA projects that AI-enabled electrical infrastructure could reduce industrial downtime costs by USD 42 billion annually by 2032 .

Electrification Supercycle

Global electricity demand is forecast to grow 35% between 2025 and 2035, driven by EV adoption, heat-pump deployment, and industrial electrification . Every megawatt of incremental load requires upstream protection, and the Air Circuit Breaker Market is positioned to capture a growing share as facilities upsize from MCCBs to ACBs to handle higher prospective fault currents. Low-voltage switchgear OEMs are already designing 6300 A ACB frames to accommodate rising power densities.

Sustainability and Circular Design

ESG reporting frameworks such as the EU Corporate Sustainability Reporting Directive (CSRD) now require companies to disclose the carbon footprint of capital equipment including power distribution infrastructure [11]. ACB manufacturers are responding with eco-designed frames using recycled copper and aluminum, SF₆-free arc chambers, and modular construction that extends product life to 30+ years. Schneider Electric's "Green Premium" ACB line and ABB's circularity program for motor protection release modules exemplify this shift.

Platform Economics and Digital Services

The Air Circuit Breaker Market is evolving from a hardware-centric model toward platform economics. OEMs are bundling ACB hardware with cloud-based energy dashboards, firmware-over-the-air updates, and subscription analytics. Siemens' "Electrical Products as a Service" pilot and Eaton's Brightlayer platform already monetize connected low-voltage switchgear data. By 2035, digital service revenues could represent 8–12% of total ACB market value, creating a new competitive dimension beyond traditional 3-pole 4-pole hardware sales [4].

Regional Market Share Analysis

Region Key Metric Primary Investment Themes
Asia-Pacific ~42% share Industrial expansion; smart-grid rollout; urbanization
North America CAGR 5.9% Data centers; NEC compliance; grid resilience
Europe ~22% share Energy efficiency directives; EV infrastructure
South America USD 0.26 B (2025) Mining electrification; grid extension
Middle East & Africa CAGR 6.8% Mega-projects; electrification programs
Total USD 4.18 B (2025) —

The Air Circuit Breaker Market exhibits pronounced regional variation driven by differing industrial maturity, code environments, and infrastructure investment timelines. Asia-Pacific's dominance reflects the sheer volume of new low-voltage switchgear installations across China and India, while mature regions grow primarily through retrofit and compliance-driven replacement.


Asia-Pacific

Country Key Metric Key Driver
China USD 0.94 B (2025) Manufacturing capex; data-center build-out
India CAGR 8.1% Smart Grid Mission; PLI scheme
Japan ~9% of regional share Seismic retrofit standards
South Korea CAGR 5.6% Semiconductor fab construction
Rest of APAC ~14% of regional share ASEAN industrialization


China remains the single largest national market for air circuit breakers, driven by State Grid Corporation's annual switchgear procurement exceeding USD 4 billion and a manufacturing sector that added 1.2 million new factory registrations in 2024 alone. India is the fastest-growing country-level opportunity in the Air Circuit Breaker Market, with the Revamped Distribution Sector Scheme (RDSS) targeting smart-metering and low-voltage switchgear deployment across 250 million consumer endpoints by 2027 . Japan's post-earthquake building code revisions mandate upgraded drawout air circuit breaker panels in critical facilities, sustaining steady replacement demand.

North America

Country Key Metric Key Driver
United States ~82% of regional share Data centers; NEC 2026; GRIP program
Canada CAGR 5.4% Mining electrification; CEC updates
Mexico USD 0.07 B (2025) Nearshoring manufacturing


The United States accounts for the vast majority of North American demand, with the Air Circuit Breaker Market benefiting from a convergence of data-center construction, NEC Article 240.87 zone selective interlock mandates, and DOE grid-resilience funding. Hyperscale operators in Virginia, Texas, and Oregon are specifying ACB LV 4000A frames with electronic trip unit protection as standard for new builds. Canada's growing critical-minerals mining sector in Ontario and Quebec drives demand for motor protection release ACBs rated for harsh environments [14].

Europe

Country Key Metric Key Driver
Germany ~28% of regional share Industrie 4.0; Energiewende
United Kingdom CAGR 5.7% BS EN 61439 adoption; data centers
France USD 0.15 B (2025) Nuclear facility upgrades
Rest of Europe ~32% of regional share EU Green Deal compliance


Germany's Industrie 4.0 initiative continues to drive demand for intelligent low-voltage switchgear with communication-enabled electronic trip unit ACBs. The U.K. has emerged as Europe's fastest-growing data-center hub outside the Nordics, creating incremental demand for 3-pole 4-pole drawout air circuit breaker assemblies in London's Docklands and Slough corridors. EU Directive 2023/1791 on energy efficiency requires large enterprises to audit and upgrade electrical distribution systems, directly benefiting the Air Circuit Breaker Market [11].

South America

Country Key Metric Key Driver
Brazil ~62% of regional share Mining; grid expansion
Chile CAGR 6.3% Copper/lithium mining electrification
Rest of South America USD 0.04 B (2025) Urban infrastructure


Brazil's mining and oil & gas sectors drive the majority of South American ACB demand, with Petrobras and Vale collectively investing over USD 18 billion in facility upgrades through 2028. Chile's booming lithium extraction industry requires ruggedized power distribution infrastructure with ACBs rated for high-altitude, high-dust environments [17].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia ~34% of regional share NEOM; Vision 2030 mega-projects
UAE CAGR 7.2% Expo legacy; data centers
Nigeria USD 0.03 B (2025) Grid electrification
Rest of MEA ~38% of regional share Infrastructure development


Saudi Arabia's NEOM, Red Sea, and Qiddiya giga-projects are specifying state-of-the-art low-voltage switchgear assemblies that include drawout air circuit breaker panels with full electronic trip unit protection and zone selective interlock coordination. The broader MEA region benefits from World Bank and AfDB electrification lending, creating first-time demand for ACBs in countries transitioning from informal to formal grid infrastructure. The Air Circuit Breaker Market in MEA is expected to nearly double by 2035 [17].

Air Circuit Breaker Market By Region, 2025-2035

Air Circuit Breaker Market Segmentation

By Type (Mounting Configuration)

Segment Key Metric Primary Demand Driver
Drawout ~58% share Critical facilities requiring zero-downtime maintenance
Fixed CAGR 5.8% Cost-sensitive commercial installations


The drawout air circuit breaker segment dominates the Air Circuit Breaker Market because it allows operators to isolate and service breakers without de-energizing the entire switchboard—a critical requirement in hospitals, data centers, and continuous-process manufacturing. Fixed-mount ACBs are gaining traction in commercial buildings and light-industrial applications where lower upfront cost outweighs maintenance flexibility. The electronic trip unit is now standard across both configurations, but drawout frames command a 25–35% price premium due to the precision cradle mechanism and additional interlocking required.

By Pole Configuration

Segment Key Metric Primary Demand Driver
3-Pole USD 2.59 B (2025) Three-phase industrial and commercial mains
4-Pole CAGR 7.0% TN-S systems requiring switched neutral; data centers


Three-pole ACBs account for the bulk of installations across standard three-phase power distribution infrastructure worldwide. The 3-pole 4-pole split is shifting gradually, however, as international codes increasingly require switched neutral protection in TN-S earthing systems—particularly in data centers, healthcare facilities, and installations with multiple supply sources. Four-pole configurations with motor protection release functionality are also specified in marine and offshore applications where neutral integrity is safety-critical [5].

By End-User Application

Segment Key Metric Primary Demand Driver
Industrial ~45% share Manufacturing, mining, oil & gas
Commercial CAGR 7.1% Data centers, hospitals, high-rises
Utilities USD 0.63 B (2025) Substation and distribution upgrades
Others (Marine, Transport) ~10% share Specialized code requirements


Industrial end users represent the largest vertical in the Air Circuit Breaker Market, specifying ACB LV 4000A frames with comprehensive motor protection release and zone selective interlock schemes for complex motor control centers and process switchboards. Commercial applications are growing fastest, propelled by the global data-center construction wave and stricter building codes mandating electronic trip unit protection above 1200 A. Utility-sector demand centers on low-voltage switchgear upgrades within distribution substations and renewable energy collection points .

Competitive Benchmarking

The Air Circuit Breaker Market is moderately concentrated, with the top five players holding an estimated 55–62% combined revenue share. The Herfindahl-Hirschman Index (HHI) is approximately 1,100–1,300, indicating a moderately competitive structure. ABB, Schneider Electric, Siemens, Eaton, and Mitsubishi Electric anchor the upper tier, while regional specialists like C&S Electric, CHINT, and Hyundai Electric compete aggressively on price in Asia-Pacific and MEA.

Company Est. Revenue Share Range Key Offerings for Air Circuit Breaker Market Strategic Positioning
ABB ~12–15% Emax 2 series; TruONE dual-rated ACB Premium digital integration; global footprint
Schneider Electric ~11–14% MasterPact MTZ; EvoPact Green Premium eco-design; BEMS connectivity
Siemens ~10–13% SENTRON 3WL; 3WT series Industrie 4.0 ecosystem; cloud analytics
Eaton ~8–11% Magnum DS; Power Defense North American channel strength; arc-flash focus
Mitsubishi Electric ~6–8% AE-SW series Asian manufacturing leadership; compact design
Legrand ~3–5% DMX³ series European mid-market; modular systems
CHINT ~3–5% NA1 series Price-competitive APAC champion
C&S Electric (Siemens) ~2–4% ACB range under Siemens brand Indian market penetration
Hyundai Electric ~2–3% UAN series Korean industrial base; export growth
LS Electric ~2–3% Susol series Smart-factory integration


Recent News & Developments

  • ABB (March 2025): Launched the Emax 2 with embedded edge-AI fault prediction, enabling adaptive zone selective interlock without external controllers. The product targets data-center and industrial power distribution infrastructure [19].
  • Schneider Electric (January 2025): Announced the MasterPact MTZ "Green Premium" line using 97% recyclable materials and an electronic trip unit with native MQTT connectivity for smart-building integration [20].
  • Siemens (October 2024): Released firmware update for SENTRON 3WL enabling IEC 61850 GOOSE messaging for real-time zone selective interlock coordination across utility substations [21].
  • Eaton (July 2024): Acquired Exertherm thermal monitoring technology and integrated it into the Magnum DS drawout air circuit breaker platform for predictive contact-wear analytics .
  • IEC (June 2024): Published IEC 61439-2 Edition 3, tightening type-test requirements for low-voltage switchgear assemblies and raising prospective fault-current ratings for ACB-equipped panels [5].
  • Mitsubishi Electric (April 2024): Expanded Changshu, China, manufacturing plant capacity by 30% to meet rising ACB LV 4000A demand across Asia-Pacific [23].
  • India Ministry of Power (September 2023): Approved RDSS Phase II, allocating USD 8.2 billion for smart distribution infrastructure including motor protection release ACB panels across 15 states .
  • CHINT (March 2023): Launched NA1 series with built-in electronic trip unit and Modbus RTU at 20% lower price point than incumbent European brands, intensifying price competition in the Air Circuit Breaker Market .


Air Circuit Breaker Market Report Scope

Parameter Detail
Market Scope Global Air Circuit Breaker Market — hardware, electronic trip units, accessories, and services
Study Period 2021–2035
CAGR 6.2% (2026–2035)
Base Year Market Size USD 4.18 Billion (2025)
Forecast Endpoint USD 7.62 Billion (2035)
Fastest Growing Segment Electronic trip unit ACBs (7.8% CAGR); Asia-Pacific by region (7.4% CAGR)
Companies Profiled ABB, Schneider Electric, Siemens, Eaton, Mitsubishi Electric, Legrand, CHINT, C&S Electric, Hyundai Electric, LS Electric
Valuation Currency USD (constant 2025 dollars)

FAQs

How does zone selective interlock reduce arc-flash hazard in facilities using air circuit breakers?
Zone selective interlock enables upstream and downstream ACBs to communicate restraint signals during a fault, allowing only the breaker nearest the fault to trip instantaneously while upstream units delay. This coordination cuts arc-flash incident energy by 50–70% compared to traditional time-graded selectivity, significantly reducing burn injury risk [5].
What factors should procurement teams evaluate when choosing between drawout and fixed-mount ACBs?
Drawout air circuit breaker frames cost 25–35% more but allow breaker replacement without de-energizing the bus, reducing maintenance downtime to under 30 minutes. Fixed-mount units suit installations where scheduled shutdowns are acceptable and budget constraints are tight.
Can legacy thermal-magnetic ACBs be retrofitted with electronic trip units instead of full replacement?
Most major OEMs offer drop-in retrofit kits that replace the trip unit while reusing the existing cradle and enclosure, typically at 40–50% of full replacement cost. Compatibility depends on frame vintage; units older than 20 years may require complete switchboard replacement [18].
How do 4-pole ACBs differ functionally from 3-pole units beyond the added neutral pole?
The fourth pole provides switched neutral protection essential in TN-S earthing systems, preventing neutral-to-earth faults and enabling safe source changeover in dual-supply configurations. Data centers and hospitals increasingly mandate 3-pole 4-pole specifications for this reason [5].
What cybersecurity risks exist for IoT-connected air circuit breakers with electronic trip units?
Networked ACBs using Modbus TCP or IEC 61850 expose potential attack surfaces for unauthorized trip commands or protection-setting manipulation. IEC 62351 provides encryption and authentication guidelines, but adoption remains below 30% industry-wide as of 2024 [4].
How does the Air Circuit Breaker Market opportunity differ for OEMs versus aftermarket service providers?
OEM revenue concentrates on new construction and major retrofits with 5–8 year sales cycles, while aftermarket providers earn recurring revenue from spare parts, trip-unit upgrades, and predictive-maintenance contracts. Aftermarket margins typically run 35–45% versus 18–22% for hardware .
What role do air circuit breakers play in renewable energy plant balance-of-system design?
Solar and wind farms above 10 MW use ACBs at the low-voltage collection bus and inverter output stages, where prospective fault currents exceed MCCB interrupting capacity. Each 50 MW solar plant typically requires 6–10 drawout air circuit breaker frames rated 2000–4000 A .    
Author
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, technical standards, industry publications, and authoritative energy & electrical organizations. Key sources included the US Department of Energy (DOE), Federal Energy Regulatory Commission (FERC), National Electrical Manufacturers Association (NEMA), Institute of Electrical and Electronics Engineers (IEEE), International Electrotechnical Commission (IEC), European Committee for Electrotechnical Standardization (CENELEC), International Energy Agency (IEA), US Energy Information Administration (EIA), International Renewable Energy Agency (IRENA), World Energy Council (WEC), China Electricity Council (CEC), Japan Electrical Manufacturers' Association (JEMA), VDW German Electrical and Electronic Manufacturers' Association, India Energy Storage Alliance (IESA), and national utility regulatory commission reports from key markets. These sources were used to collect grid infrastructure statistics, regulatory compliance data, safety certification studies, electrification trends, and competitive landscape analysis for standard air circuit breakers, intelligent air circuit breakers, and hydraulic magnetic air circuit breakers across low, medium, and high voltage ratings.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. CEOs, VPs of Product Development, R&D chiefs, and commercial directors from air circuit breaker manufacturers and OEMs comprised supply-side sources. The demand-side sources consists of chief electrical engineers, procurement managers, grid infrastructure planners, and maintenance leaders from utilities, manufacturing facilities, construction companies, and transportation authorities. Market segmentation was verified, product development timelines were confirmed, and insights regarding the adoption patterns of smart grid technologies, pricing strategies, and regulatory compliance dynamics were obtained through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (32%), Others (40%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and installation volume analysis. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, Middle East & Africa, and Latin America

Product mapping across standard air circuit breakers, intelligent air circuit breakers, and hydraulic magnetic air circuit breakers by voltage rating (low, medium, high)

Analysis of reported and modeled annual revenues specific to air circuit breaker portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (installation volume × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for power generation, industrial, commercial, residential, utilities, manufacturing, construction, and transportation end-use segments

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.



















