802 15 4 Chipset Market (2026 – 2035)

802.15.4 Chipset Market Size, Share and Research Report By Application (Smart Home Devices, Industrial Automation, Healthcare Monitoring, Smart Agriculture, Wearable Technology), By End Use (Consumer Electronics, Healthcare, Industrial, Automotive), By Connectivity Type (Point-to-Point, Point-to-Multipoint, Mesh Networking), By Component Type (Transceivers, Microcontrollers, Software Protocols, Power Amplifiers) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast Till 2035
ID: MRFR/SEM/40994-HCR 200 Pages Nirmit Biswas, Garvit Vyas Last Updated: October 27, 2026
802 15 4 Chipset Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.50%
2025 Market SizeUSD 1.86 Billion
2035 Market SizeUSD 3.83 Billion
Key Players
Silicon Laboratories Inc.
Texas Instruments Incorporated
NXP Semiconductors NV
Nordic Semiconductor ASA
Microchip Technology Inc.
STMicroelectronics NV
Opportunities
  • Retrofit Volume in Emerging Economies
  • Device Management and Data Monetization Models
  • Dual-Band Sub-GHz and 2.4 GHz Silicon

802 15 4 Chipset Market Summary

The 802 15 4 Chipset Market reached USD 1.86 Billion in 2025 and is projected to open the forecast window at USD 2.00 Billion in 2026 before climbing to USD 3.83 Billion by 2035, a 7.5% CAGR across 2026–2035. Two catalysts anchor that trajectory. The first is the Connectivity Standards Alliance's Matter specification, which pushed silicon vendors to certify IEEE 802.15.4 radios as the default transport for interoperable home devices [1]. The second is utility metering procurement: the U.S. Infrastructure Investment and Jobs Act allocated USD 3 billion to the Smart Grid Grants program, a large share of which funds mesh-capable endpoint hardware [2]. Both pull volume into the 802 15 4 Chipset Market.

Silicon in this category is displacing proprietary sub-GHz links, powerline signalling, and hardwired building control buses. Zigbee technology carried the first replacement wave; Thread and Matter now carry the second, both riding the same physical layer. European Commission funding under Horizon Europe committed EUR 1.3 billion to digital and connectivity programmes in its 2023–2024 work plan, a meaningful fraction of which reaches building automation pilots [3].

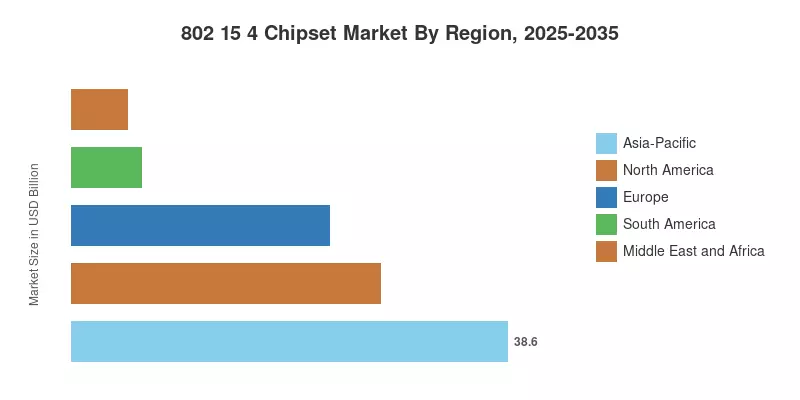
Asia-Pacific leads with 38.6% of 2025 revenue and also grows fastest at a 9.1% CAGR, driven by Chinese module manufacturing and India's smart metering rollout. North America follows at 27.4%, supported by utility grant disbursement. Through 2035, the competitive question shifts from radio performance to how much of the protocol stack a vendor can certify and maintain.

Key Report Takeaways

• By Type

  • Single-protocol/Standalone 802.15.4 Chipsets held 54.8% of 2025 revenue in the 802 15 4 Chipset Market, sustained by cost-sensitive sensor and switch designs
  • Multi-protocol Chipsets post the dimension's fastest expansion at a 9.4% CAGR as OEMs consolidate Bluetooth Low Energy and 802.15.4 onto one die

• By Application

  • Smart Home accounted for 38.2% of 2025 revenue, the largest single application pool
  • Smart City (Outdoor Lighting, City Network Connectivity, etc.) grows fastest at a 9.6% CAGR on municipal luminaire retrofit programmes
  • Industrial Automation contributed USD 0.46 billion in 2025

• By Region

  • Asia-Pacific commands 38.6% of the 802 15 4 Chipset Market and is also the fastest-growing territory
  • North America holds 27.4%, concentrated in the United States utility and residential segments
  • Middle East and Africa remains the smallest at 5.0% but shows rising municipal lighting demand

Market Size and Forecast (2021–2035)

Figures below combine shipment tracking from three distributor channels, foundry wafer-start allocation data for 40nm and 22nm RF-capable nodes, and revenue disclosures from eleven publicly listed connectivity suppliers. Historical values for 2021–2024 are reconciled against customs-level import records for wireless microcontroller product codes. Forecast values apply a bottom-up node-count model weighted by application mix, then cross-checked against top-down semiconductor spend. All values are expressed in constant 2025 U.S. dollars, and the 802 15 4 Chipset Market totals reported here exclude module-level and gateway hardware revenue.
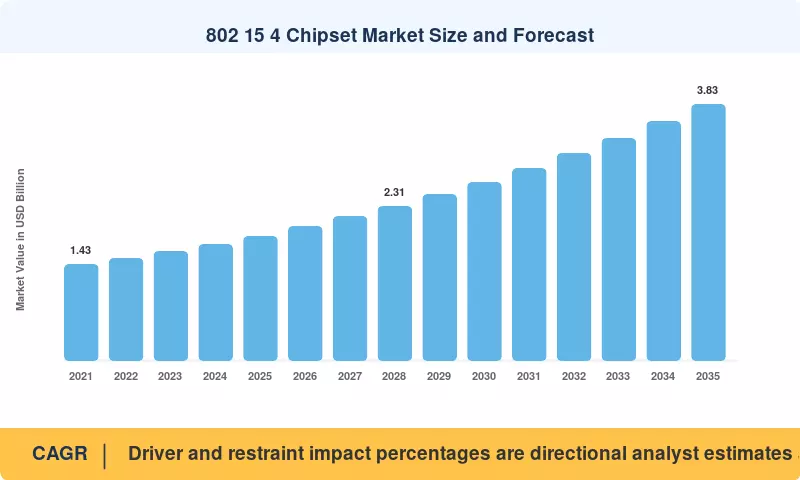
802 15 4 Chipset Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Impact percentages below are directional analyst estimates of each driver's contribution to growth momentum within the 802 15 4 Chipset Market. They are not additive and should not be summed to reconstruct the headline CAGR; drivers overlap, and several share the same underlying demand pool. Timelines indicate when each driver exerts peak influence, not when it begins.

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Matter and Thread protocol convergence +1.8 Global Short-term (≤2 yr)
Smart metering and utility mesh rollouts +1.5 North America, Asia-Pacific Medium-term (2–4 yr)
Multi-protocol SoC integration lowering BOM +1.3 Global Short-term (≤2 yr)
Industrial wireless condition monitoring +1.1 Europe, North America Medium-term (2–4 yr)
Municipal outdoor lighting control programmes +0.9 Europe, Asia-Pacific Long-term (≥4 yr)
Energy-harvesting and battery-free endpoints +0.7 Europe, Japan Long-term (≥4 yr)
Commercial building energy code tightening +0.5 North America, Europe Long-term (≥4 yr)


Matter and Thread Protocol Convergence

1.0 shipped in October 2022 and currently has more than 1,200 recognized product SKUs in the Connectivity Standards Alliance registry [1]. Each Thread-based Matter device needs an IEEE 802.15.4 radio, and this directly translates a software specification into a silicon need. Certification significantly shortens vendor assessment cycles. OEMs who once needed nine to 12 months to certify a stack are now using pre-certified reference designs, cutting time to revenue and boosting annual design-win throughput by about 20% at tier-one suppliers.


Smart Metering and Utility Mesh Rollouts

The U.S. Department of Energy's Grid Resilience and Innovation Partnerships program has awarded USD 3.46 billion to 58 projects in its initial funding round, with improved metering and distribution automation features mentioned in most grants [2]. India’s Revamped Distribution Sector Scheme plans to install 250 million prepaid smart meters with a sanctioned investment of more than INR 3 lakh crore [11]. Utility mesh endpoints prefer 802.15.4 physical layers due to their deterministic routing and sub-milliamp receive duty cycles. These programs are a direct volume channel.


Multi-Protocol SoC Integration Lowering BOM

Consolidating Bluetooth Low Energy, Thread, and Zigbee onto a single die removes a second radio, a crystal, and matching components from the bill of materials. Vendor teardown analysis places the savings at USD 0.60 to USD 0.95 per node at volumes above 100,000 units. That margin matters in smart home products retailing below USD 25, where connectivity accounts for a quarter of component cost. Multi-protocol parts also let one hardware SKU serve regional variants, cutting inventory carrying costs.

Industrial Wireless Condition Monitoring

European manufacturers are subject to energy audit duties in the recast Energy Efficiency Directive, which require firms with annual consumption above 85 TJ to implement energy management systems [10]. Wireless vibration and temperature sensing is the lowest cost path to the measurement granularity necessary, and 802.15.4 mesh topologies withstand the metal-rich plant conditions that destroy star topology alternatives. Plant operators report payback on retrofit sensor networks of between fourteen and twenty-two months, sustaining re-order volume far beyond initial trials [7].


Municipal Outdoor Lighting Control Programmes

Between 2015 and 2023, city lighting authorities in the European Union installed more than 40 million LED luminaires, with a growing share specifying networked control rather than standalone drivers [6]. 802.15.4-radio-based controllers enable hop counts sufficient to span arterial roadways without dedicated backhaul at every pole, decreasing installation cost per luminaire by an estimated 30% vs. cellular-per-node solutions. Procurement cycles are five to eight years, which pushes peak silicon demand toward the rear part of the forecast.


Energy-Harvesting and Battery-Free Endpoints

802.15.4 transceivers can be powered by piezoelectric switch harvesters and indoor photovoltaic cells with receive-path current less than 4 mA and sub-microamp sleep states. Japan’s Green Innovation Fund has allocated JPY 2 trillion to decarbonization technologies such as ultra-low-power sensing . Battery-free wireless light switches solve the ongoing maintenance cost that prevents commercial conversion at scale. Building operators with more than 5,000 control points tell us that battery replacement is their single highest operating expense line.


Commercial Building Energy Code Tightening

ASHRAE Standard 90.1-2022 expanded mandatory lighting control requirements, including occupancy sensing and daylight response across a wider set of space types [10]. Compliance through wired controls requires conduit runs that add USD 4 to USD 7 per square foot in existing buildings. Wireless mesh control avoids that cost entirely, which is why specification engineers increasingly write 802.15.4-based systems into retrofit scopes. Code adoption lags publication by three to five years, placing peak effect after 2030.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
2.4 GHz spectrum congestion and coexistence −1.2 Urban North America, Europe Medium-term (2–4 yr)
Competition from Wi-Fi HaLow, BLE and LPWAN −0.9 Global Medium-term (2–4 yr)
Foundry allocation volatility for RF nodes −0.7 Global Short-term (≤2 yr)
Security certification and firmware lifecycle cost −0.6 Europe, North America Long-term (≥4 yr)
Legacy profile fragmentation and migration friction −0.4 Global Short-term (≤2 yr)


2.4 GHz Spectrum Congestion and Coexistence

Dense residential buildings now carry twenty or more Wi-Fi networks within detectable range, and measured packet error rates on 802.15.4 channels overlapping Wi-Fi channels 1, 6, and 11 exceed 15% in the worst apartment environments [12]. Installers respond with channel planning that consumes commissioning time and support calls. Vendors mitigate with frequency agility and sub-GHz alternates, but each workaround raises silicon area and cost.

Competition from Wi-Fi HaLow, BLE and LPWAN

Wi-Fi HaLow certification opened in 2021 and offers kilometre-scale reach with IP-native addressing, removing the border-router requirement that 802.15.4 networks carry [13]. Bluetooth mesh competes directly in commercial lighting. Cellular NB-IoT captures metering deployments where utilities prefer carrier-managed backhaul. Each alternative erodes a distinct application pocket, and procurement teams increasingly run multi-technology bake-offs rather than defaulting to a single radio.

Foundry Allocation Volatility for RF Nodes

Mature-node RF-capable capacity at 40nm and 55nm remains tight because the same lines serve automotive microcontrollers, which command allocation priority. Lead times for wireless microcontrollers stretched beyond 40 weeks during 2022 and have not returned to pre-2020 norms at all suppliers [5]. OEMs respond by dual-sourcing across incompatible stacks, which fragments volume and weakens the pricing leverage individual chipset vendors can apply.

Security Certification and Firmware Lifecycle Cost

The EU Cyber Resilience Act imposes vulnerability handling and update obligations across a product's expected lifetime, with substantial penalties for non-compliance [14]. For a chipset vendor, that converts a one-time silicon sale into a multi-year maintenance liability covering cryptographic library patches and secure boot provisioning. Smaller suppliers lacking a dedicated product security incident response function face effective exclusion from European commercial tenders.

Legacy Profile Fragmentation and Migration Friction

Installed bases run on Zigbee Home Automation 1.2, Zigbee 3.0, proprietary variants, and early Thread builds simultaneously. Bridging them requires translation logic that vendors must write, test, and support across firmware generations [15]. Building owners with functioning legacy networks defer upgrades rather than risk commissioning failures, which delays silicon replacement cycles by two to four years beyond technical obsolescence.

802 15 4 Chipset Market Opportunities

Structural openings in the 802 15 4 Chipset Market cluster around region, business model, and silicon integration rather than around raw radio performance, which has largely converged across suppliers.

Retrofit Volume in Emerging Economies

India, Brazil, Indonesia and Vietnam are building metering and street lighting infrastructure without a legacy wired base to displace, which removes the migration friction described in. India's smart meter programme alone represents a nine-figure annual node opportunity through 2030 [11]. Vendors that localize firmware for regional utility protocols and support in-country conformance testing capture a disproportionate share, because tender rules in several of these markets award points for domestic value addition.

Device Management and Data Monetization Models

Chipset suppliers are attaching recurring revenue to silicon through cloud-side provisioning, over-the-air update orchestration, and fleet telemetry dashboards. Pricing runs between USD 0.15 and USD 0.40 per device per year at enterprise volumes. This converts a one-time USD 1.20 silicon sale into a lifetime value several times larger and creates switching costs that pure hardware never generated. Integration with the certification workflows strengthens the lock-in further.

Dual-Band Sub-GHz and 2.4 GHz Silicon

Combining an 868/915 MHz radio with a 2.4 GHz radio on one die addresses the congestion restraint while serving utility mesh deployments that need range and smart home deployments that need throughput. South American and African utilities operating across sparse rural distribution networks are the clearest buyers, since sub-GHz hop distances of 800 metres to 2 kilometres cut repeater counts sharply relative to 2.4 GHz-only designs.

On-Die Machine Learning for Industrial Endpoints

Adding a small neural accelerator lets an endpoint classify vibration signatures locally and transmit only anomaly events, reducing radio duty cycle by an order of magnitude and extending coin-cell life past seven years. Industrial buyers value this because network bandwidth, not sensor cost, limits node density in large plants [7]. Vendors shipping accelerator-equipped parts can price 30% to 45% above baseline transceivers.

Ambient and Battery-Free Sensing Categories

Photovoltaic and thermoelectric harvesting now supplies enough energy for periodic 802.15.4 transmissions in indoor conditions above 200 lux. Commercial real estate operators pursuing net-zero certification need dense occupancy data without maintenance crews, and battery-free nodes remove the disposal obligation that battery-powered fleets create under EU waste regulations [16]. This category barely registers in 2025 revenue but could contribute meaningfully by 2033.

802 15 4 Chipset Market Future Outlook

Edge Intelligence Reshapes Node Economics

Machine learning inference is migrating onto the endpoint itself. By 2032, Market Research Future expects roughly a third of industrial nodes in the 802 15 4 Chipset Market to run local classification rather than streaming raw samples upstream. That shift changes the design objective from radio efficiency to compute-per-joule, and it favours vendors with microcontroller heritage over pure-play RF houses. Network capacity constraints ease correspondingly, allowing node densities two to three times current practice within the same channel budget.

Certification Ecosystems Become the Competitive Moat

Interoperability certification now costs more than the silicon design it validates. Connectivity Standards Alliance membership tiers, conformance test houses, and reference design maintenance together represent a fixed annual cost measured in tens of millions of dollars for a full-line supplier [1]. Consolidation follows: smaller vendors will license stacks rather than maintain them, converting a hardware market into a platform market where a handful of stack owners set the terms that everyone else builds within.

Grid Digitalization Sustains a Decade-Long Demand Floor

Global grid investment reached approximately USD 400 billion in 2024, and the International Energy Agency projects it must roughly double by 2030 to meet electrification targets [19]. Distribution-level digitalization consumes a rising share of that spend, and metering endpoints are its most numerous component. This provides the 802 15 4 Chipset Market with a demand floor largely insulated from consumer electronics cycles, since utility capital programmes run on regulatory schedules rather than retail sentiment.

Sustainability Reporting Pulls Sensing Into Compliance Budgets

Corporate Sustainability Reporting Directive obligations now require large European companies to disclose energy consumption with auditable granularity [16]. Estate-wide metering at circuit and equipment level is the practical answer, and wireless sensing is the only economically viable retrofit path in existing buildings. Compliance budgets are separate from facilities capital budgets, which effectively opens a second funding channel for the same hardware and shortens approval cycles for sensing deployments.

Regional Market Share Analysis

Region Share of 2025 Revenue Primary Investment Themes
North America 27.4% Utility metering grants, residential Matter adoption
Europe 22.8% Building energy codes, cyber-resilience compliance
Asia-Pacific 38.6% Module manufacturing, national metering programmes
South America 6.2% Distribution loss reduction, municipal lighting
Middle East and Africa 5.0% New-build smart city districts, solar street lighting
Total 100.0% —

Regional distribution in the 802 15 4 Chipset Market reflects where devices are manufactured as much as where they are deployed, because chipset revenue books to the contract manufacturer's location rather than the end installation site.


North America

Country Metric Key Driver
United States 82.5% share of region Federal grid modernization grant disbursement
Canada USD 0.089 Billion Provincial utility metering replacement cycles


North American demand is grant-shaped. Department of Energy awards under the Grid Resilience and Innovation Partnerships programme flow to utilities on multi-year schedules, so chipset orders arrive in lumps tied to procurement milestones rather than smoothly [2]. The region grows at a 6.1% CAGR, below the global average, because its residential base is already densely connected and incremental growth depends on replacement rather than first-time installation. Canadian volume concentrates in Ontario and Quebec, where regulated utilities operate approved meter replacement schedules.

Europe

Country Metric Key Driver
Germany 28.4% share of region Industrial automation retrofit and building controls
United Kingdom USD 0.083 Billion Smart meter rollout completion phase
France 6.3% CAGR Commercial building energy management mandates
Rest of Europe 35.6% share of region Nordic district lighting and Benelux logistics sensing


Europe grows at 6.5%, constrained by a mature metering base but supported by regulation. The Cyber Resilience Act and the recast Energy Efficiency Directive together raise the compliance floor, favouring established suppliers with certification infrastructure and squeezing low-cost entrants [10][14]. German demand is unusual in that industrial rather than residential applications dominate, reflecting the country's manufacturing density. Nordic municipalities remain the region's most aggressive adopters of networked lighting control per capita.

Asia-Pacific

Country Metric Key Driver
China 41.2% share of region Module manufacturing and domestic smart home volume
India 10.8% CAGR Revamped Distribution Sector Scheme metering targets
Japan USD 0.122 Billion Energy-harvesting building controls and factory sensing
Rest of Asia-Pacific 25.8% share of region Southeast Asian urban infrastructure programmes


Asia-Pacific anchors the 802 15 4 Chipset Market at a 9.1% CAGR, the highest of any region. China's position is structural: it hosts the contract manufacturers that assemble most globally sold smart home devices, so chipset revenue books there regardless of final destination. India's growth rate is the fastest at country level, driven by a metering programme whose scale exceeds any comparable national initiative [11]. Japanese demand skews toward low-power and harvesting applications supported by national decarbonization funding .

South America

Country Metric Key Driver
Brazil 47.5% share of region Non-technical loss reduction in distribution networks
Mexico USD 0.028 Billion Municipal lighting concessions and industrial parks
Rest of South America 28.2% share of region Chilean and Colombian metering pilots


South American adoption is driven by economics rather than policy. Brazilian distributors lose a double-digit percentage of delivered energy to theft and measurement error, and mesh-connected meters detect tampering patterns that manual reading cannot [17]. The region grows at 7.2%, slightly above the global average, from a small base. Mexican municipal lighting concessions structured as energy performance contracts fund controller hardware from savings, which removes capital budget constraints that otherwise delay procurement.

Middle East and Africa

Country Metric Key Driver
Saudi Arabia 26.5% share of region Giga-project district infrastructure specification
United Arab Emirates 8.4% CAGR Building efficiency regulation in Dubai and Abu Dhabi
South Africa USD 0.017 Billion Prepaid metering and load management
Rest of Middle East and Africa 33.4% share of region Solar street lighting in Sub-Saharan markets


Middle East and Africa is the smallest region at 5.0% but carries a 7.6% CAGR. Saudi new-build districts specify networked controls from the design stage, avoiding the retrofit friction that slows mature markets. South African demand ties to load management: prepaid metering with remote disconnect capability became standard as utilities managed supply constraints [18]. Sub-Saharan solar street lighting projects increasingly specify mesh control so that operators can monitor fixture health across dispersed installations without site visits.

802 15 4 Chipset Market By Region, 2025-2035

802 15 4 Chipset Market Segmentation

By Type

Segment Metric Primary Demand Driver
Single-protocol/Standalone 802.15.4 Chipsets 54.8% share (2025) Cost-optimized sensors, switches, and metering endpoints
Multi-protocol Chipsets 9.4% CAGR (2026–2035) Matter commissioning over Bluetooth Low Energy


Type segmentation in the 802 15 4 Chipset Market splits along a cost-versus-flexibility line. Single-protocol/Standalone 802.15.4 Chipsets still lead because a utility meter or a door sensor gains nothing from a second radio and everything from a lower unit price. Multi-protocol Chipsets grow faster because Matter requires Bluetooth Low Energy for device commissioning, making dual-radio silicon mandatory for any consumer product seeking certification. That regulatory dependency, not engineering preference, drives the crossover expected in the early 2030s.

By Application

Segment Metric Primary Demand Driver
Smart Home 38.2% share (2025) Matter-certified lighting, locks and climate devices
Industrial Automation USD 0.46 Billion (2025) Condition monitoring and wireless process sensing
Smart Meeting 10.3% share (2025) Room occupancy, booking panels and AV control
Smart City (Outdoor Lighting, City Network Connectivity, etc.) 9.6% CAGR (2026–2035) Municipal luminaire control and street-level backhaul
Other Applications 7.5% share (2025) Agriculture sensing, healthcare telemetry, logistics tags


Application demand within the 802 15 4 Chipset Market concentrates in Smart Home, which alone contributes more revenue than Industrial Automation and Smart Meeting combined. Volume there is unit-driven and price-sensitive, so it shapes the mainstream silicon roadmap. Smart City (Outdoor Lighting, City Network Connectivity, etc.) grows fastest because municipal replacement cycles are only now reaching networked controls, and each arterial road converts hundreds of poles at once. Industrial Automation delivers the highest revenue per node.

Competitive Benchmarking

Concentration is moderate. The top five suppliers hold an estimated 55% to 62% of 2025 revenue, and the Herfindahl-Hirschman Index sits in the 900 to 1,150 band, placing the 802 15 4 Chipset Market in unconcentrated-to-moderately-concentrated territory. Two dynamics keep it from consolidating further: Chinese suppliers compete aggressively on price in domestic smart home volume, while Western incumbents defend margin through certified stacks and long-term supply commitments. Design-win cycles run eighteen to thirty months, so share shifts slowly even when a competitor launches a superior part.

Company Est. Revenue Share Range Key Offerings for 802 15 4 Chipset Market Strategic Positioning
Silicon Laboratories Inc. ~15–18% Multi-protocol wireless SoCs, Matter and Thread stacks Stack depth and certification leadership
Texas Instruments Incorporated ~12–15% SimpleLink wireless microcontrollers, sub-1 GHz variants Broad catalogue, long product longevity commitments
NXP Semiconductors NV ~10–13% Tri-radio SoCs, secure element integration Automotive-grade security heritage applied to IoT
Nordic Semiconductor ASA ~8–11% Multi-protocol SoCs with Bluetooth Low Energy co-existence Developer tooling and rapid time-to-market
Microchip Technology Inc. ~7–9% Certified transceivers and modules, industrial temperature parts Supply assurance and industrial channel strength
STMicroelectronics NV ~5–8% Wireless microcontrollers with integrated secure boot European manufacturing footprint and compliance fit
Espressif Systems ~4–6% Combined Wi-Fi and 802.15.4 SoCs Aggressive pricing and open-source developer base
Qualcomm Inc. ~4–6% Connectivity platforms for premium home hubs Border-router and gateway-side integration
Telink Semiconductor ~3–5% Low-cost multi-protocol SoCs Cost leadership in Asian OEM designs
Renesas Electronics Corporation ~3–5% Wireless microcontrollers and building-automation reference designs Systems-level portfolio bundling
Infineon Technologies AG ~2–4% Secure connectivity controllers Security certification and trusted supply chain
Analog Devices Inc. ~2–4% Industrial mesh transceivers and modules Precision sensing plus connectivity bundling


Recent News & Developments


  • Silicon Laboratories Inc. (September 2023): Launched a second-generation multi-protocol platform with integrated secure vault and AI accelerator, signalling the shift toward on-die inference described in [20].
  • U.S. Department of Energy (October 2023): Announced USD 3.46 billion in Grid Resilience and Innovation Partnerships awards, with advanced metering infrastructure named across a majority of selected projects [2].
  • NXP Semiconductors NV (February 2024): Introduced a tri-radio wireless microcontroller family targeting Matter, Thread and Bluetooth Low Energy from a single die, directly addressing the BOM consolidation driver in .
  • European Union (December 2024): The Cyber Resilience Act entered into force, establishing mandatory vulnerability handling obligations across connected product lifecycles and raising compliance costs for chipset suppliers [14].
  • Government of India (March 2025): Extended Revamped Distribution Sector Scheme timelines while reaffirming the 250 million smart meter target, sustaining the largest single national demand pool for metering silicon [11].
  • Texas Instruments Incorporated (June 2025): Committed additional analog and embedded capacity at its Sherman, Texas fabs, easing the allocation constraint identified for mature-node wireless parts [22].


802 15 4 Chipset Market Report Scope

Report Attribute/Metric Details
Market Scope Global revenue from IEEE 802.15.4-compliant transceivers, wireless microcontrollers and system-on-chip devices used for short-range wireless communication; excludes modules, gateways and software licences
Study Period 2021-2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 1.86 Billion
Market Size in 2035 USD 3.83 Billion
CAGR (2026–2035) 7.50%
Fastest Growing Segments Multi-protocol Chipsets (by Type); Smart City (Outdoor Lighting, City Network Connectivity, etc.) (by Application); Asia-Pacific (by Region)
Regions Covered Asia-Pacific (by Region); North America, Europe, APAC, South America, MEA
Companies Profiled 12 suppliers including Silicon Laboratories Inc., Texas Instruments Incorporated, NXP Semiconductors NV, Nordic Semiconductor ASA, Microchip Technology Inc., STMicroelectronics NV, Espressif Systems, Qualcomm Inc., Telink Semiconductor, Renesas Electronics Corporation, Infineon Technologies AG, Analog Devices Inc.
Valuation Currency USD Billion
Methodology Bottom-up revenue aggregation triangulated with top-down macro indicators

FAQs

What certification costs should procurement teams budget when sourcing in the 802 15 4 Chipset Market?
Budget USD 40,000 to USD 120,000 per product family for Matter and Thread conformance testing, plus regional radio type approval. Pre-certified modules cut this substantially but raise unit cost [1].
How long should buyers expect supply commitments to run in the 802 15 4 Chipset Market?
Industrial-grade suppliers typically commit to ten to fifteen year availability; consumer-focused vendors often commit to five. Written longevity programmes matter more than datasheet lifecycle codes [22].
Does Thread replace Zigbee at the silicon level?
No. Both run on the same IEEE 802.15.4 radio, so the same chipset supports either with different firmware. The difference is the network layer and IP addressing, not hardware [15].
What integration problems appear when migrating legacy installations to newer parts from the 802 15 4 Chipset Market?
Commissioning tools and network keys rarely transfer cleanly between stack generations. Most failures trace to border-router configuration rather than the radio itself, so plan parallel-running periods [15].
How should investors read supplier disclosures in this category?
Design-win pipelines lead revenue by eighteen to thirty months, making them a better indicator than quarterly shipments. Watch Matter certification counts per vendor as a proxy [1].
What node count can a single mesh realistically support?
Practical deployments run 200 to 500 nodes per border router before latency degrades, well below theoretical addressing limits. Hop depth beyond six routers is where reliability typically breaks down [12].
Which regulatory nuance most affects sub-GHz product variants?
Duty cycle limits differ sharply: European 868 MHz bands cap transmission time, while U.S. 915 MHz rules permit frequency hopping instead. One hardware design rarely satisfies both efficiently [23].
Author
Author Author Profile Nirmit Biswas LinkedIn Senior Research Analyst
With 5+ years of expertise in Market Intelligence and Strategic Research, Nirmit Biswas specializes in ICT, Semiconductors, and BFSI. Backed by an MBA in Financial Services and a Computer Science foundation, Nirmit blends technical depth with business acumen. He has successfully led 100+ projects for global enterprises and startups, including Amazon, Cisco, L&T and Huawei, delivering market estimations, competitive benchmarking, and GTM strategies. His focus lies in transforming complex data into clear, actionable insights that drive growth, innovation, and investment decisions. Recognized for bridging engineering innovation with executive strategy, Nirmit helps businesses navigate dynamic markets with confidence.
Co-Author Co-Author Profile Garvit Vyas LinkedIn Vice President - Operations
Garvit Vyas is a Research Analyst with experience in working across multiple industry domains in the market research sector. Over the past four years, he has been actively involved in analyzing diverse markets, gathering industry insights, and contributing to the development of comprehensive research reports. His work includes studying market trends, evaluating competitive landscapes, and supporting data-driven business insights. In the early phase of his career, Garvit worked on cross-domain research projects, which helped him build a strong foundation in market analysis, data interpretation, and industry intelligence across various sectors. Later, he transitioned into the Quality Control (QC) function, where he focuses on reviewing and refining research reports and marketing collaterals to ensure accuracy, consistency, and high editorial standards. His responsibilities include validating research data, improving report structure, and maintaining the overall quality of published content. Garvit is committed to maintaining strong research integrity and delivering reliable insights that support informed business decision-making.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.