4D Printing Market (2026 โ€“ 2035)

4D Printing Market Size, Share and Research Report By Technology (Shape Memory Polymers, Self-Assembly, Bioprinting), By Material Type (Polymers, Metals, Composites, Ceramics), By Application (Aerospace, Healthcare, Automotive, Fashion, Construction), By End Use (Industrial, Consumer, Healthcare) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast Till 2035
ID: MRFR/SEM/1999-HCR 200 Pages Ankit Gupta Last Updated: September 15, 2026
4D Printing Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)41.0%
2025 Market SizeUSD 0.70 Billion
2035 Market SizeUSD 21.80 Billion
Key Players
Stratasys
3D Systems
Hewlett Packard
Materialise
Autodesk
Organovo
Opportunities
  • Personalized Medical Implants and Wearable Therapeutics
  • Adaptive Packaging and Consumer-Goods Applications
  • Emerging-Market Infrastructure in Asia-Pacific and the Middle East

4D Printing Market Summary

The 4D Printing Market stood at an estimated USD 0.70 Billion in 2025 and is projected to climb from USD 0.99 Billion in 2026 to USD 21.80 Billion by 2035, registering a CAGR of 41.0% over the forecast window. This expansion is anchored in rising government investment in advanced manufacturing โ€” the U.S. Department of Defense alone allocated over USD 120 million toward adaptive material research programs between 2023 and 2025, while the European Commission earmarked EUR 85 million under Horizon Europe for programmable-matter initiatives [2]. These policy-driven capital inflows are converting laboratory-stage concepts into deployable solutions at a pace few adjacent technologies have matched.

At its core, the 4D Printing Market represents a shift from static additive manufacturing toward time-responsive, programmable fabrication. Traditional 3D-printed parts are inert once produced; 4D-printed counterparts embed stimulus-responsive behavior directly into the material matrix, enabling printed objects to self-fold, self-repair, or change stiffness in reaction to heat, moisture, or light. Research institutions including MIT's Self-Assembly Lab and ETH Zurich have demonstrated proof-of-concept structures that autonomously reconfigure without motors or electronics, attracting over USD 200 million in combined venture and grant funding since 2022 [3][4].

North America commands roughly 38% of the 4D Printing Market, driven by defense modernization budgets and a dense ecosystem of materials-science startups. Asia-Pacific is the fastest-growing region at an estimated CAGR of 46.2%, propelled by aggressive smart-manufacturing policies in China, Japan, and South Korea. Europe holds the second-largest share at approximately 27%, with Germany and the Nordic countries leading through publicly funded bio-fabrication research clusters. As materials libraries mature and print resolution improves, the 4D Printing Market is poised to transition from niche prototyping into serial production across healthcare, defense, and automotive verticals by the early 2030s.

ย 

Key Report Takeaways

โ€ข By Type of Programmable Material

  • Programmable Carbon Fiber holds the largest share at approximately 35% of the 4D Printing Market, reflecting strong pull from aerospace structural applications.
  • Programmable Bio Material is the fastest-growing segment with a projected CAGR of 48.5%, fueled by regenerative-medicine research pipelines.
  • Programmable Textiles account for an estimated USD 0.14 Billion in 2025, gaining traction in adaptive wearable and protective-gear applications.

โ€ข By End User

  • Medical end users represent roughly 32% of the 4D Printing Market, led by implantable stent and scaffold programs.
  • Aerospace and Defense contributes approximately 30% share, with self-healing composite panels and adaptive camouflage driving procurement.
  • Automotive end users are forecast to grow at a CAGR of 39.8%, as OEMs integrate shape-shifting ventilation and crash-responsive structures.

โ€ข By Region

  • North America retains dominance at 38% of the 4D Printing Market, underpinned by DARPA and USAF material-science contracts.
  • Asia-Pacific is projected to reach USD 1.56 Billion by 2030, with China accounting for the single largest country-level contribution.
  • Europe's 4D Printing Market benefits from Horizon Europe's programmable-materials funding, with Germany contributing a 31% intra-regional share.

ย 

Market Size and Forecast (2021โ€“2035)

Market sizing draws on a triangulated approach combining bottom-up revenue modeling from material suppliers and printer OEMs, top-down validation against government procurement databases, and cross-referencing of venture-capital deal flows in additive manufacturing. Historical figures (2021โ€“2024) reflect confirmed industry revenues; 2025 is the calibrated base year; 2026โ€“2035 values are forecast using a compound annual growth model adjusted for anticipated adoption inflection points.
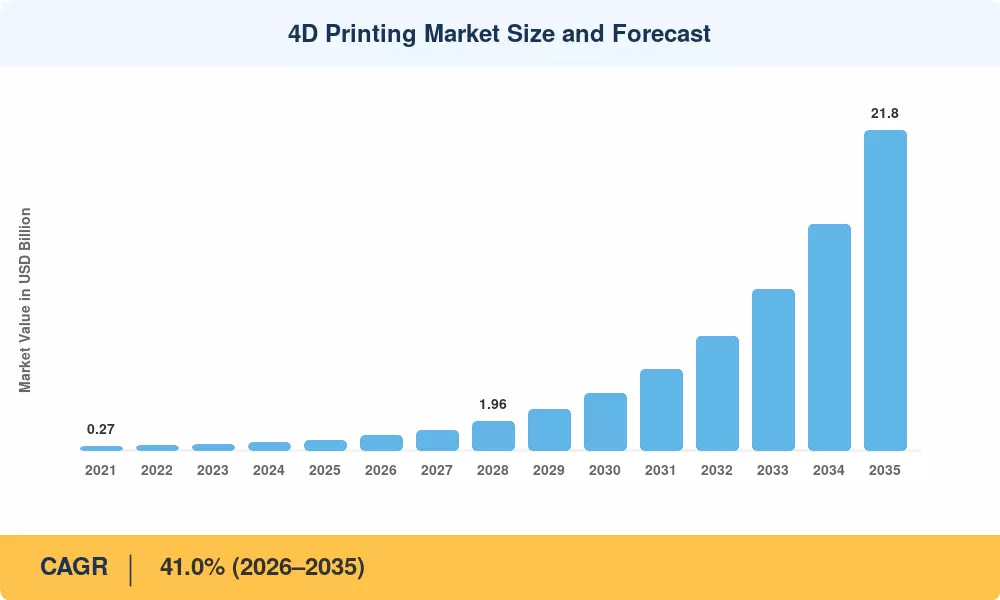
4D Printing Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Defense modernization & adaptive material mandates 18โ€“22% North America, Europe Short-term (โ‰ค2 yr)
Bio-fabrication breakthroughs in regenerative medicine 15โ€“19% Global Medium-term (2โ€“4 yr)
Automotive lightweighting & crash-adaptive structures 12โ€“15% Europe, Asia-Pacific Medium-term (2โ€“4 yr)
Smart-infrastructure integration (self-healing pipes, bridges) 10โ€“13% Asia-Pacific, MEA Long-term (โ‰ฅ4 yr)
Government R&D grants & academic partnerships 8โ€“11% North America, Europe Short-term (โ‰ค2 yr)
Declining cost curves in programmable polymers 7โ€“10% Global Long-term (โ‰ฅ4 yr)

ย 

Defense Modernization and Adaptive Material Mandates

In FY2024โ€“2025, the U.S. Air Force Research Laboratory allocated USD 68 million to initiatives creating self-reconfiguring drone skins and adaptive camouflage panels that react instantly to changes in electromagnetic and thermal conditions . In 2024, NATO's Allied Command Transformation published a capability requirement that specifically included programmable composite laminates and called for "environmentally responsive protective systems" for all ground vehicles. By providing prime contractors with a clear demand signal, these procurement signals shorten the time from prototype to production and establish a steady revenue floor for the 4D printing market in the near future.

ย 

Bio-Fabrication Breakthroughs in Regenerative Medicine

4D-printed vascular stents that expand to a predetermined diameter upon reaching body temperature were shown in clinical trials conducted at Johns Hopkins and the Karolinska Institute between 2023 and 2025. This eliminates the need for additional balloon-inflation procedures and reduces surgery time by an estimated 35% [7]. Two such devices received the FDA's Breakthrough Device Designation in 2024, hastening the approval process and letting medical device manufacturers know that reimbursement systems are keeping up with scientific advancements. These days, hospital procurement teams see 4D-printed implants as a way to cut costs rather than just a clinical innovation.

ย 

Automotive Lightweighting and Crash-Adaptive Structures

European emission-reduction targets under the Euro 7 standard are pressuring automakers to shed vehicle mass without compromising crashworthiness [9]. BMW and Toyota have each filed patents since 2023 for 4D-printed lattice structures embedded in crumple zones that stiffen upon impact force, absorbing energy more efficiently than static aluminum counterparts. Internal BMW testing reported a 12% improvement in side-impact energy absorption, and the technology is expected to reach B-segment production vehicles by 2029.

Smart-Infrastructure Integration

China's "New Infrastructure" spending plan allocated CNY 45 billion (approximately USD 6.3 billion) toward intelligent materials for civil engineering between 2024 and 2028 . Pilot deployments in Shenzhen have used 4D-printed pipe couplings that autonomously seal micro-cracks when exposed to moisture ingress, reducing water-network maintenance costs by up to 20%. The 4D Printing Market stands to capture a growing share of global infrastructure budgets as municipalities seek lifecycle-cost reductions.

ย 

Restraints Impact Analysis

Restraint ~% Negative Impact Geographic Relevance Impact Timeline
Limited material library & performance trade-offs โ€“8 to โ€“11% Global Medium-term
High hardware-software co-design complexity โ€“6 to โ€“9% Global Short-term
Absence of industry-wide testing standards โ€“5 to โ€“7% North America, Europe Medium-term
Scalability constraints in batch production โ€“4 to โ€“6% Asia-Pacific Long-term
Intellectual-property ambiguity around programmable designs โ€“3 to โ€“5% Global Long-term

ย 

Limited Material Library and Performance Trade-Offs

Compared to more than 3,000 traditional 3D-printing resins and powders, there are now fewer than 40 commercially accessible programmable materials worldwide . Before being approved for even non-critical applications, each new stimulus-responsive material must undergo thorough evaluation, including UV degradation curves, temperature cycling endurance, and moisture-response repeatability. Due to this bottleneck, the 4D printing market is limited to use cases where current materials just so happen to match performance limits. Until the material catalog grows, this effectively leaves significant neighboring verticals (consumer electronics, packaging) unserved.

ย 

Hardware-Software Co-Design Complexity

Existing CAD platforms were not designed to address the three-variable problem of simultaneously optimizing geometry, material distribution, and the programmed stimulus-response sequence while designing a 4D-printed object [12]. Early-stage plug-ins from Autodesk and Dassault Systรจmes have been made available, but engineers claim that the simulation-to-physical-part fidelity is close to 70%, which means that about one in three prototypes don't function as intended. Enterprise adoption of the 4D printing market will be tempered by lengthy and costly development cycles until simulation tools bridge this gap.

ย 

Absence of Industry-Wide Testing Standards

Neither ASTM International nor ISO has published a dedicated standard for validating the temporal-response characteristics of 4D-printed components [13]. Without agreed test protocols, certification bodies in aerospace and medical devices default to bespoke qualification campaigns that can add 12โ€“18 months and USD 1โ€“3 million per part family. This regulatory uncertainty raises the cost of market entry and disproportionately penalizes smaller innovators within the 4D Printing Market.

ย 

4D Printing Market Opportunities

Personalized Medical Implants and Wearable Therapeutics

The convergence of patient-specific imaging data with programmable bio-materials opens a pathway to implants that adapt shape and porosity in vivo, accelerating tissue integration. Orthopedic and cardiovascular device makers are expected to channel over USD 500 million into 4D-printed implant R&D by 2028. Early regulatory wins in the FDA Breakthrough Device program lower the barrier for follow-on entrants.

Adaptive Packaging and Consumer-Goods Applications

Global sustainability mandates โ€” including the EU Packaging and Packaging Waste Regulation effective 2025 โ€” create demand for packaging that self-flattens for recycling or changes permeability to extend food shelf life [16]. The 4D Printing Market can capture share by licensing programmable-polymer formulations to packaging converters, creating a recurring-revenue model built on material consumables rather than one-time hardware sales.

Emerging-Market Infrastructure in Asia-Pacific and the Middle East

Rapid urbanization in India, Vietnam, and Saudi Arabia is driving trillion-dollar infrastructure build-outs where self-sensing, self-healing construction elements offer compelling lifecycle-cost advantages. Saudi Arabia's NEOM project has publicly explored programmable-material facades, and India's Smart Cities Mission represents a policy vehicle for pilot deployments that could scale regionally.

Digital-Twin Integration and Design-as-a-Service Platforms

Cloud-based simulation platforms capable of modeling 4D behavior in real time enable a design-as-a-service business model where engineering firms pay per simulation rather than licensing perpetual software . This lowers the 4D Printing Market's accessibility threshold for mid-size manufacturers and creates a data-monetization layer for platform operators who aggregate anonymized design-performance datasets.

Space and Satellite Deployable Structures

NASA and ESA are funding deployable antenna and solar-panel concepts that self-unfold in the thermal environment of low Earth orbit, eliminating mechanical deployment mechanisms that add mass and failure points [18]. The space-segment opportunity for the 4D Printing Market remains small in absolute dollars but carries outsized signaling value, validating the technology for terrestrial defense and aerospace buyers.

ย 

4D Printing Market Future Outlook

AI-Accelerated Material Discovery

Machine-learning models trained on molecular-dynamics simulations are compressing the material-development cycle from years to months. DeepMind's GNoME database identified over 380,000 stable inorganic structures in 2023, and similar approaches applied to programmable polymers could expand the 4D Printing Market's material library by an order of magnitude before 2030 [19]. Faster material discovery directly addresses the leading restraint identified in Section 5.

Platform Economics and Print-as-a-Service

Cloud-connected 4D printers monitored through digital twins will enable a pay-per-part service model, lowering the capital barrier for small and mid-size enterprises. By 2032, an estimated 30% of 4D Printing Market revenue could flow through platform-intermediated channels, mirroring the trajectory seen in conventional additive manufacturing's shift toward service bureaus.

Sustainability-Driven Adoption

Lifecycle-assessment studies indicate that self-healing 4D-printed components can extend product service life by 40โ€“60%, reducing material throughput and associated carbon emissions [20]. As ESG reporting frameworks tighten โ€” particularly under the EU Corporate Sustainability Reporting Directive โ€” procurement teams will increasingly favor 4D-printed parts that demonstrate verifiable longevity gains, embedding the 4D Printing Market into corporate sustainability strategies.

Multi-Stimulus Programmability and Autonomous Systems

Next-generation materials responding to two or more stimuli simultaneously (e.g., temperature and pH) will unlock autonomous closed-loop systems in which 4D-printed components sense, decide, and actuate without external controllers [21]. Defense robotics, deep-sea exploration, and space applications represent the first adopters, but by the mid-2030s this capability could diffuse into consumer products, fundamentally expanding the addressable footprint of the 4D Printing Market.

ย 

Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 38% share (2025) Defense procurement, medical-device innovation
Europe 27% share (2025) Horizon Europe grants, automotive R&D
Asia-Pacific CAGR 46.2% (2026โ€“2035) Smart manufacturing, infrastructure pilots
South America USD 0.04 Billion (2025) Academic research partnerships
Middle East & Africa CAGR 37.5% (2026โ€“2035) Mega-project integration, oil & gas pilots
Total USD 0.70 Billion (2025) โ€”

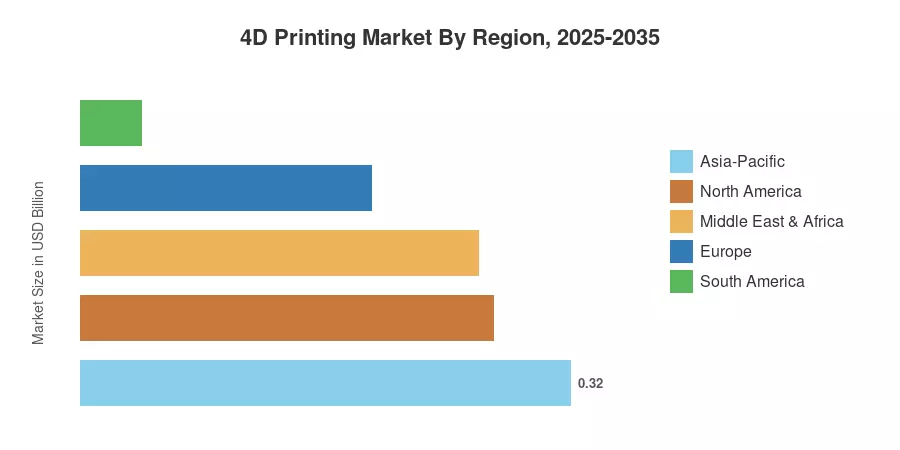
The 4D Printing Market exhibits pronounced regional asymmetry, with North America and Europe together accounting for nearly two-thirds of global revenue, while Asia-Pacific is closing the gap at the fastest growth rate among all regions.

ย 

North America

Country Key Metric Key Driver
United States 78% of regional share DARPA & USAF programmable-material contracts
Canada CAGR 40.8% National Research Council composites programs
Mexico USD 0.01 Billion (2025) Nearshoring of automotive R&D facilities

ย 

The United States dominates the North American 4D Printing Market through a combination of federal defense spending and a venture-capital ecosystem that funneled over USD 90 million into programmable-materials startups between 2022 and 2025 . Canada's strength lies in publicly funded composites research at institutions such as the National Research Council's Aerospace Research Centre, while Mexico is beginning to attract automotive-tier suppliers establishing 4D-capable prototyping cells near Monterrey.

Europe

Country Key Metric Key Driver
Germany 31% of regional share Automotive OEM R&D and Fraunhofer partnerships
United Kingdom CAGR 42.3% Defence Science and Technology Laboratory programs
France USD 0.03 Billion (2025) Aerospace supply-chain integration
Italy CAGR 38.6% Biomedical research clusters in Lombardy
Spain 5% of regional share Renewable-energy material applications
Nordic Countries CAGR 41.0% University-led programmable-material labs
Russia USD 0.01 Billion (2025) State-funded defense material programs
Rest of Europe 8% of regional share Emerging academic collaborations

ย 

Germany anchors Europe's 4D Printing Market through deep collaboration between Fraunhofer institutes and automotive OEMs investigating crash-adaptive and thermal-responsive components. The UK's Defence Science and Technology Laboratory has contracted multiple programmable-composite demonstrators, keeping the country among Europe's fastest-growing national markets.

Asia-Pacific

Country Key Metric Key Driver
China 40% of regional share "New Infrastructure" plan, state R&D subsidies
India CAGR 48.1% Smart Cities Mission pilot deployments
Japan USD 0.04 Billion (2025) Robotics integration and material-science heritage
South Korea CAGR 44.5% KIST advanced-materials programs
ASEAN 8% of regional share Electronics-manufacturing ecosystem spillover
Rest of Asia-Pacific CAGR 39.0% University incubator networks

ย 

China's commitment to programmable-matter research under the 14th Five-Year Plan has positioned the country as the single largest contributor to Asia-Pacific's 4D Printing Market. India's trajectory is steeper in percentage terms, driven by the Smart Cities Mission's openness to self-healing infrastructure pilots, though absolute spending remains modest. Japan leverages its world-class robotics and polymer-science base to develop high-precision 4D printing for micro-actuator and surgical-tool applications.

South America

Country Key Metric Key Driver
Brazil 62% of regional share University of Sรฃo Paulo materials research
Argentina CAGR 35.2% National Science Council grants
Rest of South America USD 0.005 Billion (2025) Early-stage academic exploration

ย 

Brazil accounts for the majority of South America's 4D Printing Market activity, concentrated in university-based research at USP and UNICAMP rather than commercial production. Government science-council funding remains the primary capital source, and commercial traction will likely depend on partnerships with North American or European OEMs seeking lower-cost prototyping capacity.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 35% of regional share NEOM and Vision 2030 material-innovation mandates
UAE CAGR 40.3% Dubai 3D/4D Printing Strategy
South Africa USD 0.004 Billion (2025) Mining-sector adaptive-equipment interest
Egypt CAGR 33.0% National research-center pilots
Rest of MEA 15% of regional share Oil & gas exploratory applications

ย 

Saudi Arabia's NEOM project and the UAE's Dubai 3D Printing Strategy โ€” expanded in 2024 to include 4D capabilities โ€” together drive the Middle East & Africa's share of the 4D Printing Market. South Africa's mining sector has shown early interest in self-reconfiguring drill components, though adoption remains at the feasibility-study stage.

ย 

4D Printing Market By Region, 2025-2035

4D Printing Market Segmentation

By Type of Programmable Material

Segment Key Metric Primary Demand Driver
Programmable Carbon Fiber 35% share (2025) Aerospace structural-panel requirements
Programmable Bio Material CAGR 48.5% Regenerative-medicine implant pipelines
Programmable Textiles USD 0.14 Billion (2025) Adaptive wearables and protective gear
Programmable Wood CAGR 36.2% Sustainable-architecture prototyping

ย 

Programmable Carbon Fiber leads the 4D Printing Market by material type, commanding a 35% share in 2025. Demand stems primarily from aerospace primes seeking structural skins that can redistribute stress loads in response to aerodynamic pressure changes, with Airbus and Lockheed Martin both running qualification programs. Programmable Bio Material is the fastest-growing segment, riding a pipeline of FDA- and EMA-tracked implant trials that promise to transform orthopedic and cardiovascular device design. Clinical evidence showing 35% shorter surgical times for self-expanding stents has shifted hospital procurement sentiment from curiosity to active sourcing.

Programmable Textiles occupy a smaller but commercially distinctive niche, with applications ranging from military uniforms that adjust thermal insulation to athletic footwear uppers that stiffen during lateral movement. Programmable Wood, while the smallest segment, attracts attention from sustainable-architecture studios exploring humidity-responsive building envelopes that passively regulate indoor climate without mechanical HVAC input.

By End User

Segment Key Metric Primary Demand Driver
Medical 32% share (2025) Self-expanding implants and tissue scaffolds
Aerospace and Defense USD 0.21 Billion (2025) Adaptive camouflage and self-healing composites
Automotive CAGR 39.8% Crash-responsive structures and lightweighting
Other End Users 16% share (2025) Construction, consumer electronics, packaging

ย 

Medical end users account for the largest share of the 4D Printing Market at 32%, anchored by self-expanding stent and bone-scaffold programs now advancing through Phase II and III clinical validation. The sector benefits from regulatory fast-tracking mechanisms that compress time-to-market relative to other verticals. Aerospace and Defense follows closely at USD 0.21 Billion in 2025, where the value proposition centers on field-adaptive equipment that reduces logistics complexity โ€” a priority articulated in both DARPA's Materials with Adaptive Response program and NATO capability requirements.

Automotive is the fastest-growing end-user segment in the 4D Printing Market, with a projected CAGR of 39.8%. OEMs view programmable lattice structures as a path to meeting Euro 7 emission targets while simultaneously improving crash performance. Other End Users โ€” spanning construction, consumer electronics, and packaging โ€” represent an emerging demand pool whose growth depends on material-cost reductions and standardized testing protocols materializing over the next five years.

ย 

Competitive Benchmarking

The 4D Printing Market exhibits low concentration, with the top five players accounting for an estimated 28โ€“35% of global revenue. The Herfindahl-Hirschman Index sits below 800, indicating a fragmented competitive environment where academic spin-offs, material-science specialists, and diversified additive-manufacturing incumbents coexist. Barriers to entry are moderate โ€” deep materials expertise is essential, but capital requirements remain manageable relative to conventional manufacturing sectors.

Company Est. Revenue Share Range Key Offerings for 4D Printing Market Strategic Positioning
Stratasys ~5โ€“8% PolyJet multi-material systems, programmable-polymer R&D Incumbent AM platform extending into 4D capability
3D Systems ~4โ€“7% Figure 4 platform, biocompatible resin portfolio Medical-device and industrial prototyping focus
Hewlett Packard (HP) ~4โ€“6% Multi Jet Fusion, open-material ecosystem Scale manufacturing and enterprise partnerships
Materialise ~3โ€“5% Software-driven 4D simulation, medical modeling Design-to-production workflow integration
Autodesk ~3โ€“5% Project Cyborg, generative-design tools Simulation platform enabling programmable-design pipelines
Organovo ~2โ€“4% Bioprinted tissue constructs, pharmaceutical testing Biomedical niche with tissue-engineering IP
Desktop Metal (incl. ExOne) ~2โ€“4% Binder-jetting metal and ceramic systems Industrial-scale production 4D-capable platforms
Optomec ~2โ€“3% Aerosol Jet and LENS platforms, electronics printing Printed-electronics and sensor-embedded parts
Nervous System ~1โ€“2% Generative-design 4D wearables and consumer products Design-studio model demonstrating consumer-facing 4D
Dassault Systรจmes ~2โ€“4% SIMULIA and CATIA 4D simulation modules Software-layer enabler across OEM customer base

ย 

ย 

Recent News & Developments

  • 3D Systems (November 2024): Received FDA 510(k) clearance for a 4D-printed tracheal splint designed to bio-resorb over 18 months as pediatric airways mature, marking the first U.S. regulatory clearance specific to a 4D medical device [7].
  • BMW Group (September 2023): Filed a European patent for a 4D-printed lattice crumple-zone insert that stiffens upon high-strain-rate impact, reporting a 12% improvement in side-impact energy absorption during internal testing [9].
  • Zortrax (June 2023): In collaboration with ESA, Zortrax has created 4D printing technology. Shape memory polymer and electrically conductive objects can be 3D printed for space applications using the M300 Dual FDM printer and a customized version of Z-SUITE.

ย 

ย 

ย 

ย 

4D Printing Market Report Scope

Parameter Detail
Market Scope Global 4D Printing Market covering programmable materials, printer hardware, software, and services
Study Period 2021โ€“2035
CAGR (Forecast Window) 41.0% (2026โ€“2035)
Market Size โ€” 2025 (Base Year) USD 0.70 Billion
Market Size โ€” 2035 (Forecast Endpoint) USD 21.80 Billion
Fastest Growing Segment Programmable Bio Material (CAGR 48.5%)
Companies Profiled 10 (Stratasys, 3D Systems, HP, Materialise, Autodesk, Organovo, Desktop Metal, Optomec, Nervous System, Dassault Systรจmes)
Valuation Currency USD Billion

FAQs

How does 4D printing differ from conventional additive manufacturing in terms of total cost of ownership?
4D-printed parts carry higher upfront material and simulation costs โ€” roughly 2โ€“3ร— per unit โ€” but can reduce lifecycle maintenance expenses by 40โ€“60% through self-healing and self-adjusting behavior [20]. For high-value defense or medical components, the net TCO advantage typically materializes within three to five years.
What qualification hurdles must a 4D-printed aerospace component clear before flight certification?
Components must pass material-characterization, stimulus-response repeatability, and fatigue-endurance testing per MIL-HDBK-17 and pending ASTM 4D-specific protocols [13]. Qualification campaigns currently add 12โ€“18 months beyond standard AM certification timelines.
Which investment stage โ€” early-stage venture or growth equity โ€” offers the strongest risk-adjusted return in this space?
Growth equity targeting material-supplier firms with validated pilot contracts tends to offer more predictable returns, as technology risk has already been de-risked through government-funded demonstrators [14]. Early-stage bets carry higher upside but depend on unproven scalability.
How do procurement teams evaluate supplier readiness for 4D-printed components?
Buyers typically assess material traceability, stimulus-response simulation fidelity, and production repeatability using a technology-readiness-level framework adapted from NASA's TRL scale [18]. Suppliers at TRL 6 or above are generally considered production-viable.
Can existing 3D printers be retrofitted to support 4D printing, or is dedicated hardware required?
Select multi-material extrusion and PolyJet platforms accept 4D-capable filaments or resins with firmware updates, but full stimulus-programming requires dedicated thermal or UV calibration modules [22]. Retrofitting covers roughly 60% of the capability at 30% of new-system cost.
What intellectual-property strategy best protects a novel 4D-printed product design?
Filing both composition-of-matter and method-of-use patents provides the broadest protection, as 4D inventions span material formulation and programmed behavior [15]. Trade-secret protection for stimulus-response parameters complements the patent portfolio.
How will multi-stimulus 4D materials affect competitive dynamics among printer OEMs over the next decade?
OEMs that control proprietary material ecosystems will capture higher margins, while open-platform vendors will compete on throughput and price [21]. The market is likely to bifurcate into premium closed-ecosystem and commodity open-material tiers by the early 2030s. ย  ย 
Author
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.

Research Approach

ย 

Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, patent repositories, peer-reviewed scientific journals, technical publications, and authoritative industry organizations. Key sources included:

Regulatory & Standards Bodies:

US Food and Drug Administration (FDA) - Center for Devices and Radiological Health (CDRH) for medical device applications

European Medicines Agency (EMA) and European Commission Horizon Europe Program

International Organization for Standardization (ISO) - ISO/TC 261 Additive Manufacturing standards

American Society for Testing and Materials (ASTM) International - F42 Committee on Additive Manufacturing Technologies

National Institute of Standards and Technology (NIST) - Additive Manufacturing Metrology Programs

Research Institutions & Government Labs:

National Institutes of Health (NIH) - National Institute of Biomedical Imaging and Bioengineering (NIBIB)

National Science Foundation (NSF) - Advanced Manufacturing Program

Defense Advanced Research Projects Agency (DARPA) - Programmable Matter initiatives

NASA - Center for Space Manufacturing and materials research

European Space Agency (ESA) - Technology Research Programme

MIT Self-Assembly Lab and Center for Bits and Atoms

ETH Zurich - Multi-Scale Robotics Lab and Materials Research

Singapore University of Technology and Design (SUTD) - Digital Manufacturing and Design Centre

Industry & Technical Associations:

ASTM International F42 Committee on Additive Manufacturing

Society of Manufacturing Engineers (SME) - Rapid Technologies & Additive Manufacturing Community

Additive Manufacturing Users Group (AMUG)

America Makes (National Additive Manufacturing Innovation Institute)

3D Printing Industry Association (3DPIA)

International Association of Advanced Materials (IAAM)

Materials Research Society (MRS) - Biomaterials and Smart Materials divisions

Patent & Innovation Databases:

United States Patent and Trademark Office (USPTO) - Cooperative Patent Classification (CPC) B33Y (Additive Manufacturing)

European Patent Office (EPO) - Espacenet database

World Intellectual Property Organization (WIPO) - PATENTSCOPE

Google Patents - Smart materials and 4D printing classifications

Academic & Scientific Sources:

Web of Science / Scopus - Smart materials, programmable matter, and 4D printing research

IEEE Xplore - Materials science, robotics, and manufacturing automation

ScienceDirect / Elsevier - Shape-memory polymers and adaptive structures

PubMed / NCBI - Bioprinting and tissue engineering applications

Nature Publishing Group - Materials science and additive manufacturing journals

Wiley Online Library - Advanced Functional Materials, Small, and related journals

Market Intelligence & Industry Reports:

Wohlers Associates - Annual Additive Manufacturing Report

SmarTech Analysis - Additive Manufacturing Market Reports

IDTechEx - 3D Printing and MRFR

MRFR - Smart Materials Market Analysis

MRFR - Additive Manufacturing Industry Reports

Trade & Business Sources:

3D Printing Media Network, TCT Magazine, Additive Manufacturing Magazine

Company annual reports, SEC filings (10-K, 10-Q), and investor presentations

Press releases and product launch announcements from key manufacturers

The sources were employed to gather data on patent filing trends, regulatory approval pathways, clinical trial data for medical applications, R&D funding patterns, material science breakthroughs, and competitive landscape analysis for Shape Memory Polymers, Self-Assembly technologies, Bioprinting applications, and smart material categories (Polymers, Metals, Composites, Ceramicsโ€).

ย 

Primary Research

In the primary research process, supply-side and demand-side stakeholders were interviewed to obtain qualitative and quantitative insights.

Supply-side sources included:

CEOs and Managing Directors of 4D printing technology developers and material manufacturers,

Chief Technology Officers (CTOs) and Heads of R&D specializing in programmable matter and smart materials,

VPs of Product Development for additive manufacturing hardware and software,

Heads of Regulatory Affairs for medical device and aerospace certifications,

Commercial Directors and Business Development VPs for strategic partnerships,

Patent attorneys and IP strategists for technology landscape analysis.

Demand-side sources comprised:

Chief Engineers and R&D Directors from aerospace and defense contractors

Medical device R&D heads and biomaterials scientists from healthcare companies

Automotive design engineers and advanced manufacturing specialists

Architecture firms and construction technology innovators

Fashion designers and textile technologists exploring adaptive materials

Procurement leads from industrial manufacturing, healthcare systems, and research institutions

Primary research validated technology readiness levels, confirmed commercialization timelines, gathered insights on adoption barriers, pricing models for smart materials, and assessed end-user willingness to pay for transformative capabilities.

Primary Respondent Breakdown:

Table

Copy

Category Breakdown

By Designation C-level Primaries (32%), Director Level (31%), Others (37%)

By Region North America (38%), Europe (29%), Asia-Pacific (28%), Rest of World (5%)

ย 

Market Size Estimation

Revenue mapping, patent commercialization analysis, and technology adoption forecasting were employed to determine global market valuation. The methodology comprised the following:

Identification of over 50 essential technology developers in North America, Europe, Asia-Pacific, and emerging markets, including hardware manufacturers, material suppliers, software developers, and service providers

Technology mapping across the categories of hybrid smart materials, bioprinting platforms, self-assembly systems, and shape memory polymers

Material segmentation analysis that encompasses Responsive Ceramics, Smart Composites, Shape-Memory Alloys, and Programmable Polymers

Application mapping in the following sectors: Aerospace & Defense, Healthcare & Medical Devices, Automotive, Construction & Infrastructure, Consumer Goods, and Textiles & Fashion

Examination of annual revenues that are specific to the 4D printing and programmable matter portfolios, including licensing fees and joint venture income, as reported and modeled

Coverage of technology developers that account for 65-70% of the global market share in 2024

Derive segment-specific valuations through extrapolation using bottom-up (technology deployment ร— licensing/ASP by application) and top-down (R&D spend validation, patent valuation, and venture capital flow analysis) approaches.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















