North America: Expanding dense cluster of aerospace
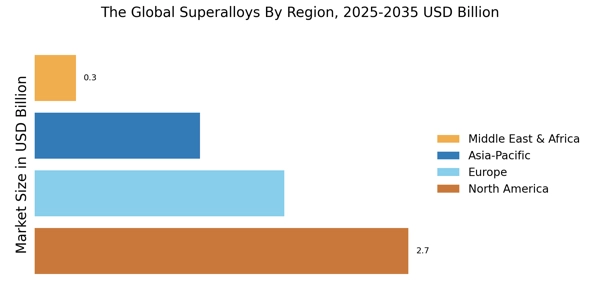
North America dominates by value, accounting for about 45–50% of the superalloys market in 2024–2025, with a market size of roughly USD 3.1–3.2 billion and projected growth to over USD 5 billion by the early 2030s at around 7% CAGR. This leadership stems from a dense cluster of aerospace and defense OEMs (Boeing, Lockheed Martin, GE Aviation) and a strong industrial‑gas‑turbine and power‑generation base. The region is also at the forefront of advanced manufacturing, including additive‑manufactured superalloy components and high‑performance turbine systems.
Europe: Strong Production dense cluster of aerospace
Europe is the second‑largest region, valued at about USD 2.18 billion in 2024 and forecast to reach ~USD 3.7 billion by 2032, growing at roughly 6.8% CAGR. Germany leads within Europe, driven by aerospace, premium automotive, and energy‑sector demand for nickel‑ and cobalt‑based superalloys. European manufacturers emphasize innovation, sustainability, and strict quality standards, which supports steady adoption in engines, turbines, and industrial‑machinery components across the EU.
Asia Pacific: Growing dense cluster of aerospace
Asia‑Pacific (APAC) is the most dynamic region, valued at USD 1.78 billion in 2024 and expected to grow to around USD 3.1 billion by 2032, implying a CAGR of about 7.3%. China is the largest APAC market, followed by India, Japan, and South Korea, where demand is being driven by aerospace‑OEM localization, industrial‑gas‑turbines, power plants, and expanding automotive and turbocharger production. APAC is also becoming a center for indigenous superalloy R&D and capacity expansion, particularly in China and India, supported by government‑backed industrial‑modernization programs.
South America: Protection of dense cluster of aerospace
South America is a small but emerging market in the sonobuoy industry, driven by maritime South America is currently the smallest reported regional segment, but it is expected to grow steadily, piggybacking on aerospace‑maintenance, power‑plant modernization, and automotive‑turbocharger demand, particularly in Brazil and Mexico. While detailed market‑size figures are scarcer, the region benefits from spillover demand from North American and European OEMs, as well as regional industrial‑modernization efforts. Overall, South America remains a niche but increasingly relevant node in the superalloys supply and service network.
Middle East & Africa: Emerging dense cluster of aerospace
Middle East & Africa (MEA) represents a smaller but structurally growing segment, valued at USD 311 million in 2024 and projected to reach around USD 515 million by 2032, with a CAGR near 6.5%. Growth is anchored in oil & gas, power generation, and desalination infrastructure, especially in the Gulf Cooperation Council (GCC) states, where high‑temperature and corrosion‑resistant superalloys are used in turbines, compressors, and offshore equipment. North Africa is also gradually increasing its share as energy‑infrastructure projects expand.



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


