Software Defined Infrastructure Market 요약
시장 조사 미래 분석에 따르면, 소프트웨어 정의 인프라 시장 규모는 2024년에 505.4억 달러로 추정되었습니다. 소프트웨어 정의 인프라 산업은 2025년 550.4억 달러에서 2035년까지 1291.1억 달러로 성장할 것으로 예상되며, 2025 - 2035년 예측 기간 동안 연평균 성장률(CAGR)은 8.9%에 이를 것으로 보입니다.
주요 시장 동향 및 하이라이트
소프트웨어 정의 인프라 시장은 기술 발전과 진화하는 비즈니스 요구에 의해 강력한 성장을 경험하고 있습니다.
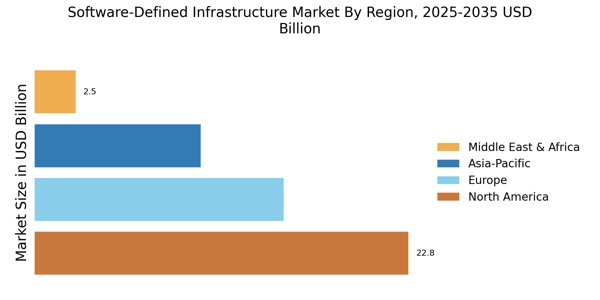
- 북미는 광범위한 클라우드 채택과 기업 투자의 추진으로 소프트웨어 정의 인프라의 가장 큰 시장으로 남아 있습니다.
- 아시아 태평양 지역은 디지털 전환 이니셔티브와 인프라 현대화의 증가로 가장 빠르게 성장하는 시장으로 부상하고 있습니다.
- 컴퓨트 부문은 시장을 계속 지배하고 있으며, 스토리지 부문은 데이터 생성 및 관리 필요성 증가로 인해 빠른 성장을 보이고 있습니다.
- 주요 시장 동인은 하이브리드 IT 솔루션을 채택하는 조직에 필수적인 확장성 및 향상된 보안 기능에 대한 증가하는 수요입니다.
시장 규모 및 예측
| 2024 시장 규모 | 50.54 (억 달러) |
| 2035 시장 규모 | 129.11 (억 달러) |
| CAGR (2025 - 2035) | 8.9% |
주요 기업
VMware (미국), Microsoft (미국), Cisco (미국), Hewlett Packard Enterprise (미국), Dell Technologies (미국), IBM (미국), Red Hat (미국), Oracle (미국), Nutanix (미국)




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



