Optical Coherence Tomography Market (2026 - 2035)
광 간섭 단층 촬영 시장 조사 보고서 - 2032년까지의 글로벌 예측
Forecast Period
2026-2035
CAGR
11.6%
2025 Market Size
USD 2.08 Billion
2035 Market Size
USD 6.23 Billion
공유:


Optical Coherence Tomography Market Summary
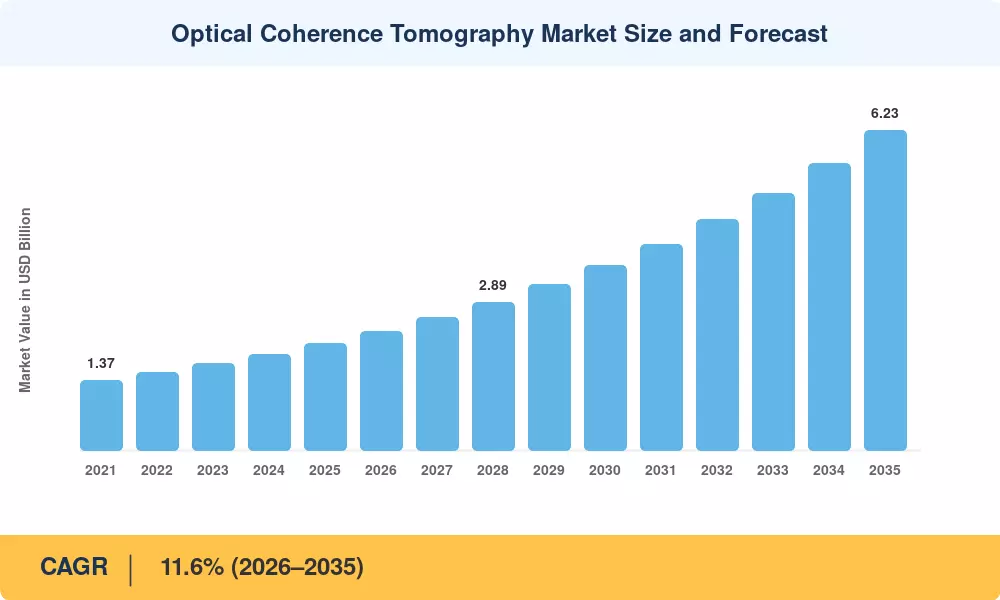
The Optical Coherence Tomography Market reached USD 2.08 billion in 2025 and opens the forecast window at USD 2.32 billion in 2026, climbing to USD 6.23 billion by 2035 at an 11.6% CAGR. Two catalysts anchor that trajectory. The first is reimbursement: the introduction of a dedicated United States CPT code for OCT angiography in 2025 gave clinics a billable pathway for a modality they had previously absorbed as overhead [16]. The second is clinical evidence — the ILUMIEN IV trial, enrolling 2,487 patients across 18 countries, established larger minimal stent area under OCT guidance and reset how interventional cardiologists argue for capital budget [1].
The quiet labor of replacement cycles obscures the headline number. Time-domain platforms, which were previously the default installed base, are being phased out in favor of spectral-domain and swept-source engines, which acquire an order of magnitude more quickly. The current location of the ceiling is illustrated by the 250 kHz angiography scan speed that Heidelberg Engineering has cleared [6]. In February 2025, Canon allocated USD 50 million to a Cleveland imaging research center, indicating that platform vendors anticipate that the next decade of differentiation will be driven by software and analytics rather than optics alone [11].
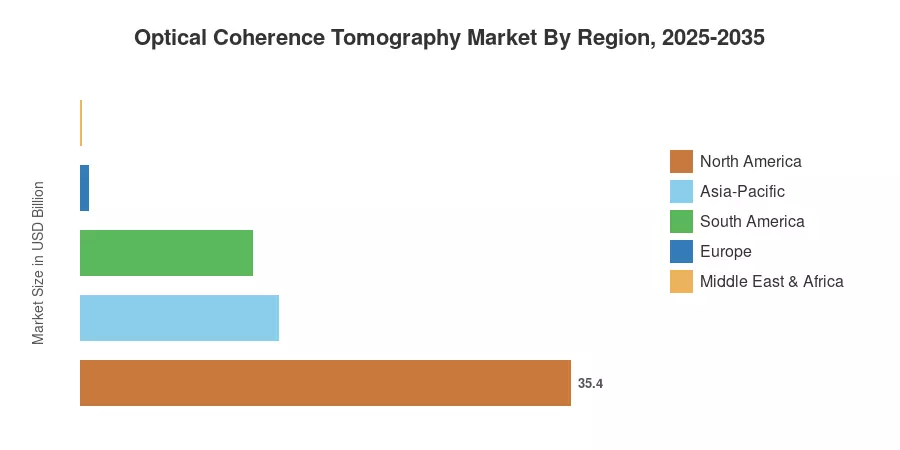
North America is responsible for 35.4% of 2025 revenue due to its concentrated ophthalmology practice networks and early angiography reimbursement. The Asia-Pacific region is expected to compound at the quickest rate of 14.3% through 2035, the highest rate recorded globally. The implementation of diabetic retinopathy screening mandates in China and India is driving this growth. Community optometry deployment under the NHS Long Term Plan is a contributing factor to Europe's second-place ranking. By 2032, it is anticipated that the disparity between regions will decrease significantly.
Key Report Takeaways
• By Technology
- Spectral-domain systems command 46.8% of 2025 Optical Coherence Tomography Market revenue, the installed-base workhorse across retina and glaucoma clinics.
- Swept-source platforms register a 14.9% CAGR to 2035 as deeper choroidal penetration becomes a purchasing requirement.
- Time-domain OCT contributes USD 0.19 billion in 2025 and continues its structural decline.
• By Region
- North America accounts for 35.4% of the Optical Coherence Tomography Market in 2025
- Asia-Pacific posts a 14.3% CAGR across the forecast window
- Europe contributes USD 0.56 billion in 2025
Market Size and Forecast (2021–2035)
Estimates below combine vendor shipment data, 510(k) clearance filings, hospital capital-procurement disclosures, and procedure-volume modelling drawn from ophthalmology and interventional cardiology registries. Historical years are reconciled against published financials from listed manufacturers; forecast years apply installed-base replacement rates layered onto procedure growth.
Driver Impact Analysis
| Driver | ~% Impact on CAGR | Geographic Relevance | Impact Timeline | Ref |
| Rising retinal disease burden (AMD, diabetic retinopathy, glaucoma) | 3.1 | Global | Long-term (≥4 yr) | [14] |
| Intravascular imaging evidence in complex PCI | 2.4 | North America, Europe, Japan | Medium-term (2–4 yr) | [1][2][17] |
| Dedicated angiography reimbursement pathways | 1.9 | United States | Short-term (≤2 yr) | [16] |
| AI-enabled interpretation and workflow automation | 1.7 | Global | Medium-term (2–4 yr) | [9] |
| Swept-source and higher scan-speed platforms | 1.5 | Global | Medium-term (2–4 yr) | [6] |
| Community optometry and primary-care deployment | 1.2 | Europe, Asia-Pacific | Long-term (≥4 yr) | |
| Handheld and point-of-care form factors | 0.9 | Emerging markets | Long-term (≥4 yr) | [19] |
Retinal Disease Prevalence Is the Structural Floor
Age-related macular degeneration affects more than 200 million people globally, and diabetic retinopathy prevalence exceeds 100 million patients — a population requiring longitudinal follow-up scans rather than one-time diagnosis [16]. That distinction matters commercially. A glaucoma or AMD patient generates repeat imaging over a decade or more, converting an episodic diagnostic purchase into recurring procedure volume. Anti-VEGF treatment protocols reinforce the pattern, since injection intervals are now titrated against measured retinal thickness rather than fixed schedules.
Cardiology Evidence Shifted from Promising to Actionable
Abbott's ILUMIEN IV study randomised 2,487 patients at 80 sites. It demonstrated a statistically significant 7% increase in minimal stent area under OCT guidance versus angiography alone, alongside a 64% reduction in stent thrombosis rates [5]. Complementary bifurcation data from the OCTOBER trial extended the case to complex anatomy [2]. Network meta-analysis pooling ILUMIEN IV and OCTOBER with 18 prior studies found intravascular imaging guidance cut target lesion failure by 31% relative to angiography [18]. Cath lab directors now have the ammunition to defend catheter budgets.
Reimbursement Converted Capability into Revenue
Introduction of the first dedicated Medicare CPT code for OCT angiography in the United States in 2025 formally recognised a procedure that clinics had performed for years without discrete billing [16]. Practices that previously treated angiography as a differentiator absorbed into overhead can now build a return-on-investment case at the practice-management level. Vendors responded by unbundling angiography modules as separately priced upgrades to existing installed platforms.
Software Became the Competitive Surface
ZEISS secured CE marking for Cirrus PathFinder, a clinical decision-support layer that sits inside existing OCT workflows and accelerates interpretation in high-volume practices [9]. The company simultaneously expanded its Cirrus 6000 normative reference database to 870 healthy eyes, roughly tripling prior coverage and improving stratification across optic disc sizes [9]. Differentiation is migrating from optical hardware toward normative data assets and algorithmic triage — a shift that favours vendors with large longitudinal image repositories.
Restraints Impact Analysis
Restraint weightings reflect analyst assessment of drag on adoption velocity within the Optical Coherence Tomography Market. Values are directional indicators rather than subtractive components of the forecast CAGR.
| Restraint | ~% Drag on CAGR | Geographic Relevance | Impact Timeline | Ref |
| High capital cost per unit | -2.2 | Emerging markets | Long-term (≥4 yr) | |
| Reimbursement gaps outside ophthalmology | -1.6 | Global | Medium-term (2–4 yr) | [16] |
| Slow intravascular imaging adoption in catheter labs | -1.3 | Global | Medium-term (2–4 yr) | [18] |
| Trained interpretation capacity shortfall | -1.0 | Asia-Pacific, MEA | Long-term (≥4 yr) | [19] |
| Cybersecurity and imaging data governance burden | -0.7 | Europe, North America | Short-term (≤2 yr) | [9] |
Capital Cost Blocks the Long Tail
Tabletop systems remain a six-figure purchase in most configurations, which puts them beyond the reach of the single-practitioner clinics that constitute the majority of eye-care delivery in South Asia, Southeast Asia, and much of Africa. Financing structures are thin, and refurbished-equipment channels are informal. Handheld devices compress the price point meaningfully, but sacrifice the normative databases and angiography modules that justify the premium in developed markets.
Catheter Lab Uptake Trails the Evidence
Adoption of intravascular imaging has moved slowly despite favourable trial data — usage grew roughly 60% between 2013 and 2019, from a small base. Procedure time, catheter cost, and operator familiarity all work against routine deployment. ILUMIEN IV itself found no statistically significant difference in two-year target-vessel failure between arms, a nuance sceptical interventionalists cite when resisting protocol change [1]. Enrolment during the pandemic likely biased outcomes toward the mean, but the headline result complicates the sales conversation.
Interpretation Capacity Is the Hidden Constraint
Placing a device does not create diagnostic throughput. Regions expanding screening fastest are precisely those with the thinnest retinal-specialist density, and volume screening generates image loads that outstrip available reading capacity. Automated triage helps, but regulatory clearance for autonomous interpretation remains narrow, so a qualified human still signs most reports.
Optical Coherence Tomography Market Opportunities
Photonic-Chip Miniaturisation
Silicon-photonics approaches promise to collapse the interferometer onto a chip, cutting bill-of-materials cost by an order of magnitude. UK-based Siloton raised £860,000 in October 2024 to develop its Akepa chip specifically for macular degeneration detection. Success here reshapes the addressable base — moving OCT from a specialist capital purchase toward a commodity module embeddable in optometry chairs and, eventually, home devices.
Emerging-Market Screening Programmes
India and China together account for the largest untreated diabetic retinopathy populations globally, and both are building tiered screening infrastructure that pairs low-cost capture at primary level with centralised reading. Handheld systems already represent a substantial share of unit volume precisely because they serve neonatal, paediatric, and intraoperative settings where chinrest-based platforms cannot reach [16]. Vendors that price for tier-two and tier-three cities rather than flagship hospitals will capture disproportionate volume.
Imaging Data Monetisation and Subscription Models
Normative databases are becoming defensible assets. ZEISS's expanded reference library and Heidelberg's multimodal repositories create switching costs no hardware specification can match [9]. The commercial logic points toward recurring-revenue structures: analytics subscriptions, per-scan interpretation fees, and pharmaceutical partnerships that embed imaging endpoints in clinical trials. Anti-VEGF developers already contract for centralised reading services, an early template for what device vendors could operate directly.
Non-Destructive Industrial Inspection
Semiconductor inspection, aerospace composite validation, and precision-manufacturing quality control all require sub-surface imaging without sample destruction. The industrial channel remains small relative to healthcare but carries different procurement dynamics — shorter approval cycles, no reimbursement dependency, and buyers accustomed to capital equipment. Vendors with existing photonics supply chains face low incremental cost to serve it.
Home Monitoring for Chronic Retinal Disease
Remote monitoring platforms combining simplified capture hardware with algorithmic change detection allow AMD patients to be screened between clinic visits, escalating only on measured deterioration. Reimbursement precedent is thin but forming, and the model aligns with payer interest in reducing avoidable injection visits.
Optical Coherence Tomography Market Future Outlook
Autonomous Interpretation Reaches Clinical Scale
Algorithmic layers currently assist rather than replace human reading, but clearance pathways are widening. Heidelberg's cleared software now pairs 250 kHz angiography acquisition with active eye tracking, generating image volumes that make manual review impractical at screening scale [6]. By the early 2030s, expect triage autonomy — algorithms clearing normal scans without human review — to become the standard operating model in high-volume screening, with specialists reserved for flagged cases.
Platform Economics Displace Hardware Margins
Vendors are converging on an ecosystem model where the capture device is a channel into recurring analytics revenue. ZEISS's integrated medical ecosystem received FDA clearance and links diagnosis through treatment and follow-up within a single data environment [9]. Once a practice's longitudinal patient history lives inside one vendor's normative framework, switching becomes clinically disruptive rather than merely inconvenient. Expect gross margin to migrate steadily from instrument sale toward subscription.
Multimodal Convergence in Cardiology
Intravascular imaging is trending toward combined modality catheters that pair high-resolution structural imaging with physiological measurement in a single pullback. Abbott already bundles coronary physiology measurement into its imaging platform. Guideline bodies incorporating imaging-guided intervention into revascularisation recommendations would accelerate this materially — European and American societies have moved in that direction following recent meta-analytic evidence [17][18].
Cost Curve and Access Inversion
Photonic integration is the variable that determines whether this market plateaus near USD 6 billion or overshoots. Chip-scale interferometers would push unit economics below the threshold where primary care and community pharmacy deployment becomes viable, converting a specialist diagnostic into a screening commodity. Early-stage funding into that thesis is small but rising. The decade's most consequential competitive risk for incumbents is a component-level cost disruption they do not control.
Regional Market Share Analysis
| Region | Metric (2025) | Primary Investment Themes |
| North America | 35.4% share | Angiography reimbursement, AI decision support, catheter-based cardiology |
| Europe | USD 0.56 Billion | Community optometry deployment, multimodal platform upgrades |
| Asia-Pacific | 14.3% CAGR (2026–2035) | National screening mandates, handheld point-of-care, domestic manufacturing |
| South America | 12.4% CAGR (2026–2035) | Private hospital capital expansion, teleophthalmology networks |
| Middle East & Africa | USD 0.08 Billion | Tertiary centre build-out, diabetes programme funding |
| Total | 100.0% / USD 2.08 Billion | — |
Regional distribution across the Optical Coherence Tomography Market reflects three variables: ophthalmology practice density, angiography reimbursement maturity, and interventional cardiology procedure volume.
North America
| Country | Metric | Key Driver |
| US | 87.1% of region | Dedicated OCTA billing code and dense retina practice networks |
| Canada | USD 0.06 Billion | Provincial diabetic screening expansion |
| Mexico | 12.8% CAGR | Private hospital ophthalmology investment |
Regulatory throughput underpins United States leadership in the Optical Coherence Tomography Market. The FDA cleared Topcon's Maestro2 platform together with its IMAGEnet 6 data system, extending indications across posterior and anterior ocular structures with an embedded normative database [10]. ZEISS added indocyanine green angiography functionality to its cleared ultra-widefield system in April 2025 [8]. Canon's USD 50 million commitment to a Cleveland imaging research centre signals that manufacturers view North America as the venue for algorithm development, not merely distribution [11].
Europe
| Country | Metric | Key Driver |
| Germany | 23.4% of region | Interventional cardiology imaging protocols |
| UK | USD 0.11 Billion | NHS Long Term Plan community optometry rollout |
| France | 14.1% of region | Hospital ophthalmology modernisation |
| Italy | 11.3% of region | Ageing population and AMD prevalence |
| Spain | 9.2% of region | Private clinic network expansion |
| Nordic Countries | 8.6% of region | Integrated electronic health record imaging |
| Russia | 5.1% of region | Domestic tertiary centre procurement |
| Rest of Europe | 12.6% of region | Central and Eastern European catch-up investment |
Britain offers the clearest policy case. NHS initiatives have widened scan availability specifically in community optometry settings, moving diagnostic capture upstream of hospital eye departments and easing referral backlogs. Primary eye-care practitioners integrating imaging into routine examination have become a distinct purchasing channel — smaller order sizes, higher unit counts, and different feature priorities than tertiary retina services. German demand skews the other way, driven by catheter-lab adoption of intravascular imaging protocols following European trial participation [1].
Asia-Pacific
| Country | Metric | Key Driver |
| China | 34.8% of region | National diabetic retinopathy screening and domestic device manufacturing |
| India | 15.9% CAGR | Tier-two city hospital expansion, high diabetes prevalence |
| Japan | 21.2% of region | Interventional cardiology imaging leadership |
| South Korea | 9.4% of region | Advanced hospital imaging infrastructure |
| ASEAN | USD 0.07 Billion | Teleophthalmology and mobile screening units |
| Rest of Asia-Pacific | 6.1% of region | Public health screening pilots |
Asia-Pacific is where the Optical Coherence Tomography Market changes shape rather than merely scales. Chinese manufacturers are advancing cost-optimised systems aimed squarely at emerging-market price points, compressing margins for incumbent platforms in the mid-tier [14]. Japan contributes differently — its interventional cardiology community was an early and heavy adopter of catheter-based imaging, and Japanese sites featured prominently in the ILUMIEN IV enrolment [1]. India's growth rests on volume: the diabetic population creates screening demand no specialist workforce can meet without automated triage.
South America
| Country | Metric | Key Driver |
| Brazil | 58.3% of region | Private hospital network capital expenditure |
| Argentina | 17.6% of region | Urban ophthalmology clinic modernisation |
| Rest of South America | 24.1% of region | Regional teleophthalmology programmes |
Brazilian demand concentrates in São Paulo and Rio de Janeiro private hospital groups, where competitive positioning around diagnostic sophistication justifies premium platform purchases. Public-sector procurement moves considerably slower and favours refurbished or entry-tier systems. Currency volatility remains the principal commercial obstacle for import-dependent buyers, pushing several distributors toward local-currency leasing structures.
Middle East & Africa
| Country | Metric | Key Driver |
| Saudi Arabia | 31.2% of region | Vision 2030 healthcare infrastructure programme |
| UAE | 24.7% of region | Medical tourism positioning and tertiary specialisation |
| South Africa | 16.4% of region | Private hospital group standardisation |
| Egypt | 11.8% of region | Diabetes screening initiatives |
| Rest of MEA | 15.9% of region | Donor-funded eye-health programmes |
Gulf state procurement behaves unlike the rest of the region — flagship hospitals specify top-tier multimodal platforms and treat diagnostic capability as a competitive asset in attracting international patients. Sub-Saharan demand runs on entirely different economics, dominated by handheld systems deployed through non-governmental screening programmes and constrained more by trained reader availability than by device supply.
Optical Coherence Tomography Market Segmentation
Segment structure within the Optical Coherence Tomography Market follows five dimensions: device type, technology, modality, end user, and sales channel.
By Device Type
| Segment | Metric (2025) | Primary Demand Driver |
| Table-Top OCT Devices | 44.6% share | Specialist clinic and hospital standard of care |
| Hand-Held OCT Devices | 13.8% CAGR | Neonatal, paediatric, and intraoperative access |
| Catheter-Based OCT Devices | USD 0.39 Billion | Complex percutaneous coronary intervention |
| Doppler OCT Devices | 6.2% share | Flow assessment in research and specialty settings |
Tabletop platforms remain the revenue anchor because they carry the angiography modules, normative databases, and multimodal imaging that specialists require. Handheld systems tell the more interesting growth story — they open clinical settings physically inaccessible to chinrest-based instruments, including neonatal intensive care and the operating theatre, and they are the entry vector into markets that cannot fund tabletop capital [16].
By Technology
| Segment | Metric (2025) | Primary Demand Driver |
| Spectral-Domain OCT | 46.8% share | Installed-base standard across retina and glaucoma |
| Swept-Source OCT | 14.9% CAGR | Deeper choroidal penetration and faster acquisition |
| Time-Domain OCT | USD 0.19 Billion | Legacy installed base, declining |
Spectral-domain holds the largest position by installed base, but swept-source is where new purchase decisions are landing. Longer-wavelength sources penetrate beneath the retinal pigment epithelium, resolving choroidal structure that spectral-domain systems approximate at best. Vendors have pushed scan speeds aggressively as a result, and the resulting acquisition-time reduction is a workflow argument as much as an image-quality one.
By Modality
| Segment | Metric (2025) | Primary Demand Driver |
| Structural OCT | 61.3% share | Core cross-sectional retinal layer measurement |
| OCT-Angiography (OCT-A) | 15.4% CAGR | Non-invasive vascular visualisation, new billing pathway |
| Functional / Polarisation-Sensitive OCT | USD 0.11 Billion | Research and emerging tissue-characterisation use |
Angiography is the modality reshaping purchase criteria. It visualises perfused vasculature without dye injection, removing the patient risk and chair time that fluorescein angiography imposes. Heidelberg's cleared module cut acquisition time by half through variable scan-speed technology, addressing the workflow objection that had slowed routine adoption [7]. Reimbursement recognition in 2025 removed the remaining commercial barrier [16].
By End User
| Segment | Metric (2025) | Primary Demand Driver |
| Hospitals & Tertiary Care Centres | 42.7% share | Multimodal platform requirements and cardiology integration |
| Specialty Clinics & Ambulatory Surgery Centres | USD 0.68 Billion | High-throughput retina and glaucoma practice |
| Research & Academic Institutes | 9.1% share | Novel modality development and clinical trial endpoints |
| Others | 7.5% share | Optometry, industrial, and veterinary applications |
Hospitals and Tertiary Care Centres dominate the end-user landscape, holding a leading share of 42.7% driven by multimodal platform requirements and cardiology integration. Specialty Clinics and Ambulatory Surgery Centres follow closely at USD 0.68 Billion, while Research & Academic Institutes and Others account for 9.1% and 7.5% shares respectively.
By Sales Channel
| Segment | Metric (2025) | Primary Demand Driver |
| Direct Sales | 68.9% share | Service contracts and software licensing attachment |
| Distributors / Third-Party | 12.9% CAGR | Emerging-market reach and mid-tier pricing |
Direct Sales dominate the sales channel landscape, securing the largest share at 68.9%, driven by service contracts and software licensing attachments. Meanwhile, Distributors and Third-Party channels expand as a key growth avenue, registering a compound annual growth rate of 12.9% to scale emerging-market reach and mid-tier pricing strategies.
Competitive Benchmarking
The Optical Coherence Tomography Market carries medium concentration — the top five vendors hold roughly 55–62% of revenue, implying an HHI in the 900–1,200 range. Structure is best described as tiered rather than fragmented: two global leaders, a competitive second tier of specialist ophthalmic firms, and a distinct cardiology segment where the ophthalmology names barely compete. Chinese entrants are pressuring the mid-tier on price.
| Company | Est. Revenue Share Range | Key Offerings for Optical Coherence Tomography Market | Strategic Positioning |
| Carl Zeiss Meditec AG | ~18–22% | Cirrus 6000, PLEX Elite 9000, AngioPlex, PathFinder decision support | Category leader; largest normative database and integrated ecosystem |
| Topcon Corporation | ~13–16% | Maestro2, Triton swept-source, IMAGEnet 6 | Workflow automation and multi-device pretesting integration |
| Heidelberg Engineering GmbH | ~9–12% | Spectralis multimodal platform, OCTA Module with SHIFT | Image-quality leadership; modular upgrade economics |
| Abbott Laboratories | ~8–11% | OPTIS Next imaging systems, Ultreon software, Dragonfly catheters | Dominant in intravascular cardiology imaging |
| NIDEK Co., Ltd. | ~5–7% | Retina Scan Duo, Mirante multimodal | Mid-tier value positioning, strong Asia-Pacific channel |
| Canon Inc. / Canon Medical | ~4–6% | Xephilio swept-source series | Research investment in AI-enabled imaging |
| Visionix (Optovue) | ~3–5% | Avanti, Solix full-range angiography | Angiography specialisation and optometry channel |
| Nikon Corporation (Optos) | ~3–5% | Monaco, MonacoPro ultra-widefield with OCT | Combined widefield fundus and cross-sectional capture |
| Leica Microsystems (Danaher) | ~2–4% | Intraoperative microscope-integrated systems | Surgical visualisation niche |
| Terumo Corporation | ~2–4% | Intravascular imaging consoles and catheters | Cardiology challenger, strong Japan position |
| Thorlabs Inc. | ~2–3% | Ganymede, Telesto research systems | Research and industrial OEM supply |
| OPTOPOL Technology S.A. | ~1–3% | REVO series | European value segment |
Recent News & Developments
- Abbott (August 2023): Presented ILUMIEN IV late-breaking data at ESC Congress, showing a 7% larger minimal stent area and 64% lower stent thrombosis rates under OCT-guided PCI across 2,487 patients in 18 countries — the evidence base cardiology sales teams have used since [5][1].
- Heidelberg Engineering (July 2024): Received FDA clearance for its Spectralis OCTA Module with SHIFT technology, cutting angiography acquisition time by approximately 50% and addressing the primary workflow objection to routine use [7].
- Heidelberg Engineering (October 2024): Cleared the Spectralis Flex Module, extending the platform to patients unable to use conventional chinrest positioning [6].
- Topcon (2024): Obtained FDA 510(k) clearance under K241081 for the 3D OCT-1 Maestro2 together with the IMAGEnet 6 Ophthalmic Data System, covering posterior and anterior ocular imaging with an embedded normative reference database [10].
- Optos / Nikon (February 2025): Launched MonacoPro, combining ultra-widefield scanning laser ophthalmoscopy with simultaneous cross-sectional capture in a single acquisition [16].
- Canon Medical Systems (February 2025): Committed USD 50 million to establish a medical imaging innovation hub in Cleveland, Ohio, with OCT research a stated focus [11][17].
- ZEISS (April 2025): Secured 510(k) clearance adding indocyanine green angiography to CLARUS 700, enabling standalone ICG and simultaneous fluorescein-ICG capture; showcased alongside CE-marked Cirrus PathFinder AI decision support at AAO 2025 [8][9].
- Heidelberg Engineering (June 2026): Announced FDA clearance for a Spectralis software release introducing a 250 kHz OCTA scan speed with enhanced active eye tracking and a Green Autofluorescence Module [6].
시장 하이라이트
FAQs
What service and consumable costs should buyers model beyond the purchase price of an Optical Coherence Tomography Market system?
Annual service contracts typically run 8–12% of list price, and angiography or normative-database modules are often licensed separately. Catheter-based cardiology systems carry per-procedure disposable costs that dominate lifetime spend [22].
How does OCT compare with intravascular ultrasound for guiding coronary intervention?
OCT delivers roughly ten times the axial resolution but requires blood clearance and cannot image through heavily calcified vessel walls as deeply. Randomised comparison found the two broadly equivalent on stent dimensions, with OCT favoured in bifurcation anatomy [17].
What integration obstacles do practices most often underestimate in the Optical Coherence Tomography Market?
Image file sizes strain practice networks and archives, and vendor-proprietary formats complicate migration between platforms. Cybersecurity requirements for connected imaging devices have also tightened materially since 2024 [9].
Can OCT interpretation be delegated to non-specialist staff?
Capture can be delegated after modest training, but diagnostic interpretation currently requires a qualified clinician in most jurisdictions. Automated triage software is narrowing that requirement for screening contexts, not for diagnosis [6].
Which vendor characteristics matter most when procuring in the Optical Coherence Tomography Market?
Normative database breadth and the depth of longitudinal patient history determine switching cost more than optical specifications. Practices building a decade-long patient record should weigh ecosystem lock-in as a strategic decision [9].
Is refurbished equipment a viable route for smaller clinics?
Refurbished tabletop systems can cut acquisition cost by 40–60%, but often lack current angiography modules and manufacturer software support. Verify that regulatory clearance transfers and that service coverage remains available [19].
What regulatory nuance applies to OCT devices outside ophthalmology?
Cardiology and dermatology indications require separate clearances rather than extending an ophthalmic authorisation. Breakthrough Device designations have accelerated several novel intravascular pathways, though commercial launch still follows full review [11].
저자
Author
 Nidhi Mandole
Co-Author
 Rahul Gotadki
Secondary Research
The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed medical journals, clinical publications, patent filings, and authoritative healthcare organizations. Key sources included the US Food and Drug Administration (FDA) Center for Devices and Radiological Health (CDRH) 510(k) and PMA databases, European Database on Medical Devices (EUDAMED) for MDR compliance, National Eye Institute (NEI/NIH), American Academy of Ophthalmology (AAO), American Society of Retina Specialists (ASRS), European Society of Cardiology (ESC), American College of Cardiology (ACC), Medical Imaging & Technology Alliance (MITA), World Health Organization (WHO) Global Health Observatory Vision Data, CDC National Center for Health Statistics (diabetes and chronic disease epidemiology), Centers for Medicare & Medicaid Services (CMS) reimbursement and HCPCS code databases, US Patent and Trademark Office (USPTO) and European Patent Office (EPO) for optical imaging innovations, National Center for Biotechnology Information (NCBI/PubMed) for clinical trial data, and national health ministry reports from key markets (China NMPA, Japan MHLW, India DCGI). These sources were used to collect device approval data, procedure volume statistics, clinical safety and efficacy studies, reimbursement landscapes, prevalence data for retinal diseases (AMD, diabetic retinopathy, glaucoma) and cardiovascular conditions, and technology landscape analysis for time-domain, spectral-domain, and swept-source OCT platforms.
Primary Research
Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consisted of CEOs, VPs of Product Development, Global Regulatory Affairs chiefs, Business Development directors, and Marketing executives from OCT device manufacturers, optical component suppliers (MEMS, interferometers, light sources), and regional distribution partners. Board-certified ophthalmologists (retina specialists, glaucoma specialists, cornea specialists), interventional cardiologists performing intravascular OCT, dermatologists utilizing non-invasive imaging, hospital procurement directors, ambulatory surgical center administrators, diagnostic imaging center medical directors, and principal investigators at academic research institutes comprised demand-side sources. Market segmentation was validated across tabletop, handheld, catheter-based, and Doppler OCT systems through primary research. AI-integration and swept-source technology pipeline timelines were confirmed, and clinical adoption patterns, point-of-care expansion, capital equipment procurement cycles, and reimbursement dynamics across ophthalmology and cardiology service lines were gathered based on the findings.
Primary Respondent Breakdown:
By Designation: C-level Primaries (30%), Director Level (35%), Others (35%)
By Region: North America (40%), Europe (24%), Asia-Pacific (26%), Rest of World (10%)
Market Size Estimation
Global market valuation was derived through revenue mapping, unit shipment analysis, and installed base modeling. The methodology included:
Carl Zeiss Meditec, Topcon Corporation, Heidelberg Engineering, Abbott Laboratories (St. Jude Medical), NIDEK, OPTOPOL, Thorlabs, and emerging handheld/portable device innovators are among the 35+ main manufacturers identified in North America, Europe, Asia-Pacific, and Latin America.
Product mapping across time-domain OCT (TD-OCT), spectral-domain OCT (SD-OCT), swept-source OCT (SS-OCT), full-field OCT, catheter-based intravascular OCT, handheld OCT devices, and Doppler/functional OCT systems
Analysis of reported and modeled annual revenues specific to OCT device portfolios, disaggregated by clinical (ophthalmology, cardiovascular, dermatology, oncology) and industrial (non-destructive testing, semiconductor inspection) applications
Coverage of manufacturers representing 75-80% of global market share in 2024
Extrapolation using bottom-up (procedure volume × ASP by country/unit shipments by device category) and top-down (manufacturer revenue validation and competitor share analysis) approaches to derive segment-specific valuations for tabletop, handheld, and catheter-based systems across hospital, ambulatory surgical center, specialty clinic, and research institute end-user segments
무료 샘플 다운로드
이 보고서의 무료 샘플을 받으려면 아래 양식을 작성하십시오
Customer Stories

“This is really good guys. Excellent work on a tight deadline. I will continue to use you going forward and recommend you to others. Nice job”

Noah Malgeri
Co-Founder

“Thanks for sending the report it gives us a good global view of the Betaïne market.”

Peter Groot koerkamp
Account and Business Manager

“We found the report very insightful! we found your research firm very helpful. I'm sending this email to secure our future business.”

Younghwan Choi
Senior Retail Manager

“I am very pleased with how market segments have been defined in a relevant way for my purposes (such as "Portable Freezers & refrigerators" and "last-mile"). In general the report is well structured. Thanks very much for your efforts.”

Mark Irwin
Management Consultant

“We got the report in time, we really thank you for your support in this process. I also thank to all of your team as they did a great job.”

Akif Moroglu
Strategy & Business Development Director

“The Automotive 48V ECU Components Procurement Intelligence Study” was a complex project, but the Market Research Future (MRFR) team handled it with quality, agility, and customer-centricity. They delivered all requested data on time and within the agreed scope. The team, including Shubhendra Anand and Rahul Gotadki, was always readily available to clarify questions and swiftly implement necessary adjustments, driving the project to a successful conclusion within a very demanding timeframe.
I would also like to specifically commend Akshay Agarwal for his responsiveness and support at every stage—from our initial inquiry on May 6th through to final delivery on June 18th. His dedication made the entire process seamless.”

Guilherme Gomes Martins
Product Management Director

“Thanks. It’s been a pleasure working with you, please use me as reference with any other Intel employees.”

Joseph Aguayo
Sales Operations & Pricing Manager

“Thank you, this will be very helpful for OQS.”

La Terria Dodd
Program Support Specialist

“I have been reading the first document or the study, ,the Global HVAC and FP market report 2021 till 2026. Must say, good info! I have not gone in depth at all parts, but got a good indication of the data inside!”

Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA

사례 연구
Aerospace & Defense

