Hydrogen Fuel Cell Vehicle Market (2026 - 2035)

Hydrogen Fuel Cell Vehicle (HFCV) Market Research Report By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Buses, Trucks (Medium & Heavy-Duty), Others (Material Handling)), By Technology (Proton Exchange Membrane Fuel Cell, Phosphoric Acid Fuel Cell, Solid Oxide Fuel Cell, Alkaline Fuel Cell, Others), By Driving Range (Less Than or Equal To 250 Miles, 251–500 Miles, Above 500 Miles), By Power Output (Less Than 100 kW, 100–200 kW, Above 200 kW), By End-Use Ownership (Private / Personal, Commercial Fleet, Public Transport / Government) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast to 2035
ID: MRFR/AT/3300-HCR 200 Pages Triveni Bhoyar, Sejal Akre Last Updated: September 10, 2026
Hydrogen Fuel Cell Vehicle (HFCV) Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)39.8%
2025 Market SizeUSD 3.22 Billion
2035 Market SizeUSD 89.76 Billion
Key Players
Toyota Motor Corporation
SAIC Motor Corporation
Weichai Power
Ballard Power Systems
Honda Motor Co.
Daimler Truck AG
Opportunities
  • Depot-Captive Fleet Conversion
  • Hydrogen-as-a-Service Contracting
  • Emerging-Market Corridor Development

Hydrogen Fuel Cell Vehicle Market 요약

Market Research Future 분석에 따르면, 수소 연료 전지 차량 시장 규모는 2024년에 48억 9천만 달러로 추정되었습니다. 수소 연료 전지 차량 산업은 2025년 58억 4천800만 달러에서 2035년까지 349억 9천만 달러로 성장할 것으로 예상되며, 2025 - 2035년 예측 기간 동안 연평균 성장률(CAGR)은 19.59%에 이를 것으로 보입니다.

주요 시장 동향 및 하이라이트

수소 연료 전지 차량 시장은 기술 발전과 지원 정책에 의해 상당한 성장을 할 준비가 되어 있습니다.

  • 북미는 수소 연료 전지 차량의 가장 큰 시장으로, 강력한 수요와 투자를 보여줍니다.
  • 아시아 태평양은 정부의 이니셔티브와 소비자 관심 증가에 힘입어 가장 빠르게 성장하는 지역으로 부상하고 있습니다.
  • 승용차가 시장을 지배하고 있으며, 상용차는 채택의 가장 빠른 성장을 경험하고 있습니다.
  • 환경 문제와 정부 인센티브는 주요 동력으로, 인프라 개발과 소비자 수용을 촉진하고 있습니다.

시장 규모 및 예측

2024 시장 규모 4.89 (억 달러)
2035 시장 규모 34.99 (억 달러)
CAGR (2025 - 2035) 19.59%

주요 기업

HFC 차량 산업의 주요 선도 기업으로는 Toyota (JP), Hyundai (KR), Honda (JP), Mercedes-Benz (DE), BMW (DE), Nissan (JP), General Motors (US), Ballard Power Systems (CA), Plug Power (US) 등이 있습니다.
Hydrogen Fuel Cell Vehicle Market Treiber

Environmental Concerns and Sustainability

The Hydrogen Fuel Cell Vehicle Market is increasingly driven by growing environmental concerns and the need for sustainable transportation solutions. As awareness of climate change and air pollution rises, consumers and governments alike are seeking alternatives to traditional fossil fuel vehicles. Hydrogen fuel cells produce zero emissions at the point of use, making them an attractive option for eco-conscious consumers. In 2025, the demand for hydrogen fuel cell vehicles is projected to increase significantly, with estimates suggesting a market growth rate of over 20% annually. This shift towards cleaner technologies is likely to bolster the hydrogen fuel cell vehicle market, as manufacturers respond to consumer preferences for sustainable options.

Government Incentives and Regulatory Frameworks

Government incentives and supportive regulatory frameworks play a crucial role in shaping the Hydrogen Fuel Cell Vehicle Market. Many countries are implementing policies that promote the adoption of hydrogen fuel cell vehicles through subsidies, tax breaks, and grants for research and development. For example, several nations have set ambitious targets for reducing greenhouse gas emissions, which often include the promotion of hydrogen as a clean fuel alternative. In 2025, it is anticipated that these initiatives will lead to a substantial increase in the number of hydrogen fuel cell vehicles on the road, further stimulating market growth and attracting investment in related infrastructure.

Technological Innovations in Fuel Cell Technology

Technological advancements in fuel cell technology are a pivotal driver for the Hydrogen Fuel Cell Vehicle Market. Innovations such as improved fuel cell efficiency, reduced costs, and enhanced durability are making hydrogen vehicles more competitive with battery electric vehicles. For instance, recent developments have led to fuel cells that can operate effectively at lower temperatures, which could expand their usability in various climates. Furthermore, the integration of advanced materials and manufacturing techniques is expected to lower production costs, potentially increasing market penetration. As these technologies continue to evolve, they may significantly influence consumer adoption rates and overall market dynamics.

Rising Consumer Demand for Alternative Fuel Vehicles

Infrastructure Development for Hydrogen Refueling Stations

시장 세그먼트 통찰력

The Hydrogen Fuel Cell Vehicle Market is evolving with diverse offerings among various vehicle types. Among these, passenger vehicles hold a significant share, leading in consumer preference and adoption. Commercial vehicles are emerging quickly, driven by the increasing demand for sustainable logistics and freight transport solutions. The market is thereby characterized by a competitive landscape, where innovative technologies and policy incentives further enhance share distribution among these segments. Growth trends in the Hydrogen Fuel Cell Vehicle Market are significantly influenced by supportive government regulations and clarity on emissions reductions goals. Passenger vehicles, while currently the largest segment, are being challenged by the rapid rise of commercial vehicles, which are witnessing advances in fuel cell efficiency and cost reduction strategies. This dynamic creates an environment ripe for both segments to thrive, catering to various market demands and consumer preferences.

In the Hydrogen Fuel Cell Vehicle Market, the sales channel landscape is dominated by Direct Sales, which holds the largest share due to the surge in interest from consumers seeking personalized vehicle solutions. Dealerships follow as a vital channel, especially as manufacturers leverage established networks to enhance accessibility and customer engagement. Online Sales, while growing, have not yet captured significant market share compared to these two primary channels, which are essential for driving consumer trust and personalized service. Looking ahead, the growth trends in the sales channel segment are driven by increasing consumer awareness about hydrogen fuel cell technology and its benefits. Dealerships are becoming the fastest-growing segment as they adapt to consumer preferences and offer enhanced services. Additionally, Direct Sales are witnessing steady demand due to the procurement of hydrogen vehicles through specialized platforms, while Online Sales will likely gain traction as more consumers become accustomed to digital shopping experiences for high-value items like vehicles. DOE's Loan Programs Office is providing $3 billion in federal loan guarantees for hydrogen-related projects — complementing the $9.5 billion BIL direct funding. This public financing layer de-risks private investment in hydrogen fuel cell infrastructure and production, directly accelerating the commercialisation pathway for FCEV deployment.

Hydrogen Fuel Cell Vehicle Market에 대한 더 자세한 통찰력 얻기

지역 통찰력

North America : Innovation and Investment Hub

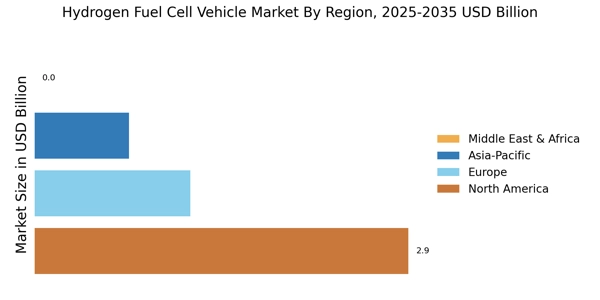
North America is poised to dominate the hydrogen fuel cell vehicle market, driven by significant investments in infrastructure and technology. The U.S. holds approximately 60% of the market share, with Canada following at around 20%. Regulatory support, such as the Infrastructure Investment and Jobs Act, aims to enhance hydrogen production and distribution, fostering a favorable environment for growth. The competitive landscape features major players like General Motors and Plug Power, alongside established automotive giants such as Toyota and Hyundai. The U.S. government is actively promoting hydrogen initiatives, which has led to increased collaboration between public and private sectors. This synergy is expected to accelerate the deployment of hydrogen fuel cell vehicles across the region.

Europe : Sustainability and Innovation Leader

Europe is rapidly emerging as a leader in the hydrogen fuel cell vehicle market, with a market share of approximately 25%. Germany and France are the largest markets, accounting for nearly 15% and 5% respectively. The European Union's Green Deal and hydrogen strategy aim to promote clean energy solutions, significantly boosting demand for hydrogen vehicles and infrastructure. Key players in this region include Mercedes-Benz and BMW, who are investing heavily in hydrogen technology. The competitive landscape is characterized by strong collaboration between automotive manufacturers and energy providers, enhancing the development of hydrogen refueling stations. This integrated approach is crucial for achieving the EU's ambitious climate goals and fostering a sustainable transport ecosystem.

Asia-Pacific : Emerging Market Potential

Asia-Pacific is witnessing rapid growth in the hydrogen fuel cell vehicle market, with Japan and South Korea leading the charge. Japan holds about 15% of the market share, while South Korea follows closely with around 10%. Government initiatives, such as Japan's Hydrogen Roadmap, are pivotal in driving demand and investment in hydrogen technologies, creating a robust market environment. The competitive landscape is dominated by key players like Toyota and Hyundai, who are at the forefront of hydrogen vehicle development. The region's focus on innovation and technology is fostering partnerships between automotive manufacturers and energy companies, enhancing the deployment of hydrogen infrastructure. This collaborative effort is essential for meeting the increasing demand for sustainable transportation solutions in Asia-Pacific.

Middle East and Africa : Resource-Rich Frontier

The Middle East and Africa region is beginning to explore the hydrogen fuel cell vehicle market, with a market share of approximately 5%. Countries like South Africa and the UAE are taking initial steps towards hydrogen adoption, driven by the need for sustainable energy solutions and diversification of their economies. Government initiatives are starting to emerge, focusing on renewable energy and hydrogen production. The competitive landscape is still developing, with local players and international companies looking to establish a foothold in the market. The presence of abundant natural resources, particularly in the Gulf region, presents significant opportunities for hydrogen production. As infrastructure develops, the region is expected to see increased interest and investment in hydrogen fuel cell technologies.

Hydrogen Fuel Cell Vehicle Market Regional Image

주요 기업 및 경쟁 통찰력

수소 연료 전지 차량 시장은 기술 발전, 환경 인식 증가, 전 세계 정부의 강력한 탄소 배출 감소 추진에 의해 촉진된 중요한 성장과 변화를 목격했습니다. 기존 화석 연료 차량에 대한 더 깨끗한 대안으로서 수소 연료 전지 차량(HFCEV)은 소비자와 제조업체 모두에게 인기를 얻고 있습니다. 이 시장에 대한 경쟁 통찰력은 연료 전지 효율성을 향상시키고 생산 비용을 줄이며 연료 인프라를 확장하기 위한 혁신, 전략적 파트너십 및 지속적인 연구 및 개발 이니셔티브로 특징지어지는 환경을 보여줍니다. 이 산업에 참여하는 기업들은 시장 존재감을 높이기 위해 강력한 전략을 구현하고 있으며, 그들의 독특한 능력과 강점을 활용하여 시장의 중요한 부분을 차지하고 있습니다.

BMW는 수소 연료 전지 차량 시장에서 중요한 진전을 이루어내며 지속 가능성과 혁신을 추진하는 주요 기업으로 자리 잡고 있습니다. 이 회사는 광범위한 자동차 엔지니어링 전문 지식을 활용하여 고급 수소 연료 전지 기술을 개발하고 이를 유명한 전기차 제품과 결합했습니다. BMW의 글로벌 존재감은 다양한 시장에서 브랜드가 널리 인식되고 신뢰받고 있다는 점에서 경쟁력을 강화합니다. 이 회사의 강점은 강력한 연구 및 개발 능력, 최첨단 기술에 대한 상당한 투자, 수소 공급망 전반에 걸친 파트너와의 강력한 협력에 있습니다. 이러한 접근 방식은 BMW가 차량 제공을 향상시키는 데 도움이 될 뿐만 아니라 자동차 산업에서 재생 가능 에너지 솔루션으로의 전환의 최전선에 남아 있도록 보장합니다.


Nikola는 수소 연료 전지 차량 시장에서 또 다른 중요한 플레이어로, 수소 동력 상업용 차량의 개척에 집중하고 있습니다. 이 회사는 주로 중형 트럭 및 관련 서비스를 통해 제로 배출 운송 솔루션에 대한 증가하는 수요를 충족하기 위해 자리를 잡고 있습니다. 혁신적인 제품 개발을 강조함으로써 Nikola는 전통적인 운송 및 물류 부문을 혁신하고자 합니다. 이 회사의 강점은 신뢰할 수 있는 수소 재충전 인프라를 개발하는 데 전념하고 있어 제공의 실용성과 매력을 높이고 있습니다. 또한 Nikola는 시장 존재감을 강화하고 성장을 가속화하기 위해 전략적 파트너십을 형성하고 인수합병에 적극적으로 참여하고 있습니다. 이러한 접근 방식은 Nikola가 시너지를 활용하고 새로운 기술 및 시장에 접근할 수 있게 하여 궁극적으로 전 세계 수소 연료 전지 차량의 경쟁 환경에서의 입지를 강화합니다.

Hydrogen Fuel Cell Vehicle Market 시장의 주요 기업은 다음과 같습니다

Recent Industry Developments

  • 2025년 3분기: 독일 100개 이상의 수소 충전소, 프랑스 70억 달러 수소 계획 발표 독일은 연료 전지 차량을 위한 100개 이상의 운영 중인 수소 재충전소를 초과했으며, 프랑스는 수소 연료 전지 차량의 채택을 가속화하고 중형 운송의 탈탄소화를 지원하기 위한 70억 달러의 국가 수소 인프라 계획을 발표했습니다.
  • 2025년 1분기: 토요타, 2025 수소 및 연료 전지 세미나에서 기술 로드맵 제공 토요타 경영진은 수소 연료 전지 차량을 위한 포괄적인 기술 로드맵을 공개하며, 수소 동력 제품 라인업 확장을 위한 회사의 의지를 재확인하고 연료 전지 혁신을 통한 탄소 중립 달성을 위한 새로운 전략을 설명했습니다.
  • 2024년 2분기: 현대, 한국에 새로운 수소 연료 전지 차량 생산 시설 개설 현대는 수소 연료 전지 차량 전용의 최첨단 제조 시설을 공식 개설하여 생산 능력을 확대하고 제로 배출 운송에 대한 증가하는 글로벌 수요를 충족할 계획입니다.
  • 2024년 2분기: 혼다와 이스즈, 수소 동력 중형 트럭 개발을 위한 파트너십 발표 혼다와 이스즈는 중형 트럭을 위한 수소 연료 전지 시스템을 공동 개발하고 상용화하기 위한 전략적 파트너십 계약을 체결하여 2025년까지 일본 및 국제 시장에 배포할 계획입니다.
  • 2025년 1분기: 니콜라, 수소 트럭 생산 확대를 위한 2억 달러 자금 조달 라운드 확보 니콜라 코퍼레이션은 북미 시장을 위한 수소 연료 전지 전기 트럭의 생산 및 배송을 가속화하기 위해 기관 투자자들이 주도하는 2억 달러의 자금 조달 라운드를 마감했습니다.
  • 2025년 2분기: 다임러 트럭과 볼보 그룹, 수소 연료 전지 시스템을 위한 합작 투자 시작 다임러 트럭과 볼보 그룹은 상업용 차량을 위한 수소 연료 전지 시스템을 개발하고 대량 생산하기 위한 합작 투자 Cellcentric을 공식 출범했으며, 첫 번째 제품은 2025년 말에 시장에 출시될 것으로 예상됩니다.
  • 2025년 1분기: 토요타, 차세대 미라이 수소 연료 전지 차량 시장 공개 토요타는 개선된 주행 거리, 더 빠른 재충전 및 고급 안전 기능을 갖춘 차세대 미라이를 소개하며 수소 연료 전지 승용차에서의 리더십을 강화했습니다.
  • 2024년 2분기: 플러그 파워, 유럽 배달 밴을 위한 수소 연료 전지 시스템 공급 계약 체결 플러그 파워는 유럽의 주요 물류 회사가 운영하는 배달 밴을 위한 수소 연료 전지 시스템을 공급하기 위한 주요 계약을 확보하여 상업용 차량 부문으로의 중요한 확장을 이루었습니다.
  • 2024년 3분기: 중국, 수소 연료 전지 차량을 위한 국가 보조금 프로그램 승인 중국 정부는 수소 연료 전지 차량의 구매 및 배치를 장려하기 위한 새로운 국가 보조금 프로그램을 승인하여 채택 및 국내 생산을 가속화할 계획입니다.
  • 2025년 2분기: BMW, 유럽 시장을 위한 수소 동력 SUV 출시 발표 BMW는 유럽 고객을 대상으로 하는 첫 번째 수소 동력 SUV의 상업적 출시를 발표하며 독일과 프랑스의 확장된 수소 재충전 인프라를 활용합니다.
  • 2025년 1분기: 발라드 파워 시스템, 철도 수소 연료 전지 통합을 위한 지멘스와 파트너십 체결 발라드 파워 시스템은 승객 철도 차량에 수소 연료 전지 기술을 통합하기 위해 지멘스 모빌리티와 파트너십을 체결했으며, 독일과 오스트리아에서 파일럿 프로젝트가 예정되어 있습니다.
  • 2024년 2분기: 제너럴 모터스, 수소 연료 전지 차량 시장 부서의 새로운 책임자 임명 제너럴 모터스는 수소 연료 전지 차량 부서를 이끌 새로운 경영진을 임명하며 수소 동력 이동 수단 솔루션에 대한 집중과 투자를 재확인했습니다.

향후 전망

Hydrogen Fuel Cell Vehicle Market 향후 전망

수소 연료 전지 차량 시장은 2025년부터 2035년까지 19.59%의 CAGR로 성장할 것으로 예상되며, 이는 기술 발전, 규제 지원 및 환경 문제의 증가에 의해 촉진됩니다.

2035년까지 시장은 상당한 성장을 이룰 것으로 예상되며, 수소 연료 전지 차량을 실행 가능한 대안으로 자리매김할 것입니다.

시장 세분화

수소 연료 전지 차량 시장 응용 전망

  • 대중 교통
  • 화물 운송
  • 개인 사용
  • 기업 차량

수소 연료 전지 차량 시장 차량 유형 전망

  • 승용차
  • 상업용 차량
  • 버스
  • 이륜차

수소 연료 전지 차량 시장 판매 채널 전망

  • 직접 판매
  • 딜러십
  • 온라인 판매

수소 연료 전지 차량 시장 연료 전지 기술 전망

  • 프로톤 교환막 연료 전지
  • 고체 산화물 연료 전지
  • 알칼리 연료 전지

보고서 범위

Parameter Detail
Market Scope Global Hydrogen Fuel Cell Vehicle Market by vehicle type, technology, driving range, power output, end-use ownership, and Region
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 39.8% (2026–2035)
Market Size Checkpoints USD 3.22 Billion (2025); USD 4.40 Billion (2026); USD 23.50 Billion (2031); USD 89.76 Billion (2035)
Fastest Growing Segments Trucks (Medium & Heavy-Duty); Above 500 Miles; Commercial Fleet
Companies Profiled 11 major suppliers and integrators
Valuation Currency USD (values in billions)
CAGR Driver Disclaimer Driver and restraint impact percentages are directional analyst estimates and are not additive components of the reported CAGR

Frequently Asked Questions

2025년 수소 연료 전지 차량 시장의 현재 가치는 얼마입니까?

수소 연료 전지 차량 시장은 2024년에 약 48.9억 달러로 평가됩니다.

2035년까지 수소 연료 전지 차량 시장의 예상 시장 가치는 얼마입니까?

시장은 2035년까지 349.9억 달러의 가치를 달성할 것으로 예상됩니다.

2025년부터 2035년까지 수소 연료 전지 차량 시장의 예상 CAGR은 얼마입니까?

시장은 2025년부터 2035년까지 19.59%의 CAGR로 성장할 것으로 예상됩니다.

수소 연료 전지 차량 시장에서 어떤 차량 유형이 선도하고 있습니까?

승용차와 상용차가 선도하는 부문으로, 2035년까지 각각 130억 달러와 80억 달러의 가치를 가질 것으로 예상됩니다.

수소 연료 전지 차량 시장의 성장을 이끄는 응용 프로그램은 무엇입니까?

대중 교통과 기업 차량이 주요 응용 프로그램으로, 2035년까지 각각 105억 달러와 99.9억 달러에 이를 것으로 예상됩니다.

시장 내에서 가장 두드러진 연료 전지 기술은 무엇입니까?

양성자 교환막 연료 전지가 시장을 지배하며, 2035년까지 175억 달러의 가치를 가질 것으로 예상됩니다.

수소 연료 전지 차량 시장에서 어떤 판매 채널이 활용되고 있습니까?

직접 판매와 온라인 판매가 중요한 채널로, 2035년까지 각각 139.9억 달러와 105.1억 달러에 이를 것으로 예상됩니다.

수소 연료 전지 차량 시장의 주요 플레이어는 누구입니까?

주요 플레이어로는 도요타, 현대, 혼다, 메르세데스-벤츠, BMW, 닛산, 제너럴 모터스, 발라드 파워 시스템즈, 플러그 파워가 있습니다.

2035년 버스 시장은 다른 차량 유형과 어떻게 비교됩니까?

버스 부문은 2035년까지 50억 달러에 이를 것으로 예상되며, 상당한 성장 잠재력을 나타냅니다.

수소 연료 전지 차량 시장의 성장이 자동차 산업에 미치는 의미는 무엇입니까?

시장의 예상 성장은 자동차 산업이 지속 가능한 에너지 솔루션으로의 변화를 암시합니다.

수소 연료 전지 차량은 어떻게 작동합니까?
FCEV는 탱크에 저장된 수소를 산소와의 전기화학 반응을 통해 전기로 변환하는 고분자 전해질 막(PEM) 연료 전지를 사용합니다. 유일한 부산물은 수증기입니다. 전기는 전기 모터에 공급되며, 회생 제동을 통해 배터리에 에너지를 회수합니다.
DOE의 수소 연료 전지 차량에 대한 비용 목표는 무엇입니까?
DOE의 US DRIVE 연료 전지 기술 팀은 자동차 연료 전지 시스템에 대해 킬로와트당 35달러를 목표로 하고 있으며(ICE 엔진과의 동등성을 위한 궁극적인 목표는 30달러/kW입니다). DOE의 수소 어스샷은 깨끗한 수소 생산 비용을 10년 이내에 킬로그램당 1달러로 줄이는 것을 목표로 하고 있습니다.
저자
Author Author Profile Triveni Bhoyar LinkedIn Senior Research Analyst
Triveni Bhoyar has over 5 years of experience in the market research industry, specializing in the Automotive and Aerospace & Defense sectors. She has contributed to 200+ reports, including numerous custom projects for leading global companies, delivering solutions to complex business challenges. Renowned for her ability to generate valuable insights, Triveni excels in addressing unique market dynamics with precision and depth. Her expertise spans market sizing, competitive intelligence, and trend analysis, enabling clients to craft data-driven growth strategies. With strong analytical rigor and a client-centric approach, she plays a pivotal role in driving impactful, strategic decision-making.
Co-Author Co-Author Profile Sejal Akre LinkedIn Senior Research Analyst
She has over 5 years of rich experience, in market research and consulting providing valuable market insights to client. Hands on expertise in management consulting, and extensive knowledge in domain including ICT, Automotive & Transportation and Aerospace & Defense. She is skilled in Go-to market strategy, industry analysis, market sizing, in depth company profiling, competitive intelligence & benchmarking and value chain amongst others.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed engineering journals, automotive publications, and authoritative energy & transportation organizations. Key sources included the US Department of Energy (DOE) Office of Energy Efficiency & Renewable Energy, US Environmental Protection Agency (EPA), National Highway Traffic Safety Administration (NHTSA), California Air Resources Board (CARB), California Fuel Cell Partnership (CaFCP), European Commission Clean Hydrogen Partnership, International Energy Agency (IEA) Global EV Outlook and Hydrogen Technology Reports, International Partnership for Hydrogen and Fuel Cells in the Economy (IPHE), International Renewable Energy Agency (IRENA), SAE International (formerly Society of Automotive Engineers), International Organization for Standardization (ISO TC 197 - Hydrogen Technologies), National Renewable Energy Laboratory (NREL), Argonne National Laboratory (ANL), Sandia National Laboratories, Hydrogen Council, Fuel Cell and Hydrogen Energy Association (FCHEA), Japan Hydrogen & Fuel Cell Promotion Council, China National Energy Administration (NEA), Korea Energy Economics Institute (KEEI), EU Eurostat Transport Database, and national energy ministry reports from key markets. These sources were used to collect vehicle deployment statistics, regulatory approval data, hydrogen station infrastructure metrics, safety certification studies, patent filings, and market landscape analysis for proton exchange membrane fuel cells (PEMFC), phosphoric acid fuel cells (PAFC), solid oxide fuel cells (SOFC), alkaline fuel cells (AFC), and vehicle categories spanning passenger cars, light commercial vehicles (LCVs), heavy commercial vehicles (HCVs), buses, and material handling equipment.


Primary Research

To gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research phase. CEOs, vice presidents of product development, chief technology officers, heads of regulatory affairs, and commercial directors from automakers, fuel cell stack producers, suppliers of hydrogen storage systems, and component suppliers were examples of supply-side sources. Fleet procurement managers, directors of public transit authorities, representatives of government energy agencies, logistics operators, fleet managers for material handling, and network developers for hydrogen stations were among the demand-side sources. In addition to verifying fuel cell technology roadmap timescales and validating market segmentation across vehicle types and power outputs, primary research also collected information on fleet adoption trends, total cost of ownership (TCO) dynamics, hydrogen pricing tactics, and infrastructure deployment schedules.

Primary Respondent Breakdown:

• By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

• By Region: North America (33%), Europe (30%), Asia-Pacific (28%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through revenue mapping and unit shipment analysis. The methodology included:

• Identification of 35+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America, encompassing automotive OEMs (passenger vehicles, commercial trucks, buses), fuel cell system integrators, and specialized industrial vehicle producers

• Product mapping across passenger cars (sedans, SUVs, hatchbacks), light commercial vehicles, heavy-duty trucks, buses & coaches, and specialized vehicles (material handling, industrial), segmented by fuel cell technology (PEMFC, PAFC, SOFC, AFC), power output (<100 kW, 100-200 kW, >200 kW), and driving range (0-250 miles, 251-500 miles, >500 miles)

• Analysis of reported and modeled annual revenues specific to fuel cell vehicle portfolios and hydrogen powertrain divisions

• Coverage of manufacturers representing 70-75% of global market share in 2024

• Extrapolation using bottom-up (unit shipment × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations, validated against hydrogen consumption data and fuel cell stack production capacities

무료 샘플 다운로드

이 보고서의 무료 샘플을 받으려면 아래 양식을 작성하십시오

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.