Contrast Media Market (2026 - 2035)

콘트라스트 미디어 시장 조사 보고서 - 2032년까지의 글로벌 전망

Forecast Period
2026-2035
CAGR
8.30%
2025 Market Size
USD 6.90 Billion
2035 Market Size
USD 15.33 Billion
Life Sciences ● Updated August 27, 2026 Report ID: MRFR/LS/0776-HCR | Pages: 90 | Author: Nidhi Mandole, Rahul Gotadki

Contrast Media Market 요약

Market Research Future 분석에 따르면, 조영제 시장 규모는 2024년 67억 4천만 달러로 평가되었으며, 시장은 2025년~2035년 예측 기간 동안 연평균 성장률(CAGR) 4.76%를 기록하며 2025년 70억 6,100만 달러에서 2035년 112억 4,000만 달러로 성장할 것으로 예상됩니다. 북미는 약 30억 3천만 달러의 수익을 창출하며 45% 이상의 점유율로 시장을 주도했습니다. 만성 질환의 유병률 증가와 고급 진단 영상 절차에 대한 수요 증가는 조영제 시장의 주요 성장 동인입니다. 의료 인프라 확장과 영상 기법의 기술 발전으로 전 세계적으로 조영제 채택이 더욱 가속화됩니다.

  • WHO에 따르면 심혈관 질환으로 인해 매년 1,790만 명이 사망하고 암으로 인해 전 세계적으로 거의 1,000만 명이 사망하는 것으로 나타났습니다. 이는 세계 최고의 사망 원인이자 영상 진단 수요가 크게 증가하는 질병입니다. OECD 보건 통계에 따르면 지난 10년 동안 회원국 전체에서 CT 스캔을 포함한 진단 영상 절차가 크게 증가했으며 대부분의 국가에서 검사량이 스캐너 가용성보다 빠르게 증가했습니다. 이는 전 세계적으로 조영제 활용의 지속적인 성장을 뒷받침하는 추세입니다. (원천:WHO — 심혈관 질환)

주요 시장 동향 및 하이라이트

조영제 시장은 기술 발전과 의료 수요 증가로 인해 상당한 성장을 이룰 준비가 되어 있습니다.

  • 북미는 고급 이미징 인프라와 높은 시술량에 힘입어 2024년에 45% 이상의 매출 점유율로 지배적 위치를 점하고 있습니다.
  • 유럽은 인구 노령화와 규제에 따른 채택에 힘입어 2024년 20억 2천만 달러 규모로 30%의 점유율을 차지합니다.
  • CT 스캔 절차는 전 세계적으로 20% 이상 증가하여 요오드화 및 가돌리늄 기반 조영제에 대한 수요가 크게 증가했습니다.
  • 유럽의 25%가 넘는 인구 노령화와 이미징 속도 증가는 강력한 지역 시장 확장을 뒷받침합니다.

시장 규모 및 예측

2024년 시장규모 6.74 (USD Billion)
2035년 시장규모 11.24 (USD Billion)
CAGR (2025 - 2035) 4.76%
2024년 지역 시장 점유율 최대 북아메리카

주요 기업

다음과 같은 회사바이엘AG(독일),GE헬스케어(미국), Bristol-Myers Squibb Company(미국), Bracco Imaging S.p.A.(IT), Fujifilm Holdings Corporation(JP), Siemens Healthineers(DE), Canon Medical Systems Corporation(JP), Hoffmann-La Roche Ltd(CH) 등이 글로벌 시장의 주요 참여자입니다.
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Contrast Media Market Treiber

Rising Incidence of Chronic Diseases

{"k"=>"만성질환 발병률 증가", "v"=>"암, 심혈관 질환, 신경 질환과 같은 만성 질환의 유병률 증가는 조영제 시장의 주요 동인입니다. 이러한 질병은 진단과 모니터링을 위해 첨단 영상기술이 필요하기 때문에 조영제에 대한 수요는 더욱 늘어날 것으로 예상됩니다.
 
최근 통계에 따르면 암 발병률이 증가할 것으로 예상되며, 이로 인해 조영제를 활용하는 MRI, CT 스캔과 같은 영상 기법에 대한 필요성이 높아질 것으로 예상됩니다. 이러한 추세는 의료 서비스 제공자가 정확한 진단 및 치료 계획을 위한 효과적인 솔루션을 추구함에 따라 조영제 시장이 성장하고 있음을 나타냅니다. 더욱이, 인구 고령화로 인해 이러한 추세가 더욱 악화될 가능성이 있습니다. 노인들이 만성 질환에 더 취약해 의료 영상에서 조영제에 대한 수요가 더욱 촉진될 가능성이 있기 때문입니다."}

Increase in Diagnostic Imaging Procedures

{"k"=>"진단 영상 절차의 증가", "v"=>"진단 영상 절차의 증가는 조영제 시장의 중요한 동인입니다. 의료 시스템이 정확한 진단을 위해 점점 더 영상화에 의존함에 따라 조영제에 대한 수요가 증가할 가능성이 높습니다. 보고서에 따르면 매년 수행되는 CT 및 MRI 스캔 수가 급증했으며 이는 보다 포괄적인 진단 접근 방식으로의 전환을 반영합니다.
 
이러한 증가는 조기 질병 발견의 중요성에 대한 인식이 높아지고 이러한 절차를 용이하게 하는 영상 기술의 발전에 기인합니다. 결과적으로, 의료 서비스 제공자가 고품질 조영제 사용을 통해 영상 연구의 효율성을 향상시키려고 함에 따라 시장은 성장할 준비가 되어 있습니다. 이러한 추세는 현대 진단 관행에서 조영제의 필수적인 역할을 강조합니다."}

Growing Awareness of Preventive Healthcare

{"k"=>"예방 의료에 대한 인식 증가", "v"=>"예방 의료에 대한 강조가 증가함에 따라 진단 영상에 대한 수요가 증가하여 조영제 시장에 영향을 미치고 있습니다. 환자와 의료 서비스 제공자가 조기 발견 및 개입의 중요성을 인식함에 따라 조영제가 필요한 영상 기술의 활용이 높아질 가능성이 높습니다.
 
교육 캠페인과 공중 보건 이니셔티브는 예방 치료 문화를 조성하여 고급 영상 촬영이 포함된 정기 건강 검진을 원하는 개인이 늘어나고 있습니다. 이러한 추세는 영상 연구의 품질을 향상시키는 데 중요한 역할을 하기 때문에 조영제에 대한 수요를 증가시킬 것으로 예상됩니다. 결과적으로 시장은 조기 진단과 치료를 우선시하는 예방 의료 관행으로의 광범위한 변화에 맞춰 성장할 수 있는 위치에 있습니다."}

Technological Innovations in Imaging Techniques

{"k"=>"이미징 기술의 기술 혁신", "v"=>"이미징 방식의 기술 발전은 조영제 시장에 큰 영향을 미치고 있습니다. 3D 이미징, 하이브리드 이미징 시스템, 향상된 MRI 기술과 같은 혁신으로 인해 고급 조영제의 채택이 촉진되고 있습니다. 이러한 기술은 진단 정확도와 환자 결과를 향상시켜 조영제 활용도를 높입니다.
 
예를 들어,가돌리늄기반 조영제는 MRI 영상에 혁명을 일으켜 더 선명한 이미지와 더 나은 진단 기능을 제공합니다. 의료 시설이 영상 품질을 향상시키기 위해 정교한 조영제가 필요한 최첨단 영상 기술에 투자함에 따라 조영제 시장은 확대될 것으로 예상됩니다. 이러한 추세는 발전하는 의료 영상 환경에 적응하면서 조영제 부문의 강력한 성장 궤적을 시사합니다."}

Regulatory Support for Advanced Imaging Solutions

{"k"=>"고급 이미징 솔루션에 대한 규제 지원", "v"=>"규제 기관은 점점 더 고급 이미징 솔루션의 개발 및 승인을 지원하고 있으며 이는 조영제 시장에 긍정적인 영향을 미치고 있습니다. 새로운 조영제 및 이미징 기술에 대한 승인 프로세스를 가속화하기 위한 계획은 혁신을 촉진하고 시장 성장을 강화할 가능성이 높습니다. 예를 들어, 규제 기관은 새로운 조영제에 대한 더 빠른 접근을 촉진하는 프레임워크를 도입하여 의료 서비스 제공자가 이미징의 최신 발전을 활용할 수 있도록 보장했습니다.
 
이러한 규제 지원은 연구 개발을 장려할 뿐만 아니라 최첨단 진단 도구에 대한 환자의 접근성을 향상시킵니다. 결과적으로 시장은 더욱 유리한 규제 환경의 혜택을 누리고 의료 전문가의 진화하는 요구를 충족하는 혁신적인 제품의 도입을 촉진할 것으로 예상됩니다."}

지역 통찰력

북미 : 혁신과 수요를 선도

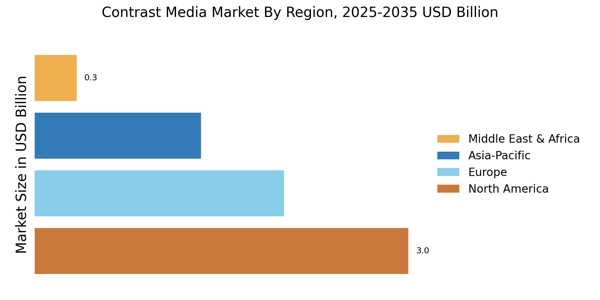
북미는 조영제 시장 규모에서 선두를 달리고 있으며 2024년 전 세계 매출의 45% 이상을 차지했습니다. 이 지역의 성장은 첨단 의료 인프라, 만성 질환의 유병률 증가, 진단 영상에 대한 수요 증가에 의해 주도됩니다. FDA와 같은 기관의 규제 지원은 시장 확장을 더욱 촉진하여 조영제 제품의 안전성과 효능을 보장합니다.

  • CDC는 1억 2,900만 명 이상의 미국인이 적어도 하나의 만성 질환을 앓고 있으며, 미국에서 영상 촬영 절차가 연간 8,000만 건을 초과한다고 보고합니다. 이러한 높은 진단량은 병원과 진단 센터 전체에서 조영제 수요를 크게 증가시킵니다. (원천:CDC / 만성 질환 예방 — 미국의 만성 질환 유병률)

미국은 의료 기술과 연구에 상당한 투자를 하는 주요 기여국입니다. GE Healthcare 및 Bristol-Myers Squibb과 같은 주요 기업은 혁신적인 솔루션과 파트너십에 중점을 두고 이 시장에서 두각을 나타내고 있습니다. 경쟁 환경은 이미징 기술의 지속적인 발전, 환자 결과 향상 및 시장 성장 촉진을 특징으로 합니다.

유럽: 규제 체계 및 성장

유럽 ​​조영제 시장 규모는 2024년 기준 20억 2천만 달러로 평가되어 30% 점유율로 두 번째로 큰 지역 시장이 되었습니다. 이 지역은 의료 제품의 고품질 표준을 보장하는 엄격한 규제 체계의 혜택을 받고 있습니다. 의료 인프라에 대한 투자 증가와 인구 노령화 증가가 수요의 주요 동인입니다.

  • WHO 유럽에 따르면 인구의 약 25%가 60세 이상이며, 만성질환으로 인한 사망자가 86% 이상입니다. 또한 EU 국가 전체에서 영상 활용도가 약 18% 증가하여 조영제 수요 증가를 뒷받침했습니다.

독일, 프랑스 등의 국가는 유리한 상환 정책과 기술 발전을 바탕으로 시장을 선도하고 있습니다. 독일은 Bayer AG 및 Siemens Healthineers와 같은 기업의 상당한 기여를 통해 주요 국가로 두각을 나타내고 있습니다. 핵심 기업 간의 혁신과 협력에 중점을 두고 경쟁 환경이 견고합니다. 유럽 ​​시장에서도 고급 이미징 기술의 채택이 증가하고 있으며, 이는 조영제 부문의 성장을 더욱 촉진하고 있습니다.

아시아 태평양: 신흥 시장 잠재력

아시아 태평양 지역은 조영제 시장에서 신흥 강자로 전 세계 점유율의 약 20%를 차지합니다. 의료비 지출 증가, 진단 영상에 대한 인식 증가, 환자 인구 증가로 인해 이 지역의 성장이 가속화되고 있습니다. 중국과 인도 같은 국가는 의료 인프라와 기술에 막대한 투자를 하며 선두에 있습니다.

규제 기관은 또한 시장 성장을 지원하기 위해 프레임워크를 강화하고 있습니다. 중국은 고급 이미징 기술에 대한 수요 급증으로 인해 이 지역에서 가장 큰 시장입니다. Fujifilm Holdings 및 Canon Medical Systems와 같은 주요 업체는 현지 요구에 맞는 혁신적인 제품에 중점을 두고 입지를 확대하고 있습니다. 빠르게 성장하는 이 부문의 시장 점유율이 혼합되면서 경쟁 환경이 진화하고 있습니다.

중동 및 아프리카: 아직 개척되지 않은 시장 기회

중동 및 아프리카 지역은 성장하는 조영제 시장을 대표하며 전 세계 점유율의 약 5%를 차지합니다. 이러한 성장은 의료 투자 증가, 진단 영상에 대한 인식 증가, 인구 증가에 의해 주도됩니다. 남아프리카 공화국 및 UAE와 같은 국가는 의료 접근성과 품질을 향상시키기 위한 정부 이니셔티브의 지원을 받아 시장을 선도하고 있습니다.

남아프리카공화국은 의료 인프라와 기술 향상에 중점을 두고 있는 핵심 국가입니다. 경쟁 환경에는 현지 기업과 국제 기업이 모두 포함되며 파트너십과 협업이 점점 더 강조되고 있습니다. 지역이 계속 발전함에 따라 고급 이미징 솔루션에 대한 수요가 증가할 것으로 예상되며 이는 시장 참여자에게 상당한 기회를 제공할 것입니다.

Contrast Media Market Regional Image

Contrast Media Market 시장의 주요 기업은 다음과 같습니다

향후 전망

Contrast Media Market 향후 전망

보고서 범위

Parameter Detail
Market Scope Global Contrast Media Market by product type, modality, route of administration, application, end user and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 8.30% (2026–2035)
Market Size Checkpoints USD 6.90 Billion (2025); USD 7.48 Billion (2026); USD 15.33 Billion (2035)
Fastest Growing Segments Microbubble & emerging agents; oncology imaging; diagnostic imaging centres; Asia-Pacific
Companies Profiled 11 suppliers including GE HealthCare, Bayer, Bracco, Guerbet, Lantheus, Fujifilm
Valuation Currency USD Billion

시장 하이라이트

FAQs

What procurement structure gives hospitals the best leverage in the Contrast Media Market?
Multi-year committed-volume contracts with dual-sourced qualification clauses. Sites that pre-qualify a secondary supplier avoid the 9–14 month requalification lag that turned the 2022 disruption into rationing [7].
Should buyers evaluate contrast agents separately from injector systems?
No. Bundled injector-plus-agent agreements now determine total protocol cost more than per-millilitre pricing, and unbundling typically forfeits dose-software access [6].
How do macrocyclic and linear gadolinium chelates compare for procurement decisions?
Macrocyclic chelates show markedly lower retention and dominate current European purchasing policy. Linear agents remain restricted or withdrawn in several jurisdictions, making them a compliance liability rather than a savings option [9].
What integration challenges arise when deploying dose-tracking software?
Interfacing injector telemetry with existing PACS and RIS environments is the common bottleneck. Facilities without HL7 or DICOM structured-dose support usually need middleware before registry reporting works [5].
Which regulatory nuance most affects new entrants in the Contrast Media Market?
Reference-listed drug equivalence for imaging agents demands comparative imaging performance data, not bioequivalence alone. That evidentiary bar lengthens filings well beyond conventional generic timelines [8].
Is photon-counting CT a threat or an opportunity for suppliers?
Both. Lower iodine loading reduces volume per scan, but reformulated low-concentration products command premium positioning, protecting revenue per procedure [11].
Where are the strongest investment returns in the Contrast Media Market outside mature economies?
ASEAN and Gulf private hospital networks. Both combine rising insured populations with rapid scanner installation and fewer entrenched supply contracts than Western systems [12].      
저자
Author
Author Profile
Nidhi Mandole LinkedIn Senior Research Analyst
She is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Nidhi is comfortably versed in data centric research backed by healthcare educational background. She leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. Her key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, she showcases extensive affinity towards learning new skills and remain fascinated in implementing them.
Co-Author
Co-Author Profile
Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed radiology journals, clinical publications, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA) Center for Drug Evaluation and Research, European Medicines Agency (EMA) Committee for Medicinal Products for Human Use, International Atomic Energy Agency (IAEA) Radiation Safety Reports, Radiological Society of North America (RSNA.org), European Society of Radiology (ESR), American College of Radiology (ACR), Society of Interventional Radiology (SIR), National Institutes of Health (NIH) Clinical Imaging Trials Database, National Center for Biotechnology Information (NCBI/PubMed), World Health Organization (WHO) Essential Medicines List, Organisation for Economic Co-operation and Development (OECD) Health Statistics, European Observatory on Health Systems and Policies, and national pharmaceutical regulatory authorities from key markets. These sources were used to collect imaging procedure statistics, regulatory approval data for new molecular entities, post-market safety surveillance (pharmacovigilance) studies, radiology workforce demographics, and diagnostic imaging infrastructure analysis for iodinated contrast agents, gadolinium-based contrast media, and barium-based formulations.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consisted of CEOs, VPs of Global Imaging, managers of regulatory affairs for pharmaceutical diagnostics, and commercial directors from contrast media manufacturers and contrast injector/device OEMs. Demand-side sources included hospital pharmacy directors, procurement leads from diagnostic imaging centers, Chiefs of Radiology from academic medical centers, and clinical specialists from catheterization laboratories. Board-certified radiologists, interventional cardiologists, and neuroradiologists were also included. Primary research has confirmed the product pipeline timelines for next-generation macrocyclic gadolinium agents and low-osmolar iodinated compounds, validated market segmentation across imaging modalities, and gathered insights on clinical adoption patterns following safety alerts, volume-based procurement strategies, and diagnostic imaging reimbursement dynamics under hospital payment systems.

Primary Respondent Breakdown:

By Designation: C-level Executives (32%), Director Level (30%), Others (38%)

By Region: North America (38%), Europe (25%), Asia-Pacific (28%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through revenue mapping and diagnostic imaging procedure volume analysis. The methodology included:

Identification of 40+ key manufacturers and pharmaceutical diagnostics divisions across North America, Europe, Asia-Pacific, and Latin America

Product mapping across iodinated contrast media (ionic vs. non-ionic, high-osmolar vs. low-osmolar), gadolinium-based contrast agents (macrocyclic vs. linear), barium sulfate formulations, and emerging nanoparticle-based contrast technologies

Analysis of reported and modeled annual revenues specific to contrast media and radiopharmaceutical portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (imaging procedure volume × ASP by country/region × contrast utilization rates) and top-down (manufacturer revenue validation and pharmaceutical diagnostics segment reporting) approaches to derive segment-specific valuations across X-ray/CT, MRI, and ultrasound contrast categories

무료 샘플 다운로드

이 보고서의 무료 샘플을 받으려면 아래 양식을 작성하십시오

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.