상업용 디스플레이 시장

상업용 디스플레이 시장 조사 보고서 디스플레이 유형별 (LCD, LED, OLED, PDP, 프로젝션), 응용 프로그램별 (소매, 의료, 기업, 교육, 환대), 최종 사용자별 (기업, 소비자, 정부 기관), 크기별 (32인치 미만, 32~55인치, 55~85인치, 85인치 이상) 및 지역별 (북미, 유럽, 남미, 아시아 태평양, 중동 및 아프리카) - 2035년까지의 예측
ID: MRFR/SEM/27081-HCR 100 Pages Ankit Gupta Last Updated: October 05, 2026
Commercial Display Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)5.9%
2024 Market Size$ 53.7 Billion
2025 Market Size$ 56.87 Billion
2035 Market Size$ 100.89 Billion
Key Players
Samsung Electronics
LG Electronics
Sony Corporation
Sharp Corporation
Panasonic Corporation
NEC Corporation
Opportunities
  • Advancements in Display Technology
  • Rising Focus on Customer Experience
  • Increasing Demand for Digital Signage

상업용 디스플레이 시장 요약

MRFR 분석에 따르면, 상업용 디스플레이 시장 규모는 2024년에 537억 달러로 추정되었습니다. 상업용 디스플레이 산업은 2025년 5687억 달러에서 2035년까지 1008억 달러로 성장할 것으로 예상되며, 2025년부터 2035년까지의 예측 기간 동안 연평균 성장률(CAGR)은 5.9%입니다.

주요 시장 동향 및 하이라이트

상업용 디스플레이 시장은 변화하는 소비자 기대에 의해 주도되는 인터랙티브 및 스마트 기술로의 역동적인 전환을 경험하고 있습니다.

  • 인터랙티브 디스플레이의 등장은 다양한 분야에서 고객 참여 전략을 재편하고 있습니다.
  • 스마트 기술의 통합이 점점 더 보편화되고 있으며, 기능성과 사용자 경험을 향상시키고 있습니다.
  • 지속 가능성이 주목받고 있으며, 제조업체들은 친환경 소재와 에너지 효율적인 솔루션에 집중하고 있습니다.
  • 디지털 사이니지에 대한 수요 증가와 디스플레이 기술의 발전은 특히 소매 및 의료 부문에서 주요 동력입니다.

시장 규모 및 예측

2024 Market Size 53.7 (USD 억)
2035 Market Size 100.89 (USD 억)
CAGR (2025 - 2035) 5.9%

주요 기업

삼성전자 (KR), LG전자 (KR), 소니 주식회사 (JP), 샤프 주식회사 (JP), 파나소닉 주식회사 (JP), NEC 주식회사 (JP), 뷰소닉 주식회사 (US), 벤큐 주식회사 (TW), 엡손 주식회사 (JP), 델 테크놀로지스 (US)

상업용 디스플레이 시장 Treiber

Advancements in Display Technology

Rising Focus on Customer Experience

Increasing Demand for Digital Signage

The Commercial Display Market experiences a notable surge in demand for digital signage solutions. Businesses across various sectors, including retail, hospitality, and transportation, increasingly adopt digital displays to enhance customer engagement and streamline communication. According to recent data, the digital signage segment is projected to grow at a compound annual growth rate of approximately 8.5% over the next five years. This growth is driven by the need for dynamic content delivery and the ability to update information in real-time, which traditional static displays cannot provide. As companies seek to differentiate themselves in competitive markets, the integration of digital signage into their marketing strategies becomes essential, thereby propelling the Commercial Display Market forward.

Government Initiatives and Regulations

Expansion of Retail and Advertising Sectors

시장 세그먼트 통찰력

The Commercial Display Market is witnessing a significant shift in preference towards various display technologies. Among these, LED displays command the largest market share due to their energy efficiency, longevity, and versatility in various applications. LCD displays remain important but are gradually losing ground to more advanced technologies such as OLED and projection, which are gaining traction, particularly in high-end applications. These changes reflect evolving customer preferences for quality, resolution, and innovative display solutions. Growth trends in the Commercial Display Market are being driven by technological advancements and increasing demand for high-quality visual experiences. OLED displays are emerging as the fastest-growing segment, favored for their superior image quality and design flexibility. Additionally, the rise of digital signage and interactive displays in retail and corporate settings is further fueling innovations in display technologies, making them more accessible to a wider audience.

상업용 디스플레이 시장에 대한 더 자세한 통찰력 얻기

지역 통찰력

북미 : 기술 채택 리더

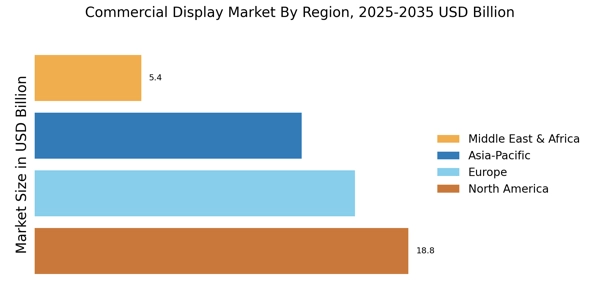
북미는 디지털 사이니지 및 고급 디스플레이 기술에 대한 수요 증가에 힘입어 상업용 디스플레이 시장에서 강력한 성장을 목격하고 있습니다. 이 지역은 전 세계 시장 점유율의 약 35%를 차지하여 가장 큰 시장이 되고 있습니다. 디지털 혁신 이니셔티브에 대한 규제 지원은 이 성장을 더욱 촉진하고 있으며, 기업들은 고객 참여를 향상시키기 위해 고품질 디스플레이 솔루션에 점점 더 많은 투자를 하고 있습니다. 미국과 캐나다는 이 지역의 주요 국가로, 삼성전자, LG전자, 델 테크놀로지스와 같은 주요 기업들이 시장을 지배하고 있습니다. 경쟁 환경은 지속적인 혁신과 주요 기업 간의 전략적 파트너십으로 특징지어지며, 변화하는 소비자 요구를 충족하기 위해 다양한 제품과 서비스를 보장합니다.

유럽 : 신흥 디지털 사이니지 허브

유럽은 디지털 사이니지 및 스마트 시티 이니셔티브에 대한 투자 증가에 힘입어 상업용 디스플레이 시장에서 중요한 플레이어로 부상하고 있습니다. 이 지역은 전 세계 시장 점유율의 약 30%를 차지하여 두 번째로 큰 시장이 되고 있습니다. 디지털 혁신과 지속 가능성을 촉진하는 규제 프레임워크는 성장을 위한 주요 촉매제로, 기업들이 향상된 커뮤니케이션 및 광고를 위해 고급 디스플레이 기술을 채택하도록 장려하고 있습니다. 유럽의 주요 국가로는 독일, 영국, 프랑스가 있으며, 소니 코퍼레이션과 샤프 코퍼레이션과 같은 기업들이 상당한 기여를 하고 있습니다. 경쟁 환경은 기존 기업과 혁신적인 스타트업이 혼합되어 있으며, 기술 발전과 고객 중심 솔루션을 위한 역동적인 환경을 조성하고 있습니다.

아시아 태평양 : 빠르게 성장하는 시장

아시아 태평양은 도시화, 기술 발전 및 소비자 지출 증가에 힘입어 상업용 디스플레이 시장에서 빠른 성장을 경험하고 있습니다. 이 지역은 전 세계 시장 점유율의 약 25%를 차지하며, 중국과 일본이 선두를 달리고 있습니다. 디지털 인프라 및 스마트 시티 프로젝트를 촉진하는 정부의 이니셔티브는 중요한 성장 동력으로 작용하고 있으며, 기업들은 다양한 응용 프로그램을 위해 고품질 디스플레이 솔루션에 투자하도록 유도하고 있습니다. 중국은 이 지역에서 가장 큰 시장이며, 일본과 한국이 뒤를 잇고 있으며, 파나소닉 코퍼레이션과 NEC 코퍼레이션과 같은 주요 기업들이 두드러진 존재감을 보이고 있습니다. 경쟁 환경은 공격적인 가격 전략과 지속적인 혁신으로 특징지어지며, 기업들은 고급 제품 제공 및 향상된 고객 경험을 통해 시장 점유율을 확보하기 위해 노력하고 있습니다.

중동 및 아프리카 : 신흥 시장 잠재력

중동 및 아프리카 지역은 인프라 및 디지털 혁신 이니셔티브에 대한 상당한 투자에 힘입어 상업용 디스플레이 시장에서 신흥 잠재력을 목격하고 있습니다. 이 지역은 전 세계 시장 점유율의 약 10%를 차지하며, UAE와 남아프리카 공화국이 선두를 달리고 있습니다. 스마트 시티 프로젝트 및 디지털 사이니지 솔루션에 대한 정부 지원은 성장을 촉진하고 있으며, 기업들은 고급 디스플레이 기술을 통해 가시성과 고객 참여를 향상시키고자 합니다. UAE에서는 빠른 도시화와 관광에 대한 집중이 상업용 디스플레이에 대한 수요를 촉진하고 있으며, 남아프리카 공화국은 소매 및 기업 부문에서 성장을 보고 있습니다. 경쟁 환경은 지역 및 국제 기업 모두를 포함하고 있으며, 뷰소닉 코퍼레이션과 벤큐 코퍼레이션과 같은 기업들이 시장 확장에 주목할 만한 기여를 하고 있습니다.

상업용 디스플레이 시장 Regional Image

주요 기업 및 경쟁 통찰력

The Commercial Display Market is currently characterized by a dynamic competitive landscape, driven by rapid technological advancements and evolving consumer preferences. Key players such as Samsung, LG, and Sony are leveraging commercial LED screens, commercial LCD, and commercial flat panel displays to strengthen their positions. Samsung Electronics (South Korea) focuses on expanding its portfolio of high-resolution displays, while LG Electronics (South Korea) emphasizes OLED technology to cater to premium segments. Sony Corporation (Japan) is increasingly investing in immersive display solutions, indicating a shift towards experiential marketing. Collectively, these strategies not only enhance their competitive edge but also shape the market's trajectory towards more sophisticated display solutions. In terms of business tactics, companies are increasingly localizing manufacturing to mitigate supply chain disruptions and optimize operational efficiency. The market appears moderately fragmented, with a mix of established players and emerging competitors. This fragmentation allows for diverse offerings, yet the collective influence of major players like NEC Corporation (Japan) and Panasonic Corporation (Japan) remains significant, as they continue to innovate and adapt to market demands.
In August LG Electronics (South Korea) announced the launch of its new line of transparent OLED displays aimed at retail environments. This strategic move is likely to enhance customer engagement by providing visually striking advertising solutions. The introduction of such innovative products not only positions LG as a leader in display technology but also reflects a broader trend towards integrating advanced features into commercial displays.
In September Sony Corporation (Japan) unveiled its latest series of interactive displays designed for educational institutions. This initiative underscores Sony's commitment to enhancing learning experiences through technology. By targeting the education sector, Sony is diversifying its market reach and aligning its offerings with the growing demand for interactive learning tools, which could potentially lead to increased market share in this niche.
In July Samsung Electronics (South Korea) entered a strategic partnership with a leading software company to develop AI-driven display solutions. This collaboration aims to enhance user experience through personalized content delivery. The integration of AI into display technology signifies a pivotal shift towards smarter, more responsive commercial displays, which may redefine customer interactions and engagement strategies in various sectors.
As of October the competitive trends in the Commercial Display Market are increasingly defined by digitalization, sustainability, and the integration of artificial intelligence. Strategic alliances are becoming more prevalent, as companies recognize the need to collaborate to stay ahead in a rapidly evolving landscape. Looking forward, competitive differentiation is likely to shift from traditional price-based competition to a focus on innovation, technological advancements, and supply chain reliability. This evolution suggests that companies that prioritize these aspects will be better positioned to thrive in the future.

상업용 디스플레이 시장 시장의 주요 기업은 다음과 같습니다

Recent Industry Developments

Q3 2026: Samsung Electronics (KR): Samsung introduced next-generation glasses-free 3D Spatial Signage at its Gurugram Business Experience Studio, combining immersive displays with AI Studio and VXT for connected retail and banking environments, directly advancing commercial display capabilities.

Q3 2026: LG Electronics (KR): LG Electronics introduced the MAGNIT Gen 2 Micro LED LMPD display for large-scale commercial installations, integrating LG Micro LED technology with NovaStar’s COEX 5G control solution to simplify configuration, color processing and system management

Q3 2026: Panasonic Corporation (JP): Panasonic showcased integrated display, projection and connected visual-communication technologies at its 2026 Tech Summit in India, presenting professional display solutions across retail, transportation, corporate offices, QSR, education and healthcare applications.

Q2 2026: ViewSonic Corporation (US): ViewSonic announced the fourth-generation LDS136-152 mobile Direct View LED display, a 136-inch foldable video wall designed for rapid deployment, expanding flexible large-format display solutions for commercial and professional environments.

The commercial display market is anticipated to reach USD 52.9 billion by 2032, expanding at a CAGR of 5.16% from 2024 to 2032. This growth is attributed to the increasing adoption of digital signage and interactive displays in various commercial settings, such as retail stores, corporate offices, and hospitality venues.

Moreover, the rising demand for large-format displays and the integration of advanced technologies, such as artificial intelligence (AI) and the Internet of Things (IoT), are further driving market expansion.Key recent developments in the commercial display market include the launch of innovative products, such as ultra-high-definition (UHD) and 8K displays, and the growing popularity of video walls and transparent displays. Additionally, the increasing focus on sustainability is leading to the development of energy-efficient and eco-friendly display solutions.
향후 전망

상업용 디스플레이 시장 향후 전망

상업용 디스플레이 시장은 2024년부터 2035년까지 5.9%의 연평균 성장률(CAGR)로 성장할 것으로 예상되며, 이는 기술 발전, 디지털 사이니지에 대한 수요 증가, 고객 참여 전략의 향상에 의해 주도됩니다.

새로운 기회는 다음에 있습니다:

  • 타겟 광고를 위한 AI 기반 분석 통합
  • 맞춤형 디스플레이 솔루션으로 신흥 시장으로의 확장
  • 지속 가능성 요구를 충족하기 위한 친환경 디스플레이 기술 개발

2035년까지 시장은 혁신적인 디스플레이 솔루션의 선두주자로서의 입지를 확고히 할 것으로 예상됩니다.

시장 세분화

상업용 디스플레이 시장 규모 전망

  • 32인치 미만
  • 32인치에서 55인치 사이
  • 55인치에서 85인치 사이
  • 85인치 이상

상업용 디스플레이 시장 유형 전망

  • LCD
  • LED
  • OLED
  • PDP
  • 프로젝션

상업용 디스플레이 시장 응용 전망

  • 소매
  • 의료
  • 기업
  • 교육
  • 환대

상업용 디스플레이 시장 최종 사용자 전망

  • 기업
  • 소비자
  • 정부 기관

보고서 범위

MARKET SIZE 2024 53.7(USD Billion)
MARKET SIZE 2025 56.87(USD Billion)
MARKET SIZE 2035 100.89(USD Billion)
COMPOUND ANNUAL GROWTH RATE (CAGR) 5.9% (2025 - 2035)
REPORT COVERAGE Revenue Forecast, Competitive Landscape, Growth Factors, and Trends
BASE YEAR 2024
Market Forecast Period 2025 - 2035
Historical Data 2019 - 2024
Market Forecast Units USD Billion
Key Companies Profiled Samsung Electronics (KR), LG Electronics (KR), Sony Corporation (JP), Sharp Corporation (JP), Panasonic Corporation (JP), NEC Corporation (JP), ViewSonic Corporation (US), BenQ Corporation (TW), Epson Corporation (JP), Dell Technologies (US)
Segments Covered Display Type, Application, End User, Size, Region
Key Market Opportunities Integration of interactive technologies enhances consumer engagement in the Commercial Display Market.
Key Market Dynamics Technological advancements drive innovation in the Commercial Display Market, enhancing consumer engagement and competitive differentiation.
Countries Covered North America, Europe, APAC, South America, MEA

Frequently Asked Questions

2025년 상업용 디스플레이 시장의 현재 가치는 얼마입니까?
상업용 디스플레이 시장은 2024년에 약 537억 달러로 평가됩니다.
2035년까지 상업용 디스플레이 시장의 예상 시장 규모는 얼마입니까?
시장은 2035년까지 100.89억 USD의 가치를 달성할 것으로 예상됩니다.
2025 - 2035년 예측 기간 동안 상업용 디스플레이 시장의 예상 CAGR은 얼마입니까?
2025 - 2035년 예측 기간 동안 상업용 디스플레이 시장의 예상 CAGR은 5.9%입니다.
상업 디스플레이 시장에서 주요 기업으로 간주되는 곳은 어디인가요?
시장 주요 업체로는 삼성전자, LG전자, 소니 코퍼레이션, 샤프 코퍼레이션이 있습니다.
상업용 디스플레이의 주요 유형과 그 시장 가치는 무엇인가요?
주요 유형으로는 LCD, LED, OLED, PDP 및 프로젝션이 있으며, LED는 2035년까지 400억 USD에 이를 것으로 예상됩니다.
상업용 디스플레이 시장은 애플리케이션별로 어떻게 세분화되나요?
응용 프로그램별 시장 세분화에는 소매, 의료, 기업, 교육 및 환대가 포함되며, 기업 부문은 2035년까지 250억 달러에 이를 것으로 예상됩니다.
상업용 디스플레이 시장에서 다양한 최종 사용자에 대한 시장 규모는 얼마입니까?
최종 사용자는 기업, 소비자 및 정부 기관을 포함하며, 기업은 2035년까지 38.0 USD 억에 이를 것으로 예상됩니다.
상업용 디스플레이 시장에서 어떤 크기 범주가 있습니까?
크기 범주는 32인치 미만, 32인치에서 55인치, 55인치에서 85인치, 85인치 이상으로 나뉘며, 55인치에서 85인치 범위는 2035년까지 400억 달러에 이를 것으로 예상됩니다.
상업용 디스플레이 시장의 성장을 영향을 미치는 트렌드는 무엇인가요?
성장을 촉진하는 트렌드에는 디스플레이 기술의 발전과 기업 및 환대 산업과 같은 다양한 분야에서의 수요 증가가 포함됩니다.
상업용 디스플레이 시장은 의료 분야에서 어떻게 성과를 내고 있습니까?
헬스케어 애플리케이션 분야는 2035년까지 약 150억 USD에 이를 것으로 예상됩니다.
저자
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of industry databases, technical publications, market intelligence reports, and authoritative electronics & display organizations. Key sources included the US Department of Commerce (Display Industry Trade Data), European Commission (Digital Economy Reports), International Electrotechnical Commission (IEC) (Display Standards & Regulations), Society for Information Display (SID.org), Consumer Technology Association (CTA), National Institute of Standards and Technology (NIST), International Energy Agency (IEA) (Display Energy Consumption Data), World Intellectual Property Organization (WIPO) (Display Technology Patents), OECD Digital Economy Outlook, UNIDO Industrial Statistics, Korea Display Industry Association (KDIA), Japan Display Inc. Industry Reports, China Optics and Optoelectronics Manufacturers Association (COEMA), and Taiwan Display Union Association (TDUA). These sources were used to collect shipment statistics, technology roadmap data, regulatory compliance standards, pricing trends, and competitive landscape analysis for LED displays, LCD displays, OLED displays, direct-view LED (dvLED), and interactive commercial display technologies.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Hardware Engineering, heads of display technology, and commercial directors from OEMs, system integrators, and producers of display panels were examples of supply-side sources. Chief technology officers, procurement directors, facility managers, and AV solutions architects from retail chains, corporate businesses, educational institutions, healthcare facilities, hospitality venues, and digital signage network operators made up demand-side sources. Market segmentation, product development schedules, and information on technology adoption trends, pricing tactics, and procurement dynamics were all corroborated by primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Region: North America (32%), Europe (30%), Asia-Pacific (33%), Rest of World (5%)


Market Size Estimation

Global market valuation was derived through revenue mapping and unit shipment analysis. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across LED displays, LCD displays, OLED displays, direct-view LED, interactive displays, and digital signage solutions

Analysis of reported and modeled annual revenues specific to commercial display portfolios

Coverage of manufacturers representing 72-78% of global market share in 2024

Extrapolation using bottom-up (unit shipment × ASP by country/segment) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations

Key Adjustments Made:

Government/Authority Sources: Shifted from medical/health agencies to trade, technology, and industrial organizations relevant to display manufacturing (Commerce Dept, IEC, NIST, UNIDO, regional Asian display associations)

무료 샘플 다운로드

이 보고서의 무료 샘플을 받으려면 아래 양식을 작성하십시오

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.