メラミン市場 (2026 - 2035)

メラミン市場調査レポート情報 製品形態別(メラミン樹脂、メラミン結晶、メラミンフォーム、その他の形態)、用途別(ラミネート、木材用接着剤、成形材料、難燃剤および繊維樹脂、その他の用途)、エンドユーザー業界別(建設およびインフラ、家具および木工、自動車および輸送、その他のエンドユーザー) – 2035年までの予測
ID: MRFR/CnM/0547-HCR 137 Pages Chitranshi Jaiswal Last Updated: October 06, 2026
Melamine Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.87%
2025 Market SizeUSD 4,380 Million
2035 Market SizeUSD 6,789 Million
Key Players
BASF SE
OCI Global
INEOS Melamines
Grupa Azoty
Mitsui Chemicals
Borealis AG
Opportunities
  • Melamine Foam in Aerospace and Rail
  • Emerging-Market Housing Programs
  • Bio-Melamine and Circular-Economy Resin Systems

Melamine Market Summary

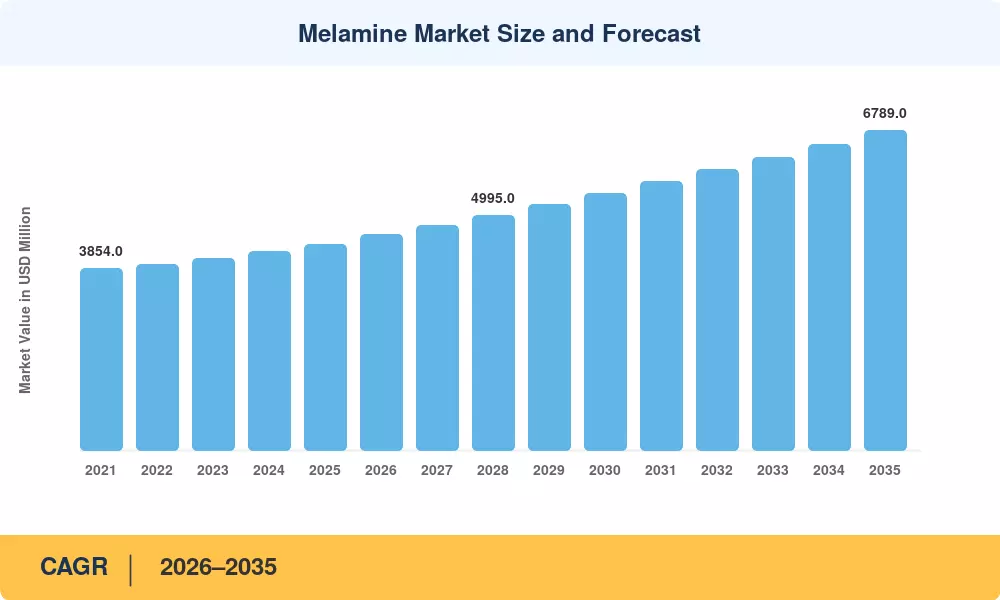
The global Melamine Market reached an estimated USD 4,380 million in 2025 and is projected to grow from USD 4,576 million in 2026 to USD 6,789 million by 2035, registering a CAGR of 4.48% across the forecast period. Tightening indoor-air-quality regulations — including the U.S. EPA's TSCA Title VI formaldehyde emission standards — are compelling panel-board and adhesive producers to reformulate with higher melamine loadings, creating a durable structural tailwind for volume growth [1].

A generational shift away from urea-formaldehyde-only binders toward melamine-fortified and melamine-urea-formaldehyde systems is under way across engineered panels and surface coatings. China's 14th Five-Year Plan allocated over CNY 6.5 billion to modernize petrochemical downstream capacity, and integrated urea–melamine complexes in Shandong and Gujarat are bringing low-cost, high-purity crystal output online at scale [2]. These investments compress resin pricing and expand the addressable end-use base simultaneously.

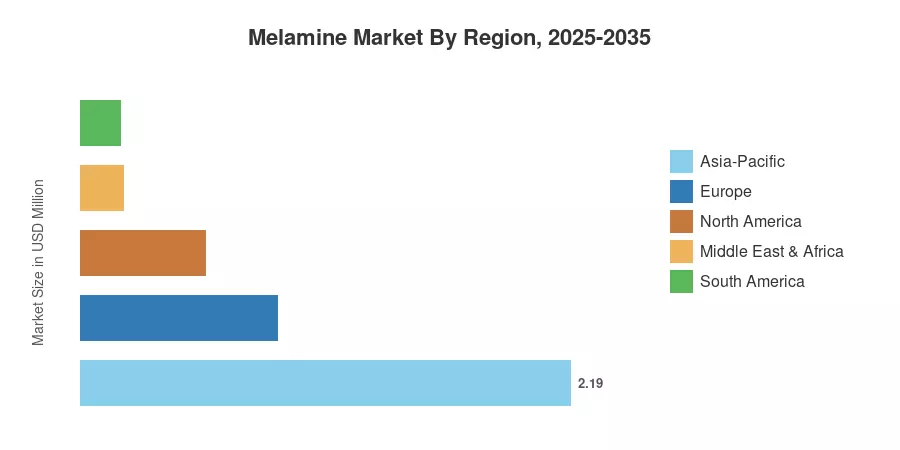
Asia-Pacific commands roughly 54.7% of global Melamine Market volume, anchored by China's dominance in both production and consumption. The Middle East & Africa region is on track to post the fastest regional CAGR at 4.70%, leveraging cost-advantaged natural-gas feedstock. Europe holds the second-largest share at approximately 22%, driven by strict EN 312 and EN 622 particleboard emission standards that favor melamine-based adhesive systems. As construction activity recovers globally and sustainability mandates intensify, the Melamine Market is positioned for steady expansion through 2035.


Key Report Takeaways

• By Product Form

  • Melamine resins captured an estimated 69.3% of the Melamine Market in 2025, driven by demand from laminate and adhesive formulators.
  • Melamine foam is advancing at a projected CAGR of 5.16% through 2035, supported by fire-safety specifications in aerospace and rail interiors.

• By Application

  • Laminates represented approximately 44.3% of the Melamine Market in 2025, reflecting their central role in surface finishing for furniture and flooring.
  • Flame-retardant and textile resin applications are forecast to grow at a 4.87% CAGR to 2035.

• By Region

  • Asia-Pacific retained 54.7% of global volume in 2025, while the Middle East & Africa is projected to record the highest regional CAGR at 4.70% through 2035.


Melamine Market Size and Forecast (2021–2035)

Market Research Future employs a triangulated estimation framework combining supply-side production audits, trade-flow analysis, and demand-side consumption surveys. All historical figures are calibrated against customs data from UN Comtrade and national chemical-industry associations.
Melamine Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Indoor-air-quality regulation tightening ~22% North America, Europe Short-term
Integrated urea–melamine complex scaling ~18% Asia-Pacific, MEA Medium-term
Construction and infrastructure recovery ~16% Global Short-term
High-pressure laminate demand growth ~14% Asia-Pacific, Europe Medium-term
Fire-safety specification expansion (foam) ~12% North America, Europe Long-term
Automotive interior lightweighting ~10% Global Long-term
Urbanization-driven housing starts ~8% Asia-Pacific, South America Medium-term


Indoor-Air-Quality Regulation

The U.S. EPA's TSCA Title VI standards mandate formaldehyde emissions below 0.05 ppm for medium-density fiberboard, pushing manufacturers to increase melamine content in resin formulations by 15–25% per panel [1]. The European Union's revised Construction Products Regulation mirrors this trajectory. These standards create a non-discretionary demand floor for the Melamine Market that is regulatory rather than cyclical.

Integrated Complex Scaling

China's Shandong Energy Group and India's Gujarat Narmada Valley Fertilizers & Chemicals have commissioned combined urea–melamine plants that reduce per-ton crystal production costs by roughly 12–18% versus standalone units [2]. This cost deflation widens the addressable application base, pulling melamine into price-sensitive wood-panel grades that previously relied on cheaper urea-only binders.

Construction Recovery Cycle

The U.S. Census Bureau reported housing starts of 1.42 million units (SAAR) in late 2024, while the EU's Renovation Wave initiative targets a doubling of building-renovation rates by 2030 [3]. Each new housing unit consumes an estimated 8–12 kg of melamine-loaded products across cabinetry, countertops, and flooring substrates, making residential construction the single largest volume lever in the Melamine Market.


Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Natural-gas price volatility ~–28% Europe, South America Short-term
Overcapacity risk from Chinese producers ~–24% Global Medium-term
Substitution by bio-based adhesives ~–20% Europe, North America Long-term
Trade tariffs and anti-dumping duties ~–16% North America, Europe Short-term
Formaldehyde health-risk perception ~–12% Global Long-term


Natural-Gas Feedstock Volatility

Melamine production consumes approximately 32–35 GJ of natural gas per ton of output. European benchmark TTF prices spiked above EUR 90/MWh during the 2022 energy crisis and remain structurally elevated relative to pre-2020 levels [8]. This feedstock exposure compresses margins for European producers and constrains the Melamine Market in the region.

Chinese Overcapacity Pressures

China's installed melamine capacity exceeded 2.1 million tons per annum in 2024, against domestic demand of roughly 1.3 million tons, generating persistent export surpluses that depress global spot pricing [9]. Anti-dumping investigations by the European Commission and U.S. Department of Commerce reflect the trade friction this overcapacity creates.


Melamine Market Opportunities

Melamine Foam in Aerospace and Rail

Class ASTM E84 Fire-rated melamine foam is making its way into aircraft cabin insulation and high-speed rail acoustic panels. Boeing’s 2024 supplier qualification roadmap has authorized two grades of melamine foam in its materials list, allowing for a high-margin sub-segment estimated at approximately USD 180 million by 2030 [5].


Emerging-Market Housing Programs

India’s Pradhan Mantri Awas Yojana (PMAY) is a program to build 30 million affordable housing units by 2026, each needing melamine-surfaced panels for cabinetry and interior finishing [7]. These programs are on a scale similar to those in Indonesia and Egypt, where volume pull is created in regions with per capita melamine consumption below the global average.


Bio-Melamine and Circular-Economy Resin Systems

Several European chemical firms are running pilot programs to develop the synthesis of melamine from bio-based urea from collected CO2 streams with lifecycle carbon reductions up to 40% [10]. Early Commercial Adoption Melamine Market could conform with the EU Taxonomy for Sustainable Activities by 2030.


Digital Printing on Melamine Surfaces

Advances in inkjet technology allow direct digital printing on melamine-impregnated paper, which cuts décor-paper inventory by up to 60% for laminate makers [4]. This shift drives demand for specialist resin grades that are optimized for ink-absorption qualities, and provides a premium pricing tier within the Melamine Market.


Data-Driven Supply-Chain Optimization

Cloud-based procurement platforms are enabling melamine distributors to offer dynamic pricing and just-in-time delivery models. Large panel-board producers report 8–12% reductions in working-capital requirements after integrating algorithmic resin sourcing, creating a new service-layer revenue stream for chemical distributors.


Melamine Market Future Outlook

Sustainability-Driven Resin Reformulation

The EU Taxonomy and CBAM mechanisms will increasingly penalize carbon-intensive chemical production routes. Melamine producers investing in captured-CO₂ urea feedstock could achieve 30–40% lifecycle emission reductions, aligning the Melamine Market with green-building certification frameworks such as LEED v5 and BREEAM 2030 [14].

Digital Manufacturing and Industry 4.0

Automated resin-dosing systems using real-time viscosity sensors are reducing melamine-resin waste by 6–10% in laminate press operations. Adoption of predictive-maintenance analytics across Asian mega-plants is expected to improve asset utilization by 3–5 percentage points, structurally lowering per-unit costs in the Melamine Market through 2035 [15].

Electrification and Lightweight Composites

As electric-vehicle production scales toward 40 million units annually by 2030 (per IEA projections), melamine-based composites are replacing heavier phenolic parts in battery-pack housings and under-hood components [6]. This automotive lightweighting trend introduces a growth vector largely independent of construction cycles.

Modular and Prefabricated Construction

Off-site construction methods are expanding at 8–10% annually in North America and Europe, with prefabricated wall panels and modular kitchen units consuming pre-surfaced melamine boards at significantly higher rates per project than conventional stick-built homes [16]. The Melamine Market stands to benefit as modular construction captures 15–20% of new residential starts by 2032.


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
Asia-Pacific 54.7% share (2025) Integrated production complexes, housing urbanization
Europe 22.0% share (2025) Emission regulation, renovation wave
North America 14.0% share (2025) TSCA compliance, residential construction
South America 4.5% share (2025) Affordable housing, import substitution
Middle East & Africa 4.70% CAGR (2026–2035) Gas-feedstock advantage, capacity additions
Total USD 4,380 Million (2025) —

The Melamine Market exhibits a pronounced geographic concentration, with Asia-Pacific and Europe collectively accounting for over three-quarters of global consumption. Regional growth trajectories diverge based on feedstock economics, construction activity, and regulatory intensity.


North America

Country Key Metric Key Driver
US 68% of regional share TSCA Title VI reformulation demand
Canada 4.62% CAGR Housing starts and panel-board expansion
Mexico USD 82 Million (2025) Furniture export manufacturing


North America's Melamine Market is underpinned by strict formaldehyde-emission standards and a robust residential construction cycle. The U.S. accounts for the dominant portion of regional demand, with composite-panel producers reformulating adhesives to meet EPA emission thresholds [1].

Europe

Country Key Metric Key Driver
Germany 28% of regional share Engineered-panel manufacturing
UK 4.38% CAGR Post-Brexit domestic production
France USD 128 Million (2025) Renovation Wave subsidies
Italy 14% of regional share Furniture and kitchen cabinetry
Spain 4.25% CAGR Residential construction rebound
Nordic Countries USD 65 Million (2025) Sustainable building mandates
Russia 8% of regional share Domestic particleboard production
Rest of Europe 4.15% CAGR Central European capacity growth


Europe's Melamine Market benefits from stringent Construction Products Regulation standards and the EU Renovation Wave, which channels over EUR 275 billion into building upgrades through 2030 [3].

Asia-Pacific

Country Key Metric Key Driver
China 58% of regional share Integrated urea–melamine production
India 5.10% CAGR PMAY housing, domestic capacity growth
Japan USD 185 Million (2025) High-performance laminate applications
South Korea 7% of regional share Electronics and automotive interiors
ASEAN 4.85% CAGR Urbanization and furniture exports
Rest of Asia-Pacific USD 95 Million (2025) Emerging industrial base


Asia-Pacific dominates the Melamine Market on both production and consumption axes. China's Shandong and Henan provinces host over 60% of global installed crystal capacity, while India's accelerating domestic production is reducing import dependence [2].

South America

Country Key Metric Key Driver
Brazil 62% of regional share MDF/HDF panel production
Argentina 4.30% CAGR Furniture manufacturing recovery
Rest of South America USD 28 Million (2025) Import-driven consumption


Brazil anchors South America's Melamine Market through its large medium-density fiberboard industry, which consumes melamine-urea-formaldehyde resins for panel surfacing and edge banding [7].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 30% of regional share Vision 2030 construction programs
UAE 4.80% CAGR Hospitality and commercial fit-out
South Africa USD 22 Million (2025) Residential panel demand
Egypt 5.05% CAGR New Administrative Capital construction
Rest of MEA 18% of regional share Gas-feedstock capacity additions


The Middle East & Africa represents the fastest-growing region in the Melamine Market, propelled by Qatar Melamine Company's 60,000-ton-per-annum facility and Saudi Arabia's Vision 2030 mega-projects that require extensive laminate and surface-finishing materials [13].


Melamine Market By Region, 2025-2035

Melamine Market Segmentation

By Product Form

Segment Key Metric Primary Demand Driver
Melamine Resins 69.3% share (2025) Laminate and adhesive formulations
Melamine Crystals USD 1,120 Million (2025) Resin synthesis feedstock
Melamine Foam 5.16% CAGR Fire-safety and acoustic insulation
Other Forms USD 185 Million (2025) Specialty coatings and additives


Melamine resins dominate the Melamine Market by product form, serving as the primary binder in high-pressure and low-pressure laminate production. These resins deliver superior hardness, moisture resistance, and surface clarity compared to urea-only alternatives, making them indispensable in furniture-grade and flooring-grade panels. Melamine foam, while smaller in absolute volume, is carving out a premium position through fire-rated acoustic and thermal insulation applications in transportation and commercial construction.

By Application

Segment Key Metric Primary Demand Driver
Laminates 44.3% share (2025) Furniture surfacing and flooring
Wood Adhesives USD 870 Million (2025) Particleboard and MDF binding
Molding Compounds 4.55% CAGR Tableware and electrical components
Flame Retardants & Textile Resins 4.87% CAGR Fire-safety codes and textile finishing
Other Applications USD 290 Million (2025) Concrete admixtures, paper treatment


Laminates anchor the Melamine Market's application landscape, spanning decorative surfaces for kitchen countertops, office furniture, and commercial flooring. The shift toward digital décor printing is raising resin-quality specifications within this segment. Flame-retardant applications are gaining momentum as building codes in the U.S., EU, and Gulf Cooperation Council states mandate intumescent or char-forming additives in interior assemblies.

By End-User Industry

Segment Key Metric Primary Demand Driver
Construction & Infrastructure 45.3% share (2025) Panel surfacing, adhesives, insulation
Furniture & Woodworking USD 1,050 Million (2025) Residential and commercial furniture
Automotive & Transportation 4.69% CAGR Lightweight composites, interior trim
Other End Users USD 380 Million (2025) Tableware, textiles, coatings


Construction and infrastructure represent the largest end-user segment in the Melamine Market, consuming melamine resins and foam across residential housing, commercial interiors, and public-infrastructure projects. Automotive and transportation end users constitute the fastest-growing segment, driven by OEM demand for lightweight, flame-resistant interior components that meet evolving vehicle-safety regulations [6].


Competitive Benchmarking

The Melamine Market exhibits medium concentration, with the top five producers accounting for an estimated 38–45% of global revenue. Regional fragmentation is significant in Asia-Pacific, where dozens of mid-scale Chinese producers compete primarily on price, while European and Middle Eastern players differentiate through product purity, sustainability credentials, and integrated logistics.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
BASF SE ~8–11% Melamine resins, impregnation solutions Integrated chemical portfolio, European leadership
OCI Global ~6–9% Melamine crystals, nitrogen products Low-cost European and North African production
INEOS Melamines ~5–8% High-purity crystals, specialty resins Pan-European supply network
Grupa Azoty ~4–7% Melamine crystals, fertilizer co-production Central European cost advantage
Qatar Melamine Company ~4–6% Melamine crystals Gas-feedstock cost leadership, MEA hub
Mitsui Chemicals ~3–5% Specialty melamine resins Asia-Pacific technology licensing
Cornerstone Chemical Company ~3–5% Melamine crystals, ammonia derivatives Sole U.S. melamine producer
Borealis AG ~2–4% Melamine, nitrogen fertilizers Integrated Austrian operations
Nissan Chemical Corporation ~2–4% Fine melamine products Japanese specialty-chemical focus
Prefere Resins ~2–3% Melamine-urea-formaldehyde resins Panel-industry resin specialist


Recent News & Developments


  • BASF (February 2025) introduced Basotect EcoBalanced, a melamine resin foam with a lower product carbon footprint from the use of green electricity and renewable raw materials using a mass balancing technique. The product extends the application reach of melamine foams in areas where fire performance and acoustics are required while procurement increasingly screens for lower-carbon materials.


  • European Commission (April 2023): Initiated an anti-dumping investigation into melamine imports from China and Trinidad and Tobago, with preliminary duties ranging from 18% to 32% [11].


メラミン市場 Market Report Scope

パラメータ 詳細
市場範囲 グローバルメラミン市場 — 結晶、樹脂、フォーム、特別な形状
調査期間 2021–2035
CAGRウィンドウ 2026–2035
基準年 2025
市場規模 (2025) USD 43億8000万
市場規模 (2035) USD 67億8900万
最も成長が早いセグメント メラミンフォーム (5.16% CAGR)
最も成長が早い地域 中東 & アフリカ (4.70% CAGR)
プロファイルされた企業 10
評価通貨 USD百万

よくある質問

バルクメラミン結晶調達の典型的な契約構造は何ですか?
ほとんどの産業バイヤーは、天然ガス指数にリンクした6〜12ヶ月の固定価格契約を交渉し、四半期ごとのボリュームフレックス条項を±10%設けています。スポット購入は、季節的な需要の急増時に契約ボリュームを補完します[8]。
メラミンフォームは建物の断熱材として繊維強化プラスチックと比較してどうですか?
メラミンフォームは、繊維強化プラスチックよりも優れた耐火性(ASTM E84クラスA)と低い煙毒性を提供しますが、設置された平方メートルあたり25〜35%のコストプレミアムがかかります。火災安全基準が厳しい占有空間で好まれます[5]。
ヨーロッパの輸入業者が監視すべき反ダンピングリスクは何ですか?
欧州委員会は、中国からのメラミンに対して18〜32%の反ダンピング税を維持しており、税率を調整できる定期的なサンセットレビューがあります。輸入業者は、税金改訂のための公式ジャーナル通知を追跡する必要があります[11]。
石油由来のメラミンに代わるバイオベースの代替品はありますか?
CO₂由来の尿素ルートによるバイオメラミンはパイロット段階にあり、商業的な実現可能性は2029年以降に期待されています。現在の生産コストは従来のルートの約2倍です[10]。
ラミネート製造業者はメラミン供給者からどのような品質認証を要求しますか?
ラミネートグレードのメラミンは通常、ISO 9001プロセス認証、欧州販売のためのREACH登録、鉄分含有量が1ppm未満で99.8%以上の純度レベルを必要とします[19]。
メラミン市場は住宅建設の低迷にどのように反応しますか?
住宅の低迷時にはボリュームが3〜5%減少しますが、改修や修理活動が新築の減少を部分的に相殺します。2020年の低迷では4.2%のボリューム減少が見られ、その後急速に回復しました[22]。
メラミン市場は電気自動車バッテリーコンポーネント製造にどのような役割を果たしていますか?
メラミンベースの複合材料は、EVバッテリーパックの難燃性セパレーターおよびハウジングコンポーネントとして機能します。この用途は新興ですが、OEMが軽量で難燃性の材料を求める中で成長しています[6]。
著者
著者 Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry publications, chemical manufacturing records, and authoritative industry associations. Key sources included the U.S. Environmental Protection Agency (EPA), European Chemicals Agency (ECHA), International Chemical Safety Cards (ICSC), National Institute of Standards and Technology (NIST), American Chemistry Council (ACC), European Chemical Industry Council (Cefic), China Petroleum and Chemical Industry Federation (CPCIF), Indian Chemical Council (ICC), Japan Chemical Industry Association (JCIA), International Monetary Fund (IMF) Commodity Price Data, World Trade Organization (WTO) Trade Statistics, United Nations Comtrade Database, International Energy Agency (IEA), U.S. Geological Survey (USGS) Mineral Commodity Summaries, National Bureau of Statistics of China, Eurostat Chemical Production Statistics, OECD Chemical Industry Statistics, and national chemical industry ministry reports from key manufacturing markets.

Production capacity data, import-export statistics, regulatory compliance frameworks, raw material cost trends (natural gas and urea), and competitive landscape analysis for melamine resin, melamine foam, and related thermosetting chemicals were gathered from these sources.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Manufacturing Operations, plant managers, and procurement heads from OEM suppliers, chemical companies, and producers of melamine resin were examples of supply-side sources. Procurement directors from building material firms, furniture makers, laminate producers, car interior specialists, textile finishing houses, and R&D leaders from adhesive formulation companies were examples of demand-side suppliers. In addition to gathering information on feedstock cost dynamics, pricing volatility, sustainability compliance, and end-user replacement tendencies, primary research verified capacity development timeframes and validated market segmentation.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (32%), Others (40%)

By Region: North America (28%), Europe (30%), Asia-Pacific (38%), Rest of World (4%)


Market Size Estimation

Production capacity mapping and consumption volume analysis were used to get the global market valuation. The methodology comprised:

Finding more than 35 important manufacturers in the Middle East, Latin America, Europe, Asia-Pacific, and North America

Product mapping for specialist melamine derivatives (laminates, wood adhesives, surface coatings, thermoset plastics), melamine resin, and melamine foam

Analysis of annual sales for melamine product portfolios, both reported and modeled

Coverage of producers accounting for 75–80% of the world market in 2024

Extrapolation using bottom-up (consumption volume × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for construction, automotive, chemical, and textile end-use sectors

無料サンプルをダウンロード

このレポートの無料サンプルを受け取るには、以下のフォームにご記入ください

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















