マグネシウム金属市場 (2026 - 2035)

Magnesium Metal Market Research Report Information By End-user Industry (aluminum alloys, die-casting, iron and steel, metal reduction, and Other end-user industries) – Forecast Till 2035.
ID: MRFR/CnM/1445-HCR 111 Pages Chitranshi Jaiswal Last Updated: October 12, 2026
Magnesium Metal Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.45%
2025 Market SizeUSD 4,085.0 Million
2035 Market SizeUSD 6,952.6 Million
Key Players
Baowu Magnesium Technology Co., Ltd.
Shanxi Yinguang Huasheng Magnesium Co., Ltd.
China Magnesium Corporation
Qinghai Salt Lake Industry Co., Ltd.
Dead Sea Magnesium Ltd.
RIMA Industrial S.A.
Opportunities
  • Biodegradable Medical Implants
  • Seawater and Brine Extraction in Emerging Markets
  • Closed-Loop Recycling and Traceability Services

マグネシウム金属市場 概要

MRFRの分析によると、マグネシウム金属市場の規模は2024年に54億米ドルと推定されました。マグネシウム金属産業は、2025年に57.39億米ドルから2035年までに105.4億米ドルに成長する見込みであり、2025年から2035年の予測期間中に年平均成長率(CAGR)は6.27を示します。

主要な市場動向とハイライト

マグネシウム金属市場は、持続可能性と技術の進歩によって成長する準備が整っています。

  • 北米は、さまざまな産業における堅調な需要に支えられ、マグネシウム金属の最大市場であり続けています。
  • アジア太平洋地域は、製造業と技術への投資の増加を反映して、最も成長が早い地域として浮上しています。
  • 熱還元プロセスが市場を支配し続けている一方で、電解プロセスはその効率性から注目を集めています。
  • 主要な市場の推進要因には、軽量材料の需要の高まりと再生可能エネルギー技術の拡大が含まれます。

市場規模と予測

2024 Market Size 5.4 (米ドル十億)
2035 Market Size 10.54 (USD十億)
CAGR (2025 - 2035) 6.27%

主要なプレーヤー

中国マグネシウム株式会社(CN)、アメリカマグネシウムLLC(US)、ルサル(RU)、ノルスク・ハイドロASA(NO)、マグネシウムエレクトロン(GB)、死海マグネシウム株式会社(IL)、ポスコ(KR)、イングアンマグネシウム(CN)、天津マグネシウムインターナショナル(CN)

マグネシウム金属市場 運転手

軽量材料の需要の増加

軽量材料の需要がさまざまな産業でマグネシウム金属市場を牽引しています。マグネシウムは最も軽い構造金属の一つであり、燃料効率を向上させ、排出量を削減するために自動車や航空宇宙の用途でますます利用されています。特に自動車部門では、マグネシウム部品の使用が急増すると予測されており、2026年までに自動車用途におけるマグネシウム市場は数十億ドルに達する可能性があると見込まれています。この傾向は、製造業者が厳しい環境規制に準拠しながら車両性能を向上させることを求める中で、マグネシウム金属市場を強化することが期待されます。

再生可能エネルギー技術の拡大

再生可能エネルギー源への移行は、マグネシウム金属市場に大きな影響を与えています。マグネシウムは、特にバッテリーや燃料電池におけるエネルギー貯蔵システムでの利用可能性が探求されています。効率的なエネルギー貯蔵ソリューションの需要が高まる中、マグネシウムベースの技術の必要性が増す可能性があります。報告によると、エネルギー用途におけるマグネシウムの市場は、持続可能なエネルギーソリューションへの世界的なシフトにより急速に拡大する可能性があります。この拡大は、企業が進化するエネルギー環境に対応するために革新を進める中で、マグネシウム金属市場内に新たな機会を生み出すと期待されています。

抽出プロセスにおける技術革新

マグネシウム金属市場は、抽出および生産技術の進展によって変革を遂げる準備が整っています。改良された電解法やより効率的な熱還元プロセスなどの革新は、生産コストを低下させ、収率を向上させる可能性があります。これらの技術的改善は、より持続可能で経済的に実行可能なマグネシウム生産の風景をもたらすかもしれません。生産がより効率的になるにつれて、マグネシウム金属市場には新たなプレーヤーが流入し、競争が激化する可能性があり、価格が下がり、さまざまな用途への市場アクセスが拡大するかもしれません。

マグネシウム合金の需要の高まり

マグネシウム合金のさまざまな分野での利用の増加は、マグネシウム金属市場の主要な推進要因です。これらの合金は、優れた機械的特性と軽量特性が評価されており、自動車、航空宇宙、電子機器などの用途に理想的です。マグネシウム合金の市場は、今後数年間で需要が大幅に増加するとの予測があり、堅調な成長が見込まれています。この傾向は、さまざまな産業の高まるニーズに応えるために、製造業者が生産を増加させることを促進し、マグネシウム金属市場を刺激する可能性があります。

航空宇宙産業における応用の増加

航空宇宙産業は、その高い強度対重量比や優れた加工性といった有利な特性から、マグネシウムの採用をますます進めています。この傾向は、航空機の重量を減らし、燃料効率を向上させようとする製造業者にとって、マグネシウム金属市場に利益をもたらすと考えられます。最近のデータは、航空宇宙部門のマグネシウム需要が大幅に増加する可能性があることを示唆しており、今後数年間で5%を超える年平均成長率が予測されています。この成長は、航空宇宙メーカーが軽量材料を優先する中で、マグネシウム金属市場の全体的な市場動向を強化することが期待されています。

地域の洞察

North America : Growing Demand and Innovation

The North American magnesium metal market is driven by increasing demand in automotive and aerospace sectors, with a focus on lightweight materials for fuel efficiency. The U.S. holds the largest market share at approximately 60%, followed by Canada at around 25%. Regulatory support for lightweight materials and sustainability initiatives further catalyze growth in this region. Key players like U.S. Magnesium LLC and Rusal are pivotal in shaping the competitive landscape. The U.S. government’s focus on domestic production and reducing reliance on imports enhances market dynamics. With advancements in extraction and processing technologies, North America is poised for significant growth in magnesium applications across various industries.

Europe : Sustainability and Innovation Focus

Europe is witnessing a robust growth trajectory in the magnesium metal market, driven by stringent environmental regulations and a shift towards sustainable materials. Germany and France are the largest markets, collectively holding about 55% of the regional share. The European Union's Green Deal and initiatives to reduce carbon emissions are significant catalysts for market expansion. Leading countries like Germany, Italy, and France are home to key players such as Norsk Hydro ASA and Magnesium Elektron. The competitive landscape is characterized by innovation in recycling and production processes, aligning with the EU's sustainability goals. The region's focus on electric vehicles and renewable energy applications further boosts demand for magnesium, positioning Europe as a leader in the global market.

Asia-Pacific : Emerging Markets and Production Hub

The Asia-Pacific region is a powerhouse in the magnesium metal market, primarily driven by rapid industrialization and increasing demand from the automotive and electronics sectors. China dominates the market, holding approximately 70% of the regional share, followed by India at around 15%. Government initiatives to enhance production capabilities and reduce environmental impact are key growth drivers. China Magnesium Corporation and Yinguang Magnesium are leading players in this competitive landscape. The region's focus on expanding manufacturing capabilities and technological advancements in magnesium extraction processes positions Asia-Pacific as a critical player in the global market. The increasing adoption of magnesium in lightweight applications further fuels demand, ensuring sustained growth in the coming years.

Middle East and Africa : Resource-Rich and Emerging Markets

The Middle East and Africa region is emerging as a significant player in the magnesium metal market, driven by abundant natural resources and increasing industrial activities. Countries like South Africa and Egypt are leading the market, collectively holding about 40% of the regional share. The region's focus on diversifying economies and enhancing manufacturing capabilities is a key growth driver. The competitive landscape is characterized by a mix of local and international players, with companies like Dead Sea Magnesium Ltd. making notable contributions. The region's potential for growth is further supported by investments in infrastructure and technology, positioning it as a future hub for magnesium production and innovation. As demand for lightweight materials rises, the Middle East and Africa are set to capitalize on their resource advantages.

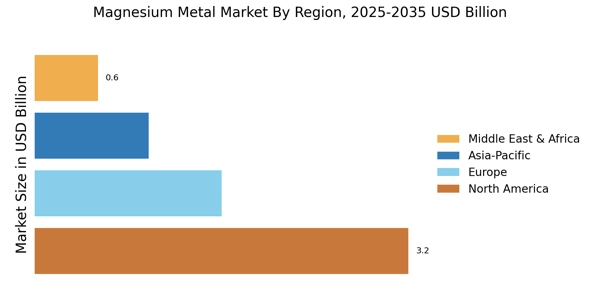
マグネシウム金属市場 Regional Image

主要企業と競争の洞察

マグネシウム金属市場は、現在、自動車、航空宇宙、電子機器などのさまざまな分野での需要の増加により、動的な競争環境が特徴です。主要なプレーヤーは、革新、地域拡大、持続可能性を強調する戦略に積極的に取り組んでいます。たとえば、U.S. Magnesium LLC(米国)は、技術革新を通じて生産能力の向上に注力しており、Rusal(ロシア)は、アルミニウム生産における豊富な経験を活かしてマグネシウムをポートフォリオに統合し、提供内容を多様化しています。これらの戦略的な立場は、市場での存在感を強化するだけでなく、現代の製造にとってますます重要になっている分野でのリーダーシップを巡って企業が競い合う、より競争的な環境に寄与しています。

ビジネス戦略に関しては、企業はコストを削減し、サプライチェーンの効率を向上させるために製造を地域化しています。マグネシウム金属市場は、いくつかの主要なプレーヤーがそれぞれの地域に影響を及ぼしているため、適度に分散しているようです。この分散は、企業が自社の運営を最適化し、地域市場の需要に応じるためのさまざまな競争戦略を可能にします。これらのプレーヤーの集合的な影響は市場構造を形成し、革新と運営の卓越性が最も重要な環境を育んでいます。

2025年8月、Norsk Hydro ASA(ノルウェー)は、車両の効率を向上させることを目的とした軽量マグネシウム部品を開発するために、主要な自動車メーカーとの戦略的パートナーシップを発表しました。このコラボレーションは、自動車セクターにおける軽量材料への傾向が高まっていることを強調しており、持続可能性と燃料効率にますます焦点を当てています。Norsk Hydroは、自動車業界の主要なプレーヤーと提携することで、急速に進化する市場における重要な供給者としての地位を確立しています。

2025年9月、中国マグネシウム株式会社(中国)は、世界的な需要の高まりに応じて生産施設の拡張計画を発表しました。この拡張により、同社の生産能力が大幅に増加し、国際市場により良く対応できるようになると期待されています。この動きの戦略的重要性は、特に産業成長によりマグネシウムの需要が急増している地域で、中国マグネシウムの供給者としての地位を確固たるものにする可能性にあります。

2025年10月、死海マグネシウム株式会社(イスラエル)は、持続可能性を重視した新しいエコフレンドリーなマグネシウム製品ラインを発表しました。この取り組みは、環境に配慮した製造慣行への業界全体の傾向を反映しています。持続可能性を優先することで、死海マグネシウムは規制の要求を満たすだけでなく、エコ意識の高い製品を重視する消費者層にアピールし、競争力を高めています。

2025年10月現在、マグネシウム金属市場は、デジタル化、持続可能性、AIなどの先進技術の統合を強調する傾向を目の当たりにしています。戦略的提携は、企業が革新を推進するためのコラボレーションの価値を認識する中で、競争環境をますます形成しています。価格競争から技術革新とサプライチェーンの信頼性に焦点を移す動きが明らかになっています。この進化する環境において、革新と持続可能な慣行を優先する企業がリーダーとして浮上し、マグネシウム金属市場における競争の差別化を再定義する可能性が高いです。

マグネシウム金属市場市場の主要企業には以下が含まれます

Recent Industry Developments

  • 2024年第2四半期:US Magnesiumがユタ州施設の1億米ドル拡張を発表 US Magnesiumは、ユタ州ローリーの工場を拡張するために1億米ドルを投資する計画を発表し、生産能力を増加させ、外国からの輸入依存を減らすことを目指しています。この拡張により、60の新しい雇用が創出され、米国のマグネシウム金属供給チェーンが強化される見込みです。
  • 2024年第2四半期:南京雲海特種金属が山西文西マグネシウムの支配権を1億2000万米ドルで取得 南京雲海特種金属は、山西文西マグネシウムの過半数の株式を取得し、中国最大のマグネシウム生産者の一つとしての地位を強化し、高品位マグネシウム資源へのアクセスを拡大しました。
  • 2024年第2四半期:欧州委員会がドイツの新しいマグネシウムリサイクル工場に規制承認を付与 欧州委員会は、ドイツのザクセンにマグネシウムリサイクル施設の建設を承認しました。この施設は、自動車および航空宇宙部門からのスクラップマグネシウムを処理し、EUの持続可能性目標を支援します。
  • 2024年第3四半期:Western Magnesium Corp.が米国生産を加速するために3000万米ドルの資金調達を確保 Western Magnesium Corp.は、機関投資家主導の3000万米ドルの資金調達を完了し、米国における独自のクリーンマグネシウム生産技術を拡大することを可能にしました。
  • 2024年第3四半期:マグネシウムエレクトロンが航空宇宙用途向けの新しい高性能マグネシウム合金を発表 マグネシウムエレクトロンは、航空宇宙部品向けに設計された新しいマグネシウム合金を導入し、強度と耐腐食性を向上させ、航空機メーカー向けの軽量ソリューションを提供します。
  • 2024年第3四半期:米国エネルギー省がマグネシウム抽出研究のために1500万米ドルの助成金を授与 米国エネルギー省は、エネルギー消費と環境影響を削減することを目的とした先進的なマグネシウム抽出方法を開発するために、大学と企業のコンソーシアムに1500万米ドルの助成金を授与しました。
  • 2024年第4四半期:中国の銀光マグネシウムが欧州自動車OEMとの長期供給契約を締結 銀光マグネシウムは、主要な欧州自動車メーカーとの数年にわたる供給契約を締結し、軽量車両部品におけるマグネシウム金属の安定した需要を確保しました。
  • 2024年第4四半期:マグネシウムインターナショナル社が西オーストラリアに新しい生産施設を開設 マグネシウムインターナショナル社は、西オーストラリアに新しいマグネシウム金属生産工場を開設し、地域の生産量を増加させ、地元の製造業を支援します。
  • 2025年第1四半期:グローバルマグネシウムホールディングスが国際的な拡張を推進するために新しいCEOを任命 グローバルマグネシウムホールディングスは、ドクター・リサ・チェンを新しい最高経営責任者に任命し、同社のグローバル成長戦略をリードし、欧州および北米での新しいパートナーシップを築く任務を与えました。
  • 2025年第1四半期:POSCOマグネシウムが韓国のEVバッテリー生産用マグネシウム供給契約を確保 POSCOマグネシウムは、次世代電気自動車バッテリー用のマグネシウム金属を提供するために、韓国の主要なバッテリーメーカーとの供給契約を締結し、同国のクリーンエネルギー移行を支援します。
  • 2025年第2四半期:Western Magnesium Corp.が軽量車両部品のために米国自動車メーカーとのパートナーシップを発表 Western Magnesium Corp.は、将来の車両モデル向けにマグネシウムベースの軽量部品を開発・供給するために、主要な米国自動車会社との戦略的パートナーシップを締結しました。
  • 2025年第2四半期:マグネシウムテクノロジーズ社が拡張資金調達のためにNASDAQにIPOを申請 マグネシウムテクノロジーズ社は、マグネシウム金属生産能力の拡大と新しい合金開発の推進のために資本を調達することを目指して、NASDAQに初回公開株式の書類を提出しました。

今後の見通し

マグネシウム金属市場 今後の見通し

マグネシウム金属市場は、2024年から2035年にかけて年平均成長率6.27%で成長する見込みであり、自動車および航空宇宙部門での需要の増加と抽出技術の進展がその要因です。

新しい機会は以下にあります:

  • 電気自動車用の軽量マグネシウム合金の開発

2035年までに、マグネシウム金属市場は、革新と持続可能性の取り組みによって堅調な成長を遂げると予想されています。

市場セグメンテーション

マグネシウム金属市場製品の展望

  • 純マグネシウム
  • マグネシウム化合物
  • マグネシウム合金

マグネシウム金属市場の製造プロセスの展望

  • 熱的還元プロセス
  • 電解プロセス
  • リサイクル

レポートの範囲

Parameter Details
Market Scope Magnesium Metal Market by end-user industry and region, covering primary and recycled metal
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.45% (2026–2035)
Market Size Checkpoints USD 4,085.0 Million (2025); USD 4,312.5 Million (2026); USD 6,952.6 Million (2035)
Fastest Growing Segments die-casting (end-user industry); Asia-Pacific (region)
Companies Profiled Baowu Magnesium, Shanxi Yinguang Huasheng, China Magnesium Corporation, Qinghai Salt Lake Industry, Dead Sea Magnesium, RIMA Industrial, Solikamsk Magnesium Works, US Magnesium, Latrobe Magnesium, Magrathea Metals
Valuation Currency USD Million

Frequently Asked Questions

マグネシウム金属市場の現在の評価額はどのくらいですか?
マグネシウム金属市場は2024年に54億USDの価値がありました。
2035年のマグネシウム金属市場の予想市場評価額はどのくらいですか?
市場は2035年までに105.4億USDに達すると予測されています。
2025年から2035年までのマグネシウム金属市場の予想CAGRはどのくらいですか?
マグネシウム金属市場の2025年から2035年の予測期間中の期待されるCAGRは6.27%です。
マグネシウム金属市場において重要な製造プロセスはどれですか?
主要な製造プロセスには、熱還元プロセス、電解プロセス、リサイクルが含まれ、それぞれ2035年までに41.2億米ドル、30.8億米ドル、33.4億米ドルの評価があります。
マグネシウム金属市場の主な製品セグメントは何ですか?
主要な製品セグメントは、純マグネシウム、マグネシウム化合物、マグネシウム合金であり、それぞれ2035年までに30億米ドル、24億米ドル、51.4億米ドルの評価が見込まれています。
マグネシウム金属市場の主要企業はどこですか?
市場の主要プレーヤーには、中国マグネシウム株式会社、U.S. Magnesium LLC、ルサール、ノルスク・ハイドロASAなどが含まれます。
マグネシウム合金の性能は他の製品と比べてどうですか?
マグネシウム合金は2035年までに51.4億USDの最高評価を持つと予測されており、強い需要を示しています。
マグネシウム金属市場においてリサイクルはどのような役割を果たしていますか?
リサイクルは2035年までに33.4億USDの評価に寄与すると期待されており、持続可能性におけるその重要性を強調しています。
マグネシウム金属市場の成長に影響を与えているトレンドは何ですか?
成長は、自動車および航空宇宙産業における軽量材料の需要の増加によって推進されているようです。
電解プロセスは、マーケットバリューの観点から熱還元プロセスとどのように比較されますか?
電解プロセスは2035年までに3.08億米ドルに達すると予測されており、熱還元プロセスは4.12億米ドルに達すると期待されており、競争の激しい状況を示しています。
著者
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry publications, trade statistics, government mineral resources reports, and authoritative materials science journals. Key sources included the US Geological Survey (USGS) Mineral Commodity Summaries, International Magnesium Association (IMA), US Department of Energy (DOE), European Commission Directorate-General for Internal Market, Industry, Entrepreneurship and SMEs (GROW), China Nonferrous Metals Industry Association (CNIA), International Energy Agency (IEA) Critical Minerals Division, Organisation for Economic Co-operation and Development (OECD) Trade Statistics, World Bureau of Metal Statistics (WBMS), United Nations Comtrade Database, National Institute of Standards and Technology (NIST) Materials Genome Initiative, German Federal Institute for Geosciences and Natural Resources (BGR), Japan Oil, Gas and Metals National Corporation (JOGMEC), Australian Bureau of Statistics (ABS) Mineral Resources, Indian Bureau of Mines (IBM), Brazilian National Mining Agency (ANM), and national geological surveys from key producing markets. These sources were used to collect production statistics, trade flow data, regulatory policy frameworks, patent filings, environmental compliance standards, and supply chain landscape analysis for thermal reduction processes (Pidgeon process), electrolytic processes, recycling technologies, pure magnesium, magnesium alloys (AZ, AM, AS, ZK, ZE series), and magnesium compounds.

Additional secondary sources included MRFR Commodity Insights, CRU Group Magnesium Market Outlook, Metal Bulletin (Fastmarkets) pricing databases, International Aluminium Institute (IAI) cross-reference data, Society of Automotive Engineers (SAE) standards publications, ASTM International B07 Committee on Light Metals and Alloys, Aerospace Materials Specifications (AMS), US Environmental Protection Agency (EPA) Toxics Release Inventory, European Chemicals Agency (ECHA) REACH registrations, China Ministry of Industry and Information Technology (MIIT) industrial policies, Korea Institute of Geoscience and Mineral Resources (KIGAM), and peer-reviewed journals including Journal of Magnesium and Alloys, Materials Science and Engineering: A, Corrosion Science, and Resources, Conservation and Recycling.
 

Primary Research

The major study process involved gathering qualitative and quantitative information through interviews with supply-side and demand-side participants. Supply-side sources included the CEOs, VPs of Operations, plant managers, chief metallurgists, and heads of regulatory affairs of primary magnesium producers, alloy manufacturers, and recycling facilities. Demand-side representatives included Chief Procurement Officers from automobile OEMs (powertrain and chassis engineering divisions), aerospace Tier-1 suppliers, electronics manufacturers, die-casting foundry managers, and materials scientists from R&D centers and national laboratories.

Primary research reaffirmed the market segmentation based on manufacturing process (thermal reduction versus electrolytic versus recycling), validated capacity expansion timeframes and collected outlooks on alloy formulation adoption trends, pricing trends associated with energy costs (natural gas/electricity), Chinese export quota effects and sustainability driven demand shifts.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through production volume mapping and revenue analysis across the value chain. The methodology included:

Identification of 40+ key producers across China, Russia, Israel, the United States, Norway, South Korea, Australia, Brazil, and Kazakhstan

Product mapping across pure magnesium (ingots, granules, powder), magnesium alloys (aluminum-zinc, rare-earth containing, thorium-free), and magnesium compounds (oxide, hydroxide, chloride, carbonate)

Analysis of reported and modeled annual revenues specific to magnesium metal portfolios

Coverage of manufacturers representing 75–80% of global primary production capacity in 2024

Extrapolation using bottom-up (production volume × realized price by country/grade) and top-down (producer revenue validation, trade value reconciliation) approaches to derive segment-specific valuations

無料サンプルをダウンロード

このレポートの無料サンプルを受け取るには、以下のフォームにご記入ください

Global Magnesium Sulfate Market – Forecast till 2027
ケーススタディ
Chemicals and Materials
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.