Location Based Service Market 概要
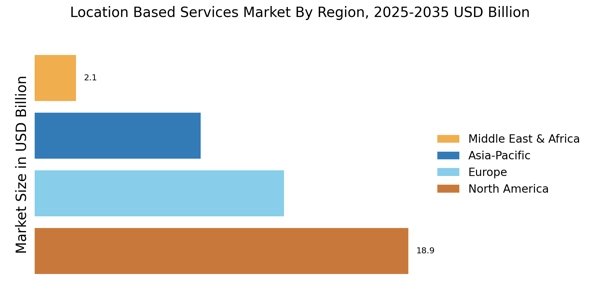
マーケットリサーチフューチャーの分析によると、ロケーションベースサービス市場は2024年に420.1億米ドルと推定されています。ロケーションベースサービス業界は、2025年に481.4億米ドルから2035年までに1880.8億米ドルに成長すると予測されており、2025年から2035年の予測期間中に14.6%の年平均成長率(CAGR)を示しています。
主要な市場動向とハイライト
位置情報サービス市場は、技術の進歩と進化する消費者の好みによって堅調な成長を遂げています。
- 市場は、ユーザーエンゲージメントと体験を向上させる拡張現実の採用が増加しています。
- 北米は最大の市場であり、アジア太平洋はこの分野で最も成長の早い地域として認識されています。
- 現在最大のハードウェアセグメントでは、より高度な位置追跡デバイスへの需要が革新を促進しています。
- パーソナライズされたサービスへの需要の高まりとモバイル技術の進歩が市場を前進させる主要な推進要因です。
市場規模と予測
| 2024年の市場規模 | 42.01(米ドル億) |
| 2035年の市場規模 | 188.08(米ドル億) |
| CAGR(2025 - 2035) | 14.6% |
主要なプレーヤー
Google(米国)、Apple(米国)、Facebook(米国)、HERE Technologies(オランダ)、TomTom(オランダ)、Uber(米国)、Foursquare(米国)、Mapbox(米国)、Waze(イスラエル)



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


