Edge AI Market

エッジAI市場規模、シェアおよび調査報告書:アプリケーション別(スマートシティ、自律走行車、産業オートメーション、ヘルスケア、小売)、展開モデル別(オンプレミス、クラウドベース、ハイブリッド)、コンポーネント別(ハードウェア、ソフトウェア、サービス)、エンドユーザー別(製造、輸送、ヘルスケア、通信、コンシューマーエレクトロニクス)および地域別(北アメリカ、ヨーロッパ、南アメリカ、アジア太平洋、中東およびアフリカ) - 2035年までの業界予測
ID: MRFR/ICT/34256-HCR 100 Pages Aarti Dhapte Last Updated: September 17, 2026
Edge AI Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)21.84%
2024 Market Size$ 7.52 Billion
2025 Market Size$ 9.17 Billion
2035 Market Size$ 66.11 Billion
Key Players
NVIDIA
Intel
IBM
Microsoft
Google
Amazon
Opportunities
  • Rising Adoption of Smart Devices
  • Enhanced Real-Time Data Processing
  • Growing Demand for IoT Integration

Edge AI Market 概要

Market Research Future の分析によれば、エッジ AI 市場規模は 2024 年に 75 億 2,500 万米ドルと推定されています。エッジ AI 業界は、2025 年の 91 億 6,800 万米ドルから 2035 年までに 661 億 1,000 万米ドルに成長すると予測されており、2025 ~ 2035 年の予測期間中に 21.84% の年間平均成長率 (CAGR) を示します。

主要な市場動向とハイライト

エッジAI市場は、技術の進歩とさまざまな分野での需要の増加により、堅調な成長を遂げています。

  • 北アメリカは、技術とインフラへの大規模な投資により、エッジAI市場の最大の市場であり続けています。
  • アジア太平洋地域は、急速な都市化と技術の採用により、最も成長が早い市場として浮上しています。
  • スマートシティは最大のセグメントを占めており、自律走行車はAIと機械学習の進展により最も速い成長を見せています。
  • 主要な市場の推進要因には、リアルタイムデータ処理の向上とスマートデバイスの採用の増加が含まれ、エッジAI市場の未来を形作っています。

市場規模と予測

2024 Market Size k 2024年の市場規模 v 7.525(米ドル十億)
2035 Market Size k 2035年の市場規模 v 66.11(米ドル十億)
CAGR (2025 - 2035) k CAGR(2025 - 2035) v 21.84%

主要なプレーヤー

エヌビディア(私たち)、インテル(私たち)、IBM(US)、Microsoft (US)、Google (US)、Amazon (US)、Qualcomm (US)、Edge Impulse (US)、Siemens (DE)、Hewlett Packard Enterprise (US)

Edge AI Market 運転手

Rising Adoption of Smart Devices

{"k"=>"スマートデバイスの採用の増加", "v"=>"エッジAI市場は、さまざまな分野でスマートデバイスの採用が顕著に増加しているのを目の当たりにしています。消費者と企業がスマート技術を受け入れるにつれて、エッジでの効率的なデータ処理の必要性がより明確になります。スマートホームデバイス、ウェアラブル、産業自動化ツールは、ローカライズされたデータ分析と意思決定を可能にするAI機能を備えるようになっています。この傾向は、ユーザーエクスペリエンスを向上させるだけでなく、エネルギー効率とコスト削減にも寄与します。市場アナリストは、エッジAI市場が堅調なペースで成長し、2029年までに30億USDの潜在的な市場規模に達する可能性があると予測しています。これは、スマートデバイスへのAIの広範な統合によって推進されています。"}

Enhanced Real-Time Data Processing

{"k"=>"リアルタイムデータ処理の強化", "v"=>"エッジAI市場は、リアルタイムデータ処理能力の需要が急増しています。組織が意思決定のために瞬時のデータ分析にますます依存するようになるにつれて、エッジコンピューティングソリューションの必要性が重要になります。このシフトは、製造業やヘルスケアなどの分野で特に顕著であり、タイムリーな洞察が運用効率と患者の結果を改善することにつながります。最近の推定によると、エッジAI市場は2026年までに約12億USDの評価に達する見込みであり、低遅延処理の必要性によって推進されています。データをソースで分析する能力は遅延を最小限に抑え、応答性を向上させるため、エッジAIはさまざまな業界のデジタルトランスフォーメーションの旅において重要な要素となっています。"}

Growing Demand for IoT Integration

{"k"=>"IoT統合の需要の増加", "v"=>"モノのインターネット(IoT)デバイスの普及は、エッジAI市場に大きな影響を与えています。より多くのデバイスが相互接続されるにつれて、エッジで生成されるデータの量は指数関数的に増加します。この傾向は、データをローカルで処理および分析できる高度なAIアルゴリズムを必要とし、帯域幅の使用を削減し、データセキュリティを向上させます。農業やスマートシティなどの産業は、この統合から特に恩恵を受けており、より効率的な資源管理とリアルタイム監視が可能になります。市場予測によると、エッジAI市場は今後数年間で25%以上の年平均成長率を目撃する可能性があり、これは主にAIとIoT技術の統合によって促進されます。"}

Advancements in Machine Learning Algorithms

{"k"=>"機械学習アルゴリズムの進展", "v"=>"エッジAI市場は、機械学習アルゴリズムの継続的な進展によって前進しています。これらの革新により、デバイスはローカルで複雑な計算を実行できるようになり、自律走行車やスマート監視システムなど、即時のフィードバックを必要とするアプリケーションにとって不可欠です。エッジで高度なAIモデルを展開する能力は、パフォーマンスを向上させるだけでなく、クラウドインフラへの依存を減らし、運用コストを低下させます。機械学習技術が進化するにつれて、市場は新しいアプリケーションやユースケースの流入を目撃し、さらなる成長を促進する可能性があります。アナリストは、エッジAIソリューションの市場が大幅に拡大し、2027年までに20億USDを超える可能性があると予測しています。"}

Increased Focus on Data Privacy Regulations

{"k"=>"データプライバシー規制への関心の高まり", "v"=>"エッジAI市場は、データプライバシー規制への関心の高まりによってますます形作られています。データ保護を規制する厳格な法律が施行される中、組織は運用効率を維持しながらコンプライアンスを確保するソリューションを採用することを余儀なくされています。エッジAI市場は、企業が敏感なデータをローカルで処理するための実行可能な道筋を提供し、データ漏洩のリスクを最小限に抑え、ユーザーの信頼を高めます。この傾向は、データプライバシーが最も重要な金融やヘルスケアなどの分野で特に関連性があります。規制の枠組みが進化し続ける中、データセキュリティを優先するエッジAIソリューションの需要が高まると予想されており、2028年までに15億USDに達する市場の拡大につながる可能性があります。"}

市場セグメントの洞察

By Application: Smart Cities (Largest) vs. Autonomous Vehicles (Fastest-Growing)

The Edge AI Market is witnessing a significant distribution in its application segments, with Smart Cities holding a large portion of the market share. This segment is leveraging AI capabilities to enhance urban living through smart infrastructure, energy management, and traffic optimization. Autonomous Vehicles are rapidly gaining momentum, showcasing increasing investment and innovation, which positions them as the fastest-growing segment in the Edge AI Market landscape.

Smart Cities: Dominant vs. Autonomous Vehicles: Emerging

Smart Cities are at the forefront of the Edge AI Market, utilizing advanced analytics and AI-driven solutions to improve urban life experiences and operational efficiencies. This segment's dominance stems from the increasing urbanization and the need for sustainable living solutions. On the other hand, Autonomous Vehicles represent an emerging segment within this market. They are heavily invested in by tech and automotive companies, focusing on safety and efficiency through real-time data processing, making them a key driver for innovation and growth within the Edge AI Market sector.

By Deployment Model: On-Premises (Largest) vs. Cloud-Based (Fastest-Growing)

In the Edge AI Market, the deployment model segment is primarily dominated by the On-Premises approach, which allows organizations to maintain direct control over their data and applications, ensuring enhanced security and compliance. However, Cloud-Based deployment is rapidly gaining traction due to its scalability and cost-effectiveness, catering well to businesses looking to minimize infrastructure investments. The Hybrid model also sees significant interest, enabling flexibility by combining both On-Premises and Cloud-Based solutions to meet varied business needs.

Deployment Model: On-Premises (Dominant) vs. Cloud-Based (Emerging)

On-Premises deployment remains the dominant approach in the Edge AI Market due to its robust security measures, allowing organizations to keep sensitive data within their own infrastructure. This model is particularly favored by industries that prioritize compliance and data privacy, such as healthcare and finance. Conversely, the Cloud-Based model is emerging rapidly, driven by its ability to offer flexibility and a pay-as-you-go pricing model. It appeals to startups and smaller enterprises seeking to leverage AI capabilities without heavy investments in hardware. The Hybrid model strategically positions itself between the two, combining the strengths of both On-Premises and Cloud-Based deployments, making it a vital component of modern Edge AI Market strategies.

By Component: Hardware (Largest) vs. Software (Fastest-Growing)

In the Edge AI Market, the component segment is categorized into hardware, software, and services. Among these, hardware holds the largest market share, driven primarily by the increasing demand for robust computing capabilities at the edge. This comprise advanced processors, sensors, and IoT devices that facilitate data processing close to the source, minimizing latency and enhancing efficiency. Software follows as the fastest-growing segment, owing to the rising integration of AI algorithms and machine learning frameworks. As industries embrace automation and AI, software solutions are being increasingly deployed for data analytics and real-time processing.

Hardware: Specialized Chips (Dominant) vs. Software: AI Frameworks (Emerging)

In the Edge AI Market, specialized chips represent the dominant force within the hardware component, characterized by high-performance processing and low power consumption. These chips are essential for running complex algorithms and support various use cases, from autonomous vehicles to smart manufacturing. On the other hand, AI frameworks in the software category are emerging rapidly, enabling developers to create and deploy AI applications efficiently. With the rising complexity of AI models, the demand for sophisticated software tools that can streamline development processes and enhance model accuracy is increasing. This trend underscores a shifting dynamic where hardware specialists must combine their offerings with complementary software solutions to provide comprehensive edge AI systems.

By End Use: Manufacturing (Largest) vs. Transportation (Fastest-Growing)

In the Edge AI Market, the distribution of market share among various end-use segments reveals manufacturing as the largest segment, showcasing its significant adoption of edge AI technologies. This dominance is driven by the industry's necessity for real-time data processing and automation, leading to enhanced operational efficiency. In contrast, the transportation sector, while currently smaller in market share, is identified as the fastest-growing segment, bolstered by advancements in autonomous driving and smart logistics solutions that rely heavily on edge AI capabilities.

Manufacturing: Dominant vs. Transportation: Emerging

Manufacturing stands as the dominant player within the Edge AI Market, utilizing advanced analytics and machine learning algorithms for predictive maintenance, quality control, and supply chain optimization. The sector's drive towards automation and Industry 4.0 principles fosters the integration of edge AI solutions, making it crucial for smart factories. On the other hand, transportation is an emerging segment, rapidly adopting edge AI technologies to enhance vehicle safety and efficiency. With the rise of connected vehicles and IoT applications, the sector sees burgeoning investments focused on leveraging real-time data for improved traffic management and logistics. This transition is pivotal, indicating a paradigm shift toward smarter mobility solutions.

Edge AI Marketに関する詳細な洞察を得る

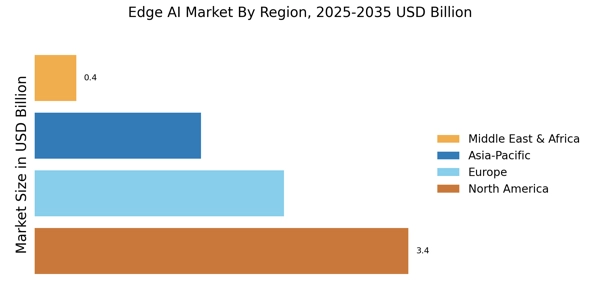
地域の洞察

北米 : イノベーションとリーダーシップのハブ

北米はエッジAI市場の最大の市場であり、世界シェアの約45%を占めています。この地域の成長は、急速な技術進歩、リアルタイム データ処理の需要の増大、政府の支援的な取り組みによって推進されています。大手テクノロジー企業の存在と強固なスタートアップエコシステムが市場の拡大をさらに促進します。 AI イノベーションを促進する規制の枠組みも、状況を形成する上で重要な役割を果たします。米国はエッジ AI 市場をリードしており、カナダが大きく貢献しています。 NVIDIA、Intel、Microsoft などの主要企業が競争環境を支配し、イノベーションと投資を推進しています。この地域は研究開発に注力しており、サイバーセキュリティにも重点を置いているため、エッジ AI 市場テクノロジーのリーダーとしての地位を確立しています。競争環境は、業界リーダー間の継続的な進歩と協力によって特徴付けられます。

ヨーロッパ : 可能性を秘めた新興市場

ヨーロッパではエッジ AI 市場の採用が大幅に増加しており、世界市場シェアの約 30% を占めています。この地域の成長は、スマート製造、ヘルスケア、運輸部門への投資の増加によって促進されています。特に欧州連合からの規制支援は、デジタル変革と AI 統合を重視しており、エッジ AI 市場テクノロジーにとって有利な環境を作り出しています。持続可能性とエネルギー効率への注目も、革新的なソリューションへの需要を促進します。ヨーロッパの主要国にはドイツ、フランス、イギリスがあり、ドイツが最大の市場です。競争環境には、エッジ AI マーケット ソリューションに積極的に投資しているシーメンスや IBM などの主要企業がいます。この地域では公共部門と民間部門の連携が重視されており、イノベーションが促進されている一方、厳格なデータ保護規制により責任ある AI の導入が保証されています。この要因の組み合わせにより、ヨーロッパはエッジ AI 市場の有望な市場として位置付けられます。

アジア太平洋: 急速な成長とイノベーション

アジア太平洋地域はエッジ AI 市場の強国として台頭しており、世界シェアの約 20% を占めています。この地域の成長は、急速な都市化、インターネット普及の増加、スマートデバイスの需要の急増によって推進されています。政府はデジタルインフラの強化とイノベーションの促進を目的としたさまざまな政策により、AIへの取り組みを積極的に推進しています。製造業やヘルスケアを含むこの地域の多様な業界は、効率と意思決定を向上させるためにエッジ AI マーケット ソリューションの採用を増やしています。中国、日本、インドがこの地域の主要国であり、中国が最大の市場です。競争環境は、確立されたテクノロジー大手と革新的な新興企業が混在しているのが特徴です。 Qualcomm や Edge Impulse などの主要企業は、エッジ AI 市場の開発で大きな進歩を遂げています。この地域は研究開発に重点を置いており、人材プールの拡大と相まって、エッジ AI 市場テクノロジーの将来の進歩に有利な立場にあります。

APAC では、オーストラリアのエッジ AI 市場がスマートシティやスマートシティでの導入の増加により勢いを増しています。産業オートメーションプロジェクト。

中東とアフリカ:テクノロジーの新たなフロンティア

中東およびアフリカ (MEA) 地域はエッジ AI 市場で徐々に台頭しており、世界シェアの約 5% を占めています。この成長は、スマートシティ構想、電気通信、ヘルスケアへの投資の増加によって推進されています。政府は AI テクノロジーの重要性を認識しており、イノベーションとデジタル変革をサポートする規制の枠組みが生まれています。この地域の若い人口とインターネット接続の増加により、エッジ AI 市場ソリューションの需要がさらに高まっています。 MEA 地域の主要国には UAE と南アフリカが含まれ、UAE が最大の市場です。競争環境は進化しており、国内および海外のプレーヤーが市場に参入しています。企業は自社のサービスを強化するためにパートナーシップやコラボレーションに注力しています。この地域特有の課題と機会は、エッジ AI 市場イノベーションの肥沃な土壌を提供し、将来の投資にとって魅力的な市場となっています。

Edge AI Market Regional Image

主要企業と競争の洞察

現在、エッジ AI 市場は、急速な技術の進歩とリアルタイム データ処理に対する需要の増加によって、ダイナミックな競争環境が特徴です。 NVIDIA (米国)、Intel (米国)、Microsoft (米国) などの大手企業が最前線に立ち、イノベーションと戦略的パートナーシップにおける強みを活用して市場での地位を高めています。 NVIDIA (米国) は、エッジでの AI 機能を促進する最先端のハードウェアおよびソフトウェア ソリューションの開発に重点を置いており、一方、Intel (米国) は、エッジ コンピューティング アプリケーション向けにカスタマイズされたプロセッサの広範なポートフォリオを強調しています。 Microsoft (米国) は、AI 機能を統合してさまざまな業界全体の運用を最適化する Azure IoT プラットフォームを通じて、戦略的に自社の地位を確立しています。これらの戦略を総合すると、技術革新と協力的なエコシステムがますます中心となる競争環境に貢献します。ビジネス戦術の面では、企業は業務効率を高めるために製造の現地化とサプライチェーンの最適化を進めています。エッジ AI 市場は、確立されたプレーヤーと新興の新興企業が混在し、適度に細分化されているように見えます。この構造により、多様な競争戦略が可能になり、主要企業が技術の進歩と市場へのリーチを通じて大きな影響力を発揮します。これらの企業の共同行動により、進化する消費者の需要と技術トレンドに対応する環境が形成されます。 2025 年 9 月、NVIDIA (米国) は、高度な機械学習機能を統合してリアルタイム データ処理を強化する、最新の AI 駆動エッジ コンピューティング プラットフォームの発売を発表しました。この戦略的動きは、NVIDIA (米国) が、特に自動運転車やスマート シティなどの分野で、エッジ AI ソリューションに対する需要の増大でより大きなシェアを獲得できる立場にあるため、重要です。このプラットフォームの導入は、NVIDIA のイノベーションへの取り組みと、市場のニーズに効果的に対応する能力を強調しています。 2025 年 8 月、インテル (米国) は、エッジ AI テクノロジーを活用したスマート製造ソリューションの開発を目的としたシーメンス (ドイツ) との新たなパートナーシップを発表しました。このコラボレーションは、インテルのハードウェア専門知識とシーメンスの産業用ソフトウェア機能を組み合わせ、製造プロセスに革命をもたらす可能性があるため極めて重要です。このパートナーシップは、業界を超えたコラボレーションの広範な傾向を反映しており、これにより、この分野の業務効率が向上し、技術の進歩が促進されると考えられます。 2025 年 7 月、Microsoft (米国) は、エッジ デバイス向けに特別に設計された高度な分析と AI 機能を統合することにより、Azure IoT サービスを拡張しました。この戦略的強化は、マイクロソフト (米国) がエッジ コンピューティングの力を活用しようとする企業の増大するニーズに応える包括的なソリューションを提供できるようにするため、非常に重要です。 Microsoft (米国) は AI 統合に注力することで、自社を業界のリーダーとしての地位を確立しています。デジタル変革業界の競争力をさらに強化します。 2025 年 10 月の時点で、エッジ AI 市場では、デジタル化、持続可能性、AI テクノロジーの統合を重視するトレンドが見られます。主要企業間の戦略的提携により、競争環境が形成され、イノベーションが促進され、製品提供が強化されています。今後、競争上の差別化は価格ベースの戦略から、イノベーション、技術の進歩、サプライチェーンの信頼性にますます重点を置くようになると予想されます。この変化は、企業が急速に進化する市場で競争力を維持するために研究開発に投資する必要があることを示唆しています。

Edge AI Market市場の主要企業には以下が含まれます

Recent Industry Developments

  • 2024 年第 2 四半期: Edge Impulse がエッジ AI 開発プラットフォームを拡張するためにシリーズ C で 6,000 万ドルを調達エッジ AI 開発ツールの大手プロバイダーである Edge Impulse は、製品イノベーションとエッジ デバイスに AI モデルを展開するためのプラットフォームの世界的拡張を加速するために、6,000 万ドルのシリーズ C 資金調達ラウンドを発表しました。
  • 2024 年第 2 四半期: NVIDIA がエッジ AI アプリケーション向けの新しい Jetson Orin Nano モジュールを発売NVIDIA は、ロボティクス、スマート カメラ、産業オートメーション分野をターゲットとして、低電力エッジ デバイスに高度な AI 機能をもたらすように設計された Jetson Orin Nano モジュールを発表しました。
  • 2024 年第 2 四半期: Microsoft と Qualcomm がエッジにおけるオンデバイス AI の提携を発表Microsoft と Qualcomm は、エンタープライズおよび IoT 顧客向けのリアルタイム AI 処理を強化することを目的として、Qualcomm の AI チップを Microsoft Azure のエッジ サービスと統合する戦略的パートナーシップを締結しました。
  • 2024年第3四半期: シーメンスがミュンヘンに新しいエッジAI研究施設を開設シーメンスは、リアルタイムを活用した次世代の産業オートメーション ソリューションを開発するため、ミュンヘンに専用のエッジ AI 研究センターを開設しました機械学習端で。
  • 2024 年第 3 四半期: ABB が工場向けエッジ AI を活用した予知保全プラットフォームを発表ABB は、製造現場でのリアルタイムの機器監視と故障予測を直接可能にする、製造における予知保全のための新しいエッジ AI プラットフォームを導入しました。
  • 2024年第3四半期: サムスンがエッジAIスタートアップのDeepSenseを金額非公開で買収サムスン電子は、オンデバイスインテリジェンスのポートフォリオを強化するために、スマートデバイス向けのエッジAIアルゴリズムを専門とする新興企業DeepSenseの買収を完了した。
  • 2024 年第 4 四半期: エッジ AI マーケットのチップメーカー Kneron がシリーズ B 資金で 4,900 万ドルを調達エネルギー効率の高いエッジ AI チップの開発者である Kneron は、生産を拡大し、自動車およびセキュリティ市場に拡大するためにシリーズ B 資金で 4,900 万ドルを確保しました。
  • 2024 年第 4 四半期: ボッシュ、小売分析用のエッジ AI 対応スマート カメラを発表ボッシュは、小売環境にリアルタイムの顧客分析と紛失防止を提供するように設計された、エッジ AI 機能を搭載した新しいスマート カメラを発売しました。
  • 2025 年第 1 四半期: アマゾン ウェブ サービスが AWS IoT Greengrass のエッジ AI 統合を発表AWS は、IoT Greengrass プラットフォーム向けの新しいエッジ AI 機能を発表しました。これにより、顧客は機械学習モデルをエッジデバイスに直接デプロイして、より迅速でローカライズされた意思決定が可能になります。
  • 2025 年第 1 四半期: インテル、エッジ AI マーケット ソリューション担当の新しい副社長を任命インテルはプリヤ ナタラジャン博士をエッジ AI マーケット ソリューション担当副社長に任命し、彼女にエッジ コンピューティングと AI 製品開発に関する会社の戦略を主導する任務を与えました。
  • 2025年第2四半期: ソニー、産業オートメーション向けのエッジAIセンサープラットフォームを発売ソニーは、産業オートメーションを目的とした新しいエッジ AI センサー プラットフォームをリリースし、製造ラインで直接リアルタイムの画像分析とプロセスの最適化を可能にしました。
  • 2025 年第 2 四半期: エッジ AI 市場のスタートアップ BrainChip がヒュンダイとの大規模な自動車契約を獲得BrainChip は、今後の車両モデルに搭載される次世代運転支援システム用のエッジ AI プロセッサを供給するため、ヒュンダイと複数年契約を締​​結しました。

今後の見通し

Edge AI Market 今後の見通し

エッジAI市場は、2025年から2035年までの期間に21.84%のCAGRで成長すると予測されており、IoT、データ処理、リアルタイム分析の進展に支えられています。

2035年までに、エッジAI市場はグローバルな技術インフラの重要な要素となると期待されています。

市場セグメンテーション

Edge AI Market End Use Outlook

  • k
  • エッジAI市場の最終用途の展望
  • v
  • 製造
  • 輸送
  • ヘルスケア
  • 通信
  • コンシューマーエレクトロニクス

Edge AI Market Component Outlook

  • k
  • エッジAI市場のコンポーネントの展望
  • v
  • ハードウェア
  • ソフトウェア
  • サービス

Edge AI Market Application Outlook

  • k
  • エッジAI市場のアプリケーションの展望
  • v
  • スマートシティ
  • 自律走行車
  • 産業オートメーション
  • ヘルスケア
  • 小売

Edge AI Market Deployment Model Outlook

  • k
  • エッジAI市場の展開モデルの展望
  • v
  • オンプレミス
  • クラウドベース
  • ハイブリッド

レポートの範囲

Frequently Asked Questions

2035年までのエッジAI市場の予測市場評価額はどのくらいですか?

エッジAI市場は2035年までに661.1億米ドルの評価額に達すると予測されています。

2024年のエッジAI市場の市場評価額はどのくらいでしたか?

2024年、エッジAI市場は75.25億米ドルの評価額でした。

2025年から2035年の予測期間中のエッジAI市場の期待CAGRはどのくらいですか?

2025年から2035年の予測期間中のエッジAI市場の期待CAGRは21.84%です。

エッジAI市場の主要なプレーヤーと見なされる企業はどれですか?

エッジAI市場の主要プレーヤーには、NVIDIA、Intel、IBM、Microsoft、Google、Amazon、Qualcomm、Edge Impulse、Siemens、Hewlett Packard Enterpriseが含まれます。

エッジAI市場の主なアプリケーションセグメントは何ですか?

主なアプリケーションセグメントには、スマートシティ、自動運転車、産業オートメーション、ヘルスケア、小売が含まれます。

産業オートメーションセグメントは市場評価額の観点でどのようにパフォーマンスを発揮していますか?

産業オートメーションセグメントは、2024年の20億米ドルから2035年までに180億米ドルに成長すると予測されています。

2024年のクラウドベースの展開モデルの市場評価額はどのくらいですか?

クラウドベースの展開モデルは2024年に20億米ドルの評価額でした。

エッジAI市場におけるハードウェアコンポーネントの予測成長はどのくらいですか?

ハードウェアコンポーネントは、2024年の25億米ドルから2035年までに220億米ドルに成長すると予測されています。

2035年までに最も高い予測評価額を持つエンドユースセグメントはどれですか?

コンシューマーエレクトロニクスのエンドユースセグメントは、2035年までに206億米ドルに達すると予測されています。

ヘルスケアアプリケーションセグメントの期待される市場パフォーマンスはどのようなものですか?
ヘルスケアアプリケーションセグメントは、2024年の15億米ドルから2035年までに120億米ドルに成長すると予想されています。
著者
Author Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed engineering journals, technical publications, and authoritative technology organizations. Key sources included the US National Institute of Standards and Technology (NIST), European Commission's AI Office, International Organization for Standardization (ISO/IEC JTC 1/SC 42 - Artificial Intelligence), IEEE Standards Association, Semiconductor Industry Association (SIA), European Semiconductor Industry Association (ESIA), International Data Corporation (MRFR), MRFR Research, MRFR Global Institute, World Economic Forum (WEF) Centre for the Fourth Industrial Revolution, Organisation for Economic Co-operation and Development (OECD) AI Policy Observatory, United Nations Industrial Development Organization (UNIDO), US Bureau of Economic Analysis, Eurostat Digital Economy and Society Statistics, China Academy of Information and Communications Technology (CAICT), Japan Ministry of Economy Trade and Industry (METI) AI Strategy Reports, and national digital transformation agencies from key markets. These sources were used to collect deployment statistics, regulatory framework data, technical safety studies, adoption trends, and competitive landscape analysis for hardware accelerators, edge AI software platforms, integrated systems, and professional services.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consulted were CEOs, VPs of Edge Computing Strategy, Chief AI Officers, leaders of IoT product development, and commercial directors from semiconductor manufacturers, edge device OEMs, cloud service providers, and AI software vendors. Chief Technology Officers, VP of Manufacturing Operations, directors of smart city programs, heads of fleet management, healthcare IT directors, and procurement leads from automotive manufacturers, industrial automation firms, telecommunications operators, healthcare systems, and retail chains comprised demand-side sources. Market segmentation was verified, product roadmap timelines were confirmed, and insights regarding technology adoption patterns, pricing strategies, and integration challenges were obtained through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (38%), Europe (25%), Asia-Pacific (28%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through revenue mapping and deployment volume analysis. The methodology included:

Identification of 60+ key technology providers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across AI accelerators (GPUs, TPUs, NPUs), edge AI software frameworks, integrated hardware-software systems, and managed services

Analysis of reported and modeled annual revenues specific to edge AI portfolios

Coverage of manufacturers and service providers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (device deployment volume × ASP by country/region) and top-down (vendor revenue validation) approaches to derive segment-specific valuations across Smart Cities, Autonomous Vehicles, Industrial Automation, Healthcare, and Retail applications

無料サンプルをダウンロード

このレポートの無料サンプルを受け取るには、以下のフォームにご記入ください

Global Diameter Signaling Market
ケーススタディ
Information and Communications Technology
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.