Marché des Véhicules Autonomes

Taille, Part et Rapport de Recherche du Marché des Véhicules Autonomes par Type (Totalement Autonome, Semi-Autonome), par Type de Véhicule (Voitures Particulières, Véhicules Commerciaux) et par Région (Amérique du Nord, Europe, Amérique du Sud, Asie-Pacifique, Moyen-Orient et Afrique) - Prévisions de l'Industrie jusqu'en 2035.
ID: MRFR/SEM/0514-CR 200 Pages Aarti Dhapte, Shubham Munde Last Updated: September 21, 2026
Autonomous Vehicles Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)21.2%
2024 Market Size$ 28.6 Billion
2025 Market Size$ 34.66 Billion
2035 Market Size$ 237.12 Billion
Key Players
Waymo
Tesla
Cruise
Aurora
Baidu
Nuro
Opportunities
  • Increased Investment in R&D
  • Regulatory Support and Frameworks
  • Growing Demand for Mobility Solutions

Marché des Véhicules Autonomes Résumé

Selon l'analyse de MRFR, la taille du marché des véhicules autonomes était estimée à 28,6 milliards USD en 2024. L'industrie des véhicules autonomes devrait croître de 34,66 milliards USD en 2025 à 237,12 milliards USD d'ici 2035, affichant un taux de croissance annuel composé (CAGR) de 21,2 % pendant la période de prévision 2025 - 2035.

Principales tendances et faits saillants du marché

Le marché des véhicules autonomes est prêt à connaître une croissance substantielle, soutenue par les avancées technologiques et l'évolution des préférences des consommateurs.

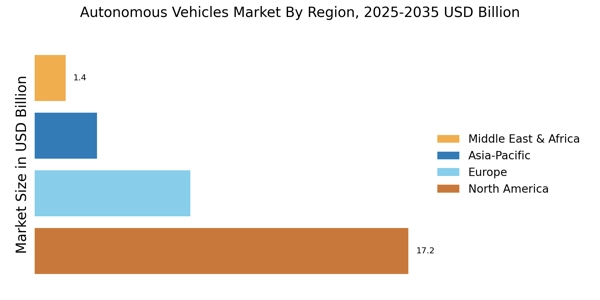
  • L'Amérique du Nord reste le plus grand marché des véhicules autonomes, montrant un investissement robuste dans la R&D et l'infrastructure.
  • La région Asie-Pacifique émerge comme le marché à la croissance la plus rapide, propulsée par l'urbanisation croissante et la demande de solutions de mobilité innovantes.
  • Les véhicules entièrement autonomes dominent le marché, tandis que les véhicules semi-autonomes connaissent la croissance la plus rapide grâce aux avancées en IA et en apprentissage automatique.
  • Les principaux moteurs du marché incluent l'augmentation des investissements en R&D et le soutien réglementaire, qui sont essentiels pour favoriser l'innovation et l'acceptation par les consommateurs.

Taille du marché et prévisions

2024 Market Size 28,6 (milliards USD)
2035 Market Size 237,12 (milliards USD)
CAGR (2025 - 2035) 21,2 %

Principaux acteurs

Waymo (US), Tesla (US), Cruise (US), Aurora (US), Baidu (CN), Nuro (US), Mobileye (IL), Zoox (US), Pony.ai (CN)
Marché des Véhicules Autonomes conducteurs

Increased Investment in R&D

The Autonomous Vehicles Market is witnessing a surge in investment directed towards research and development. Major automotive manufacturers and tech companies are allocating substantial resources to innovate and enhance autonomous driving technologies. In 2025, it is estimated that investments in R&D for autonomous vehicles could reach approximately 100 billion dollars, reflecting a commitment to advancing safety, efficiency, and user experience. This influx of capital is likely to accelerate the development of advanced sensors, artificial intelligence, and machine learning algorithms, which are crucial for the functionality of autonomous vehicles. As these technologies mature, they may lead to more reliable and safer autonomous systems, thereby fostering greater consumer trust and acceptance in the Autonomous Vehicles Industry.

Regulatory Support and Frameworks

Growing Demand for Mobility Solutions

Advancements in AI and Machine Learning

Environmental Sustainability Initiatives

Aperçu des segments de marché

The vehicle type segment of the Autonomous Vehicles Market is predominantly characterized by Passenger Cars, which hold a significant share compared to Commercial Vehicles. Passenger Cars are widely recognized for their advanced autonomous features and have been the focal point for major automotive manufacturers and technology firms. Meanwhile, Commercial Vehicles are progressively gaining traction, driven by increasing investments in autonomous technology tailored for logistics and transportation sectors. This reflects diversification across the autonomous vehicles industry. As the market evolves, the growth trajectory of Commercial Vehicles is fueled by several key drivers. Rising demand for efficient delivery systems and automated transport solutions is pushing businesses to adopt autonomous technology. Additionally, regulatory support and technological advancements in sensor and AI capabilities further accelerate the development of autonomous Commercial Vehicles. As automation becomes increasingly vital in improving productivity and safety, this segment is poised for rapid growth in the coming years.

Obtenez des informations plus détaillées sur Marché des Véhicules Autonomes

Aperçu régional

Amérique du Nord : Pôle d'Innovation et de Leadership

L'Amérique du Nord est le plus grand marché des véhicules autonomes, détenant environ 60 % de la part de marché mondiale. La croissance de la région est propulsée par des avancées technologiques, des investissements significatifs de la part des acteurs clés et des cadres réglementaires favorables. Le gouvernement américain a été proactif dans l'établissement de directives qui facilitent les tests et le déploiement de véhicules autonomes, stimulant ainsi la demande du marché. Le paysage concurrentiel est dominé par de grandes entreprises telles que Waymo, Tesla et Cruise, qui sont à la pointe de l'innovation. La présence de fabricants automobiles établis et de géants de la technologie renforce les capacités de la région dans le développement de technologies autonomes. De plus, les partenariats entre les entreprises automobiles et technologiques favorisent des avancées rapides dans ce secteur.

Marché des Véhicules Autonomes Regional Image

Acteurs clés et aperçu concurrentiel

The Autonomous Vehicles Market features a moderately fragmented landscape driven by innovation, collaboration, and strategic expansion. Market leaders continue to shape the autonomous vehicles market size trajectory through technology investments, partnerships, and global expansion strategies. Key players such as Waymo (US), Tesla (US), and Baidu (CN) are at the forefront, each adopting distinct strategies that shape the market's evolution. Waymo (US) focuses on extensive testing and deployment of its autonomous ride-hailing services, while Tesla (US) emphasizes the integration of advanced AI technologies into its vehicles, enhancing user experience and safety. Baidu (CN), on the other hand, is leveraging its strong AI capabilities to develop autonomous driving solutions tailored for the Chinese market, indicating a regional focus that complements its global ambitions. The business tactics employed by these companies reflect a concerted effort to optimize operations and enhance market presence. Localizing manufacturing and supply chain optimization are prevalent strategies, particularly as companies seek to mitigate risks associated with global supply chain disruptions. The market appears moderately fragmented, with a mix of established players and emerging startups, each contributing to a competitive structure that fosters innovation and collaboration.
In August Waymo (US) announced the expansion of its autonomous ride-hailing service to additional cities, a strategic move aimed at increasing its market share and enhancing service accessibility. This expansion not only signifies Waymo's commitment to scaling its operations but also positions it to capture a larger customer base in urban areas, where demand for autonomous services is surging. The implications of this move suggest a potential shift in consumer behavior towards embracing autonomous mobility solutions.
In September Tesla (US) unveiled its latest software update, which includes enhanced features for its Full Self-Driving (FSD) system. This update is pivotal as it underscores Tesla's continuous investment in AI and machine learning, aiming to improve safety and driving efficiency. The strategic importance of this development lies in Tesla's ability to maintain its competitive edge through technological innovation, which is likely to attract more consumers to its brand.
In July Baidu (CN) entered into a partnership with a leading automotive manufacturer to co-develop next-generation autonomous vehicles. This collaboration is significant as it combines Baidu's AI expertise with the manufacturing capabilities of its partner, potentially accelerating the development and deployment of autonomous technologies in the market. Such strategic alliances are indicative of a broader trend where companies are increasingly recognizing the value of collaboration to enhance their technological capabilities and market reach.
As of October the competitive trends in the Autonomous Vehicles Market are heavily influenced by digitalization, sustainability, and the integration of AI technologies. Strategic alliances are becoming a cornerstone of competitive strategy, enabling companies to pool resources and expertise. Looking ahead, it is anticipated that competitive differentiation will increasingly pivot from traditional price-based competition to a focus on innovation, technological advancements, and the reliability of supply chains. This shift may redefine the parameters of success in the market, emphasizing the importance of agility and responsiveness to consumer needs.

Les principales entreprises du marché Marché des Véhicules Autonomes incluent

Recent Industry Developments

  • Q3 2026: Tesla (US): Tesla deployed more than 40 purpose-built Cybercabs without steering wheels or brake pedals for limited autonomous taxi service in Austin, marking a new vehicle platform for its Robotaxi operations.

  • Q3 2026: Aurora (US): Aurora launched second-generation driverless trucks across its U.S. commercial network, with manufacturing partner Roush targeting a 1,000-truck annual production run-rate, expanding autonomous freight capacity for commercial deployment.

  • Q3 2026: Baidu (CN): Apollo Go reached 28 cities globally and accumulated more than 350 million autonomous kilometers, including over 240 million fully driverless kilometers, while expanding operations and testing across Europe, the Middle East, and Asia.

  • Q3 2026: Mobileye (IL): Mobileye reported continued preparations for commercial robotaxi services with Volkswagen Group's MOIA and expanded work on vehicle supply, system installation, fleet logistics, rider applications, and customer-facing mobility infrastructure.

  • Recent developments across funding, partnerships, regulatory approvals, and pilot deployments underscore accelerating autonomous vehicle advancements and rising confidence in commercial scalability.

  • Q2 2024: Waymo expands autonomous ride-hailing service to Los Angeles Waymo, Alphabet's self-driving unit, launched its autonomous ride-hailing service in Los Angeles, marking its first major expansion outside of Phoenix and San Francisco. The company began offering fully driverless rides to the public in select areas of the city.
  • Q2 2024: Aurora Innovation secures $820 million in new funding to launch autonomous trucking operations Aurora Innovation announced it raised $820 million in a new funding round to support the commercial launch of its autonomous trucking business, with plans to begin driverless freight operations in Texas by the end of 2024.
  • Q2 2024: Cruise names new CEO as GM seeks to revive robotaxi business General Motors appointed Marc Whitten as the new CEO of Cruise, its autonomous vehicle subsidiary, following a series of safety incidents and a temporary suspension of operations in late 2023.
  • Q1 2024: Mobileye and Volkswagen announce partnership to develop next-generation autonomous driving systems Mobileye, an Intel company, entered a strategic partnership with Volkswagen to co-develop advanced autonomous driving systems for future Volkswagen vehicles, targeting deployment in Europe and China.
  • Q1 2024: Baidu receives regulatory approval to expand driverless taxi service in Wuhan Baidu was granted regulatory approval by Chinese authorities to expand its Apollo Go driverless taxi service in Wuhan, allowing the company to operate fully autonomous vehicles without safety drivers in a larger area of the city.
  • Q2 2024: Pony.ai raises $100 million in new funding to accelerate autonomous vehicle commercialization Pony.ai secured $100 million in a new funding round to support the commercialization of its autonomous vehicle technology, with a focus on expanding its robotaxi and autonomous trucking services in China.
  • Q1 2024: Tesla receives regulatory approval to launch Full Self-Driving beta in Europe Tesla obtained regulatory approval to begin limited public testing of its Full Self-Driving (FSD) beta software in select European countries, marking the company's first official FSD deployment outside North America.
  • Q2 2024: Hyundai opens new autonomous vehicle R&D center in Singapore Hyundai Motor Group inaugurated a new research and development center in Singapore dedicated to autonomous vehicle technologies, aiming to accelerate the development and deployment of self-driving cars in Southeast Asia.
  • Q1 2024: Nuro announces partnership with Walmart to expand autonomous delivery services Nuro entered into a partnership with Walmart to expand its autonomous delivery services to additional cities in the United States, leveraging Nuro's latest generation of driverless delivery vehicles.
  • Q2 2024: Zoox begins testing autonomous robotaxis on public roads in Las Vegas Amazon-owned Zoox started public road testing of its purpose-built autonomous robotaxis in Las Vegas, marking the company's first deployment outside California.
  • Q1 2024: Apple hires former Ford executive to lead autonomous vehicle project Apple appointed Doug Field, a former Ford and Tesla executive, to lead its autonomous vehicle project, signaling renewed commitment to developing self-driving car technology.
  • Q2 2024: TuSimple completes first fully driverless semi-truck run on public roads in Japan TuSimple announced it successfully completed Japan's first fully driverless semi-truck run on public roads, demonstrating its autonomous technology in partnership with a major Japanese logistics company.

Perspectives d'avenir

Marché des Véhicules Autonomes Perspectives d'avenir

La part de marché des véhicules autonomes devrait croître à un taux de croissance annuel composé (CAGR) de 21,2 % de 2024 à 2035, soutenue par les avancées technologiques, le soutien réglementaire et la demande croissante des consommateurs.

De nouvelles opportunités résident dans :

  • Développement de systèmes de communication intégrés véhicule-infrastructure.
  • Expansion des plateformes de covoiturage autonome dans les zones urbaines.
  • Investissement dans des solutions de maintenance prédictive alimentées par l'IA pour les flottes.

D'ici 2035, les tendances du marché des véhicules autonomes devraient être une force dominante dans le transport.

Segmentation du marché

Perspectives de marché des véhicules autonomes

  • Entièrement autonome
  • Semi-autonome

Perspectives du marché des véhicules autonomes par type de véhicule

  • Voitures particulières
  • Véhicules utilitaires

Portée du rapport

MARKET SIZE 2024 28.6(USD Billion)
MARKET SIZE 2025 34.66(USD Billion)
MARKET SIZE 2035 237.12(USD Billion)
COMPOUND ANNUAL GROWTH RATE (CAGR) 21.2% (2025 - 2035)
REPORT COVERAGE Revenue Forecast, Competitive Landscape, Growth Factors, and Trends
BASE YEAR 2024
Market Forecast Period 2025 - 2035
Historical Data 2019 - 2024
Market Forecast Units USD Billion
Key Companies Profiled Waymo (US), Tesla (US), Cruise (US), Aurora (US), Baidu (CN), Nuro (US), Mobileye (IL), Zoox (US), Pony.ai (CN)
Segments Covered Type, Vehicle Type, Regional
Key Market Opportunities Integration of advanced artificial intelligence for enhanced safety and efficiency in the Autonomous Vehicles Market.
Key Market Dynamics Technological advancements and regulatory shifts drive competitive dynamics in the Autonomous Vehicles Industry.
Countries Covered North America, Europe, APAC, South America, MEA

Frequently Asked Questions

Quelle est la valorisation actuelle du marché des véhicules autonomes ?
En 2024, le marché des véhicules autonomes était évalué à 28,6 milliards USD.
Quelle est la taille de marché projetée pour le marché des véhicules autonomes d'ici 2035 ?
Le marché devrait atteindre 237,12 milliards USD d'ici 2035.
Quel est le CAGR attendu pour le marché des véhicules autonomes pendant la période de prévision 2025 - 2035 ?
Le CAGR attendu pour le marché des véhicules autonomes entre 2025 et 2035 est de 21,2 %.
Quels segments sont inclus dans le marché des véhicules autonomes ?
Les segments de marché comprennent les véhicules entièrement autonomes et semi-autonomes, ainsi que les voitures particulières et les véhicules commerciaux.
Quelles sont les évaluations projetées pour les véhicules entièrement autonomes et semi-autonomes d'ici 2035 ?
D'ici 2035, les véhicules entièrement autonomes devraient atteindre 100,0 milliards USD, tandis que les véhicules semi-autonomes pourraient atteindre 137,12 milliards USD.
Comment les évaluations des voitures particulières et des véhicules utilitaires se comparent-elles sur le marché des véhicules autonomes ?
Les voitures particulières devraient atteindre 180,0 milliards USD, tandis que les véhicules commerciaux pourraient atteindre 57,12 milliards USD d'ici 2035.
Qui sont les acteurs clés du marché des véhicules autonomes ?
Les acteurs clés incluent Waymo, Tesla, Cruise, Aurora, Baidu, Nuro, Mobileye, Zoox et Pony.ai.
Quel rôle Tesla joue-t-il sur le marché des véhicules autonomes ?
Tesla est reconnu comme un acteur majeur sur le marché des véhicules autonomes, contribuant de manière significative à l'innovation et à la croissance du marché.
Quelle est l'importance de la croissance projetée de 2024 à 2035 sur le marché des véhicules autonomes ?
Le marché devrait passer de 28,6 milliards USD en 2024 à 237,12 milliards USD d'ici 2035, indiquant une expansion robuste.
Comment la performance du marché des Véhicules Commerciaux se compare-t-elle à celle des Voitures Particulières ?
Alors que les voitures particulières devraient dominer avec 180,0 milliards USD, les véhicules commerciaux devraient atteindre 57,12 milliards USD d'ici 2035.
Auteur
Author Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Co-Author Co-Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed engineering journals, technical publications, and authoritative automotive and transportation organizations. Key sources included the US National Highway Traffic Safety Administration (NHTSA), US Department of Transportation (DOT), Federal Motor Carrier Safety Administration (FMCSA), European Union Agency for Railways (ERA), European Commission Mobility & Transport, European Road Safety Observatory (ERSO), Society of Automotive Engineers (SAE International), International Organization for Standardization (ISO), Insurance Institute for Highway Safety (IIHS), National Transportation Safety Board (NTSB), Bureau of Transportation Statistics (BTS), International Transport Forum (ITF), World Road Association (PIARC), China Ministry of Industry and Information Technology (MIIT), Japan Ministry of Land, Infrastructure, Transport and Tourism (MLIT), and national motor vehicle regulatory authorities from key markets. These sources were used to collect vehicle safety statistics, regulatory approval data, autonomous testing mileage reports, demographic trends, and market landscape analysis for fully autonomous and semi-autonomous passenger cars and commercial vehicles.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. From autonomous vehicle manufacturers, OEMs, LiDAR/sensor suppliers, and mobility service providers, supply-side sources comprised CEOs, VPs of Autonomous Driving Programs, regulatory affairs leaders, and fleet operations directors. The demand-side sources included procurement leads from commercial fleet operators, public transit authorities, and mobility-as-a-service (MaaS) providers, as well as fleet managers, logistics directors, urban transportation planners, and ride-sharing operators. Market segmentation was validated, autonomous driving roadmap timelines were confirmed, and insights regarding technology adoption patterns, fleet deployment strategies, and regulatory compliance dynamics were obtained through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Region: North America (40%), Europe (22%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and vehicle deployment volume analysis. The methodology included:

Identification of 50+ key manufacturers and technology developers across North America, Europe, Asia-Pacific, and Middle East & Africa

Product mapping across fully autonomous (Level 4-5) and semi-autonomous (Level 2-3) systems for passenger cars and commercial vehicles

Analysis of reported and modeled annual revenues specific to autonomous vehicle R&D investments and commercial deployment portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (vehicle deployment volume × technology cost by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations

Télécharger l'échantillon gratuit

Veuillez remplir le formulaire ci-dessous pour recevoir un échantillon gratuit de ce rapport

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.