Superalloys Market (2026 - 2035)

Superalloys Market Research Report Information By Base Material (Nickel-based, Iron-based, Cobalt-based, and Others (Titanium-based and Niobium-based)), and By End-user Industry (Aerospace and Defense, Power Generation, Oil and Gas, Automotive, Electronics, and Other Industries (Medical Devices, Marine, Chemical, Electronics)) – Forecast Till 2035.
ID: MRFR/CnM/6003-CR 174 Pages Chitranshi Jaiswal Last Updated: September 09, 2026
Superalloys Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.69%
2025 Market SizeUSD 31.28 Billion
2035 Market SizeUSD 59.75 Billion
Key Players
Precision Castparts Corp.
Carpenter Technology Corporation
ATI Inc.
Haynes International, Inc.
thyssenkrupp AG
PROTERIAL, Ltd.
Opportunities
  • Powder Metallurgy and Additive Supply Chains
  • Closed-Loop Revert and Recycling Economics
  • Emerging Market Localization

Superalloys Market Resumen

Según el análisis de Market Research Future, el mercado de superaleaciones en forma de producto fue valorado en 6,892.9 millones de USD en 2024. Se proyecta que la industria de sonoboyas crecerá de 7,533.94 millones de USD en 2025 a 18,332.59 millones de USD para 2035, exhibiendo una tasa de crecimiento anual compuesta (CAGR) del 9.3% durante el período de pronóstico (2025 - 2035).

Tendencias clave del mercado y aspectos destacados

El Mercado de Superaleaciones está siendo remodelado por varias tendencias a nivel de confluencia relacionadas con la demanda de aeroespacial y defensa, necesidades de transición energética, fabricación avanzada, innovación en materiales de aleación, sostenibilidad y reestructuración de la cadena de suministro regional.

  • El sector de petróleo y gas continúa dependiendo de las superaleaciones para herramientas de fondo de pozo, equipos de cabezal de pozo y componentes de alta presión / alta corrosión, especialmente en campos de aguas profundas y de gas ácido.
  • La fabricación aditiva (AM), o impresión 3D de metal, es indudablemente la tendencia más transformadora en superaleaciones hoy en día.
  • Los OEM y proveedores están calificando cada vez más superaleaciones basadas en níquel para procesos de AM basados en láser y haz de electrones, especialmente para prototipos de palas de turbina y cámaras de combustión y producción en series de bajo volumen.
  • La frontera de la ciencia de materiales está avanzando más allá de las superaleaciones clásicas basadas en níquel, hierro y cobalto hacia aleaciones de alta entropía (HEAs) y otras composiciones de “nueva generación”.

Tamaño del mercado y previsión

Tamaño del mercado 2024 6,892.9 (millones de USD)
Tamaño del mercado 2035 18,332.59 (millones de USD)
CAGR (2025 - 2035) 9.3%

Principales jugadores

Precision Castparts Corp, Aubert & Duval, HAYNES INTERNATIONAL, Nippon Yakin Kogyo Co., Ltd, Universal Stainless (Aperam), VDM Metals, Cannon‑Muskegon, CRS Holdings, LLC., thyssenkrupp Materials Trading GmbH, Allegheny Technologies Incorporated (ATI).
Superalloys Market Treiber

Aumento de la demanda en la industria aeroespacial y de defensa

El aumento del gasto en aeroespacial y defensa es un factor clave para el mercado de superaleaciones, ya que estos sectores dependen en gran medida de materiales que pueden soportar temperaturas extremas, presión y estrés mecánico. El gasto en defensa ha superado los 2718 mil millones de USD, reflejando tensiones geopolíticas aumentadas y esfuerzos de modernización militar a largo plazo. Este aumento sostenido en el gasto apoya la demanda de materiales de alto rendimiento utilizados en motores de aeronaves, turbinas de gas, sistemas de propulsión naval y plataformas espaciales, áreas donde las superaleaciones son esenciales.

Aumento del uso de turbinas de gas en la generación de energía y las industrias de petróleo y gas

El aumento en el despliegue de turbinas de gas en la generación de energía y operaciones de petróleo y gas es un motor de crecimiento clave para el mercado de superaleaciones. Las turbinas de gas operan a temperaturas extremadamente altas y tensiones de rotación, especialmente en plantas de energía de ciclo combinado, plataformas en alta mar, instalaciones de GNL y sistemas de compresión de tuberías. Las superaleaciones, en particular las de base níquel, son esenciales para las palas de turbina, álabes, cámaras de combustión y discos porque pueden mantener la resistencia, resistir la fluencia y soportar la oxidación a temperaturas que superan los 1,000 °C. A medida que los países invierten en generación de energía confiable y flexible para apoyar el crecimiento industrial y la seguridad energética, las plantas de gas son cada vez más favorecidas debido a sus menores emisiones en comparación con el carbón y su capacidad para complementar fuentes de energía renovable. Esto impulsa directamente la demanda de superaleaciones avanzadas utilizadas en componentes de turbinas de alta eficiencia.

Perspectivas del segmento de mercado

Based on Product Form, the Superalloys Market has been segmented into Cast Ingot, Wrought Superalloys, Powder Metallurgy (PM) Superalloys, Others. Wrought superalloys are increasingly in demand due to their superior mechanical properties, fatigue resistance, and dimensional stability, making them essential for high-performance components in aerospace, power generation, and industrial sectors. Unlike cast alloys, wrought superalloys can be processed into complex shapes such as sheets, plates, and forged parts with controlled microstructure, enabling precise engineering of turbine disks, blades, and high-stress structural components. Powder metallurgy superalloys are increasingly adopted in aerospace, defense, and high-performance industrial applications due to their ability to produce components with superior mechanical properties, fine microstructure, and near-net-shape precision. Nickel-based powders are widely used in turbine blades, disks, and hot-section components, where high-temperature strength, creep resistance, and oxidation tolerance are critical. Cobalt-based powders find application in components subjected to extreme wear, corrosion, and thermal cycling, including combustor liners, vanes, and specialized industrial machinery.

By Application: Aerospace (largest market) vs Power Generation (fastest-Growing)

Obtenga información más detallada sobre Superalloys Market

Perspectivas regionales

North America: Expanding dense cluster of aerospace

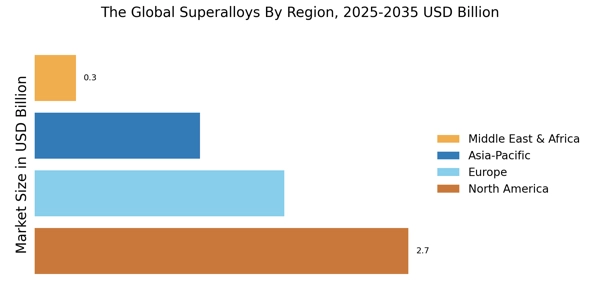
North America dominates by value, accounting for about 45–50% of the superalloys market in 2024–2025, with a market size of roughly USD 3.1–3.2 billion and projected growth to over USD 5 billion by the early 2030s at around 7% CAGR. This leadership stems from a dense cluster of aerospace and defense OEMs (Boeing, Lockheed Martin, GE Aviation) and a strong industrial‑gas‑turbine and power‑generation base. The region is also at the forefront of advanced manufacturing, including additive‑manufactured superalloy components and high‑performance turbine systems.

Europe: Strong Production dense cluster of aerospace

Europe is the second‑largest region, valued at about USD 2.18 billion in 2024 and forecast to reach ~USD 3.7 billion by 2032, growing at roughly 6.8% CAGR. Germany leads within Europe, driven by aerospace, premium automotive, and energy‑sector demand for nickel‑ and cobalt‑based superalloys. European manufacturers emphasize innovation, sustainability, and strict quality standards, which supports steady adoption in engines, turbines, and industrial‑machinery components across the EU.

Asia Pacific: Growing dense cluster of aerospace

Asia‑Pacific (APAC) is the most dynamic region, valued at USD 1.78 billion in 2024 and expected to grow to around USD 3.1 billion by 2032, implying a CAGR of about 7.3%. China is the largest APAC market, followed by India, Japan, and South Korea, where demand is being driven by aerospace‑OEM localization, industrial‑gas‑turbines, power plants, and expanding automotive and turbocharger production. APAC is also becoming a center for indigenous superalloy R&D and capacity expansion, particularly in China and India, supported by government‑backed industrial‑modernization programs.

South America: Protection of dense cluster of aerospace

South America is a small but emerging market in the sonobuoy industry, driven by maritime South America is currently the smallest reported regional segment, but it is expected to grow steadily, piggybacking on aerospace‑maintenance, power‑plant modernization, and automotive‑turbocharger demand, particularly in Brazil and Mexico. While detailed market‑size figures are scarcer, the region benefits from spillover demand from North American and European OEMs, as well as regional industrial‑modernization efforts. Overall, South America remains a niche but increasingly relevant node in the superalloys supply and service network.

Middle East & Africa: Emerging dense cluster of aerospace

Middle East & Africa (MEA) represents a smaller but structurally growing segment, valued at USD 311 million in 2024 and projected to reach around USD 515 million by 2032, with a CAGR near 6.5%. Growth is anchored in oil & gas, power generation, and desalination infrastructure, especially in the Gulf Cooperation Council (GCC) states, where high‑temperature and corrosion‑resistant superalloys are used in turbines, compressors, and offshore equipment. North Africa is also gradually increasing its share as energy‑infrastructure projects expand.

Superalloys Market Regional Image

Jugadores clave y perspectivas competitivas

Muchos proveedores globales, regionales y locales caracterizan el mercado de superaleaciones. El mercado es altamente competitivo, con todos los jugadores compitiendo por ganar cuota de mercado. La intensa competencia, los rápidos avances en materiales, los cambios frecuentes en las políticas gubernamentales y las regulaciones ambientales son factores clave que enfrentan el crecimiento del mercado. Los proveedores compiten en función del costo, la calidad del producto, la fiabilidad y las regulaciones gubernamentales. Los proveedores deben ofrecer productos de alta calidad y costo-efectivos para sobrevivir y tener éxito en un mercado intensamente competitivo.
Los principales actores en el mercado incluyen Precision Castparts Corp, Aubert & Duval, HAYNES INTERNATIONAL, Nippon Yakin Kogyo Co., Ltd, Universal Stainless (Aperam), VDM Metals, Cannon‑Muskegon, CRS Holdings, LLC., thyssenkrupp Materials Trading GmbH, Allegheny Technologies Incorporated (ATI), desarrollos estratégicos del mercado y decisiones para mejorar la efectividad operativa.

Las empresas clave en el mercado Superalloys Market incluyen

Recent Industry Developments

August 2025: EOS expanded its additive manufacturing (AM) material portfolio by introducing nickel-based superalloy powders, EOS IN738 and EOS K500. These materials were integrated into its Laser Beam Powder Bed Fusion (PBF-LB) machines. The EOS Nickel Alloy IN738 and EOS Nickel Alloy K500 became commercially available for the EOS M 290 machine series in December 2024 and are expected to be compatible with the EOS M 400-4 machines in the first half of 2025, enabling advanced applications in high-performance additive manufacturing.

April 2025: Mitsubishi Materials Co., Ltd. launched a new heat-resistant superalloy grade, MV9005, designed for machining nickel-based alloys in the aviation sector. The new grade supports medium finishing processes, where coated inserts provide enhanced tool life, even when only one corner of the insert is used for machining large components.

March 2025: Aubert & Duval’s strategy revolves around material innovation and specialized alloy solutions for aerospace, defense, and energy industries. The company leverages advanced metallurgy capabilities to produce high-strength, high-temperature alloys, targeting clients requiring tailored solutions for extreme conditions. Aubert & Duval enhances its market position through close collaboration with OEMs and engineering partners, enabling customization, rapid prototyping, and just-in-time supply. The company also invests in digitalization and quality management systems to ensure consistent performance and reliability for critical industrial applications.

Perspectivas futuras

Superalloys Market Perspectivas futuras

Se proyecta que el Mercado de Superaleaciones crecerá a una CAGR del 9.3% de 2025 a 2035, impulsado por la creciente demanda de computación de alto rendimiento y características de seguridad mejoradas.

Para 2035, se espera que el mercado logre un crecimiento robusto, consolidando su posición como una industria clave.

Segmentación de mercado

Mercado de Superaleaciones por Aplicación

  • Automotriz
  • Generación de Energía
  • Petróleo y Gas
  • Aeroespacial
  • Otros

Mercado de Superaleaciones por Tipo de Material

  • Basado en Níquel
  • Basado en Hierro
  • Basado en Cobalto

Mercado de Superaleaciones por Perspectiva de Aplicación

  • Aeroespacial y Defensa
  • Energía
  • Turbina de Gas Industrial
  • Automotriz
  • Petróleo y Gas
  • Otros

Alcance del informe

Parameter Detail
Market Scope Global Superalloys Market by base material and end-user industry across five regions and 27 countries
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.69% (2026–2035)
Market Size Checkpoints USD 31.28 Billion (2025); USD 33.37 Billion (2026); USD 43.23 Billion (2030); USD 59.75 Billion (2035)
Fastest Growing Segments Cobalt-based (Base Material); Electronics (End-user Industry); Europe (Region)
Companies Profiled Precision Castparts, Carpenter Technology, ATI, Haynes International, thyssenkrupp, PROTERIAL, Doncasters, Cannon-Muskegon, Aperam, MIDHANI, Aubert & Duval
Valuation Currency USD Billion, end-user value at current prices

Frequently Asked Questions

How should procurement teams structure long-term supply agreements in the Superalloys Market?
Index pricing to LME nickel with a separate conversion-cost escalator, since melt and remelt energy costs move independently of metal. Lock capacity allocation rather than volume, because furnace slots are the binding constraint [13].
What lead times should buyers plan for premium rotating-grade material?
Vacuum arc remelted bar for rotating applications typically runs 40–60 weeks, and large closed-die forgings extend beyond 80 weeks during peak demand. Order coverage below twelve months invites program disruption [21].
Does the Superalloys Market face meaningful antitrust or export-control exposure?
Yes. Several rotating grades fall under ITAR and EU dual-use controls, requiring licensing for cross-border transfer. Buyers sourcing outside their home jurisdiction should validate classification before contracting [14].
How do single-crystal and directionally solidified castings differ commercially?
Single-crystal castings eliminate grain boundaries entirely, permitting roughly 30–50°C higher operating temperature, but yield rates run materially lower. That yield gap, not raw material, drives the price premium [15].
What integration challenges arise when qualifying a second source in the Superalloys Market?
Statistical allowables must be regenerated from the new supplier's own heats, typically demanding thirty or more lots and eighteen to thirty months. Process equivalence, not chemistry match, governs approval [14].
Are recycled-content claims commercially verifiable in this sector?
Aerospace revert is traceable by heat number, so recycled content is auditable in ways scrap-based claims in other metals are not. European buyers increasingly require this documentation under CSRD reporting [20].
Which emerging use case deserves the most attention from Superalloys Market investors?
Small modular reactor components. Intermediate heat exchangers and control-rod hardware require creep-resistant nickel grades qualified to nuclear codes, a small but high-margin channel opening after 2030 [2].
Autor
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory filings, industry technical standards, commodity trade databases, and specialized aerospace & defense publications. Key sources included the US Federal Aviation Administration (FAA) certification databases, European Union Aviation Safety Agency (EASA) type certificates, US Department of Defense (DoD) procurement records & Defense Logistics Agency (DLA) strategic material reports, US Geological Survey (USGS) Mineral Commodity Summaries for nickel, cobalt, and refractory metals, US Department of Energy (DOE) Oak Ridge National Laboratory (ORNL) advanced materials research, National Institute of Standards and Technology (NIST) metallurgical standards, Bureau of Industry and Security (BIS) export control classifications, Aerospace Industries Association (AIA) manufacturing statistics, SAE International (Society of Automotive Engineers) standards databases, ASM International (American Society for Metals) technical journals, International Air Transport Association (IATA) fleet forecasts, Energy Industries Council (EIC) power generation infrastructure data, International Nickel Study Group (INSG) supply statistics, Cobalt Institute production reports, and national aviation authorities from key markets including China's CAAC, Russia's FATA, and Brazil's ANAC.

For nickel-based, cobalt-based, iron-based, and developing refractory metal superalloys, these sources were used to gather production statistics, aerospace order books, defense material specifications, raw material pricing trends, melt shop capacity data, and regulatory clearance procedures.


Primary Research

To gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, vice presidents of metallurgy, chief technology officers, heads of regulatory compliance, and commercial directors from precision casters, integrated superalloy producers, and makers of specialty mill products were examples of supply-side sources. Chief metallurgists from industrial gas turbine manufacturers, supply chain executives from oilfield services firms, maintenance directors from commercial aviation MRO facilities, procurement leads from defense contractors, and chief engineers from aerospace OEMs (airframers and engine manufacturers) were examples of demand-side sources. Primary research verified additive manufacturing qualification timescales, established market segmentation between wrought and cast forms, and obtained information on long-term supply agreements, strategic stockpile dynamics, and raw material hedging tactics.

Primary Respondent Breakdown:

• By Designation: C-level Primaries (32%), Director Level (35%), Others (33%)

• By Region: North America (32%), Europe (28%), Asia-Pacific (32%), Rest of World (8%)


Market Size Estimation

Bill-of-materials (BOM) quantification for end-use applications and capacity utilization analysis were used to determine the global market valuation. The following were part of the methodology:

• More than 35 major manufacturers from North America, Europe, Asia-Pacific, and developing Eastern European specialty alloy producers were identified.

• Product mapping between powder metallurgy superalloy categories, nickel-based (Inconel, Rene, Nimonic series), cobalt-based (Haynes, Stellite alloys), and iron-based (A-286, Incoloy).

• Examination of modeled aerospace alloy allocations from Tier 1 suppliers and reported segment revenues

• Manufacturers that will account for 75–80% of the world's superalloy melt capacity in 2024

• Extrapolation by base metal composition and manufacturing process (wrought, conventionally cast, directionally solidified, single crystal, powder metallurgy) to derive segment-specific valuations using top-down (primary metal producer revenue validation adjusted for value-add processing) and bottom-up (aircraft engine deliveries × alloy content per engine + industrial gas turbine installations × alloy tonnage per turbine) approaches

Descargar muestra gratis

Complete el formulario a continuación para recibir una muestra gratuita de este informe

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















