Mercado de Arena Mineral Resumen
Tendencias clave del mercado y aspectos destacados
Tamaño del mercado y previsión
| CAGR (2025 - 2035) | 4.32% |
| CAGR (2025 - 2035) | 4.32% |
The Mineral Sand Market is currently experiencing a dynamic phase characterized by evolving demand patterns and shifting supply dynamics. This sector, which encompasses various minerals such as zircon, rutile, and ilmenite, plays a crucial role in multiple industries, including construction, electronics, and manufacturing. The increasing emphasis on sustainable practices and the transition towards greener technologies appear to be influencing the market landscape. As industries seek to reduce their environmental footprint, the demand for responsibly sourced mineral sands is likely to rise, prompting suppliers to adapt their operations accordingly. Moreover, geopolitical factors and trade policies are shaping the Mineral Sand Market in complex ways. Countries rich in mineral resources are navigating the challenges of export regulations and tariffs, which could impact global supply chains. The interplay between local production capabilities and international demand suggests that market participants must remain agile and responsive to changes. As the industry evolves, stakeholders may need to invest in innovative extraction and processing technologies to enhance efficiency and sustainability. Overall, the Mineral Sand Market seems poised for continued transformation, driven by both environmental considerations and economic factors.
The focus on sustainability within the Mineral Sand Market is intensifying. Companies are increasingly adopting eco-friendly practices to minimize environmental impact. This trend is likely to drive innovation in extraction and processing methods, as stakeholders seek to align with global sustainability goals.
Technological progress is reshaping the Mineral Sand Market. Enhanced extraction techniques and processing technologies are emerging, potentially improving efficiency and reducing costs. This trend may lead to increased competitiveness among market players, as they leverage new technologies to optimize operations.
Geopolitical factors are playing a significant role in the Mineral Sand Market. Trade policies, tariffs, and international relations can affect supply chains and market dynamics. Stakeholders must navigate these complexities to ensure stable operations and maintain market access.
Infrastructure development projects are significantly influencing the Mineral Sand Market. Governments and private entities are investing heavily in infrastructure, including roads, bridges, and buildings, which require substantial quantities of mineral sands for construction materials. For instance, the demand for zircon and ilmenite, essential components in construction and manufacturing, is expected to rise as new projects are initiated. Recent data indicates that infrastructure spending is projected to increase by 5% annually, further driving the need for mineral sands. This trend suggests that the Mineral Sand Market will likely see a robust growth trajectory as it aligns with the ongoing global push for modernization and urbanization. The interplay between infrastructure development and mineral sand extraction is thus a critical driver of market dynamics.
The mineral sand market is characterized by a diverse range of products, with Ilmenite holding the largest market share among the various types. This black iron-titanium oxide mineral is primarily utilized in the production of titanium dioxide pigment and has a strong foothold in the industrial sector. Meanwhile, Rutile is emerging as the fastest-growing segment due to increasing applications in specialty titanium products and the rising demand in the aerospace and automotive industries. The unique properties of Rutile, including its high purity and low impurities, are appealing to manufacturers looking for higher efficiency in their production processes. Continuous innovations and advancements in extraction and processing techniques for these mineral sands have also led to more efficient production methods, creating opportunities for better yield and profit margins. The overall growth is fueled by increasing global consumer demand for titanium-based products, particularly in emerging economies where urbanization and industrialization are on the rise.
Ilmenite is recognized as the dominant player in the mineral sand market due to its extensive use in the production of titanium dioxide, which is vital for paints, coatings, and plastics. Its robust supply chain and established market presence give it a competitive edge. In contrast, Zircon is an emerging segment, valued for its uniqueness in applications such as ceramics and refractories. Its market position is bolstered by a growing demand for high-quality zircon in the manufacturing of tiles and sanitary ware. Furthermore, the increased awareness of Zircon's properties in producing high-performance materials adds to its attractiveness among manufacturers. As the focus on sustainable materials rises, both Ilmenite and Zircon are likely to play significant roles in the evolving market landscape.
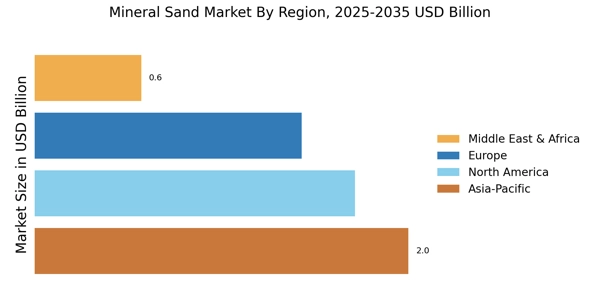
North America is witnessing significant growth in the mineral sand market, driven by increasing demand from the construction and electronics sectors. The region holds approximately 30% of the global market share, with the United States being the largest contributor, followed by Canada. Regulatory support for sustainable mining practices is further catalyzing market expansion, as companies adapt to environmental standards and invest in innovative extraction technologies. The competitive landscape in North America is characterized by key players such as Tronox Holdings and Iluka Resources, which are actively involved in mineral sand production. The presence of advanced mining technologies and a skilled workforce enhances the region's competitive edge. Additionally, the U.S. government's focus on domestic mineral production to reduce reliance on imports is expected to bolster market growth, making North America a pivotal player in the global mineral sand industry.
Europe is emerging as a significant player in the mineral sand market, driven by stringent environmental regulations and a strong emphasis on sustainability. The region accounts for approximately 25% of the global market share, with countries like Germany and the United Kingdom leading the charge. The European Union's Green Deal and various national policies are encouraging investments in eco-friendly mining practices, which are expected to boost demand for mineral sands in the coming years. Leading countries in Europe are actively enhancing their mineral sand production capabilities, with key players such as Kenmare Resources and Rio Tinto making substantial investments. The competitive landscape is marked by a focus on innovation and sustainability, as companies strive to meet regulatory requirements while maximizing efficiency. The region's commitment to reducing carbon footprints and promoting circular economy principles is shaping the future of the mineral sand market in Europe.
The Asia-Pacific region is rapidly becoming a powerhouse in the mineral sand market, driven by robust industrial growth and increasing demand for titanium and zircon. This region holds approximately 35% of the global market share, with Australia being the largest producer, followed by countries like China and India. The growing construction and manufacturing sectors are key demand drivers, supported by favorable government policies aimed at boosting mineral production and exports. Australia's dominance in mineral sand production is complemented by the presence of major players such as Iluka Resources and Base Resources. The competitive landscape is evolving, with new entrants emerging to capitalize on the region's growth potential. Additionally, investments in infrastructure and mining technology are enhancing operational efficiencies, positioning Asia-Pacific as a critical player in The Mineral Sand Market.
The Middle East and Africa region is rich in mineral resources, presenting significant opportunities in the mineral sand market. This region accounts for approximately 10% of the global market share, with South Africa and Mozambique being the leading countries in production. The demand for mineral sands is driven by the growing construction and manufacturing sectors, alongside increasing investments in mining infrastructure and technology, which are expected to enhance production capabilities. Key players in the region include Sierra Rutile Limited and Doral Mineral Sands, which are focusing on expanding their operations to meet rising demand. The competitive landscape is characterized by a mix of established companies and emerging players, all vying for market share. As governments in the region implement policies to attract foreign investment and improve mining regulations, the mineral sand market is poised for growth, making the Middle East and Africa a region to watch.
The Mineral Sand Market is currently characterized by a dynamic competitive landscape, driven by increasing demand for titanium dioxide and zircon, which are essential for various industrial applications. Key players such as Iluka Resources (AU), Tronox Holdings (US), and Rio Tinto (GB) are strategically positioned to leverage their extensive operational capabilities and market reach. Iluka Resources (AU) focuses on sustainable mining practices and has recently expanded its production capacity, indicating a commitment to meeting growing global demand. Tronox Holdings (US) emphasizes innovation in its product offerings, particularly in high-performance titanium dioxide, which enhances its competitive edge. Meanwhile, Rio Tinto (GB) is actively pursuing partnerships to enhance its supply chain resilience, reflecting a broader trend among industry leaders to optimize operations in a fluctuating market.The business tactics employed by these companies reveal a concerted effort to localize manufacturing and optimize supply chains, which is crucial in a moderately fragmented market. The collective influence of these key players shapes the competitive structure, as they navigate challenges such as regulatory compliance and environmental sustainability. This strategic focus on operational efficiency and localized production is likely to enhance their market positions while addressing the growing consumer demand for responsibly sourced materials.
In August Iluka Resources (AU) announced the commissioning of a new processing facility aimed at increasing its zircon production capacity. This strategic move is significant as it not only positions Iluka to meet the rising demand for zircon in the ceramics and electronics industries but also underscores its commitment to sustainable practices by utilizing advanced processing technologies. The facility is expected to enhance operational efficiency and reduce environmental impact, aligning with global sustainability trends.
In September Tronox Holdings (US) unveiled a new product line of eco-friendly titanium dioxide, which is anticipated to capture a growing segment of environmentally conscious consumers. This initiative reflects Tronox's strategic pivot towards sustainability, potentially allowing the company to differentiate itself in a competitive market. By investing in greener technologies, Tronox may enhance its brand reputation and appeal to a broader customer base, thereby solidifying its market position.
In July Rio Tinto (GB) entered into a strategic partnership with a leading technology firm to integrate AI-driven solutions into its mineral extraction processes. This collaboration aims to enhance operational efficiency and reduce costs, indicating a shift towards digital transformation within the industry. The integration of AI technologies could provide Rio Tinto with a competitive advantage by optimizing resource allocation and improving decision-making processes.
As of October the Mineral Sand Market is witnessing trends that emphasize digitalization, sustainability, and technological integration. Strategic alliances among key players are increasingly shaping the competitive landscape, fostering innovation and collaboration. The shift from price-based competition to a focus on technological advancement and supply chain reliability is becoming evident. Companies that prioritize innovation and sustainable practices are likely to emerge as leaders in this evolving market, as they adapt to changing consumer preferences and regulatory landscapes.
Se proyecta que el mercado de arenas minerales crecerá a una Tasa de Crecimiento Anual Compuesto (CAGR) del 4.32% desde 2024 hasta 2035, impulsado por la creciente demanda en los sectores de electrónica, construcción y energía renovable.
Nuevas oportunidades se encuentran en:
Para 2035, se espera que el mercado de arenas minerales consolide su posición como un actor clave en las industrias de recursos globales.
| MARKET SIZE 2024 | 5.802(USD Billion) |
| MARKET SIZE 2025 | 6.052(USD Billion) |
| MARKET SIZE 2035 | 9.24(USD Billion) |
| COMPOUND ANNUAL GROWTH RATE (CAGR) | 4.32% (2025 - 2035) |
| REPORT COVERAGE | Revenue Forecast, Competitive Landscape, Growth Factors, and Trends |
| BASE YEAR | 2024 |
| Market Forecast Period | 2025 - 2035 |
| Historical Data | 2019 - 2024 |
| Market Forecast Units | USD Billion |
| Key Companies Profiled | Iluka Resources (AU), Tronox Holdings (US), Sierra Rutile Limited (GB), Rio Tinto (GB), Kenmare Resources (IE), Base Resources (AU), Doral Mineral Sands (AU), MZI Resources (AU) |
| Segments Covered | Application, Type, Form, End Use Industry, Regional |
| Key Market Opportunities | Growing demand for high-purity mineral sands in advanced manufacturing and renewable energy sectors. |
| Key Market Dynamics | Rising demand for titanium and zircon minerals drives competitive dynamics and supply chain adjustments in the mineral sand market. |
| Countries Covered | North America, Europe, APAC, South America, MEA |
 Chitranshi Jaiswal

Complete el formulario a continuación para recibir una muestra gratuita de este informe

“This is really good guys. Excellent work on a tight deadline. I will continue to use you going forward and recommend you to others. Nice job”
 Noah Malgeri
Co-Founder

“Thanks for sending the report it gives us a good global view of the Betaïne market.”
 Peter Groot koerkamp
Account and Business Manager

“We found the report very insightful! we found your research firm very helpful. I'm sending this email to secure our future business.”
 Younghwan Choi
Senior Retail Manager

“I am very pleased with how market segments have been defined in a relevant way for my purposes (such as "Portable Freezers & refrigerators" and "last-mile"). In general the report is well structured. Thanks very much for your efforts.”
 Mark Irwin
Management Consultant

“We got the report in time, we really thank you for your support in this process. I also thank to all of your team as they did a great job.”
 Akif Moroglu
Strategy & Business Development Director

“The Automotive 48V ECU Components Procurement Intelligence Study” was a complex project, but the Market Research Future (MRFR) team handled it with quality, agility, and customer-centricity. They delivered all requested data on time and within the agreed scope. The team, including Shubhendra Anand and Rahul Gotadki, was always readily available to clarify questions and swiftly implement necessary adjustments, driving the project to a successful conclusion within a very demanding timeframe.
I would also like to specifically commend Akshay Agarwal for his responsiveness and support at every stage—from our initial inquiry on May 6th through to final delivery on June 18th. His dedication made the entire process seamless.”
 Guilherme Gomes Martins
Product Management Director

“Thanks. It’s been a pleasure working with you, please use me as reference with any other Intel employees.”
 Joseph Aguayo
Sales Operations & Pricing Manager

“Thank you, this will be very helpful for OQS.”
 La Terria Dodd
Program Support Specialist

“I have been reading the first document or the study, ,the Global HVAC and FP market report 2021 till 2026. Must say, good info! I have not gone in depth at all parts, but got a good indication of the data inside!”
 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



