Markt für Humangenetik

Marktforschungsbericht zur Humangenetik Informationen nach Anwendung (Wellness & E-Commerce, Präventivmedizin, Diagnostik & Behandlung), nach Test (NIPT, Trägertests, Pharmakogenomische Tests, Karyotypisierung, Thrombophilie-Tests, Septin 9 Biomarker-Tests, NGS, Andere) und nach Region (Nordamerika, Europa, Asien-Pazifik und Rest der Welt) – Marktausblick bis 2035
ID: MRFR/LS/0243-CR 169 Pages Nidhi Mandole, Kinjoll Dey Last Updated: September 27, 2026
Human Genetics Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)10.8%
2024 Market Size$ 31.79 Billion
2025 Market Size$ 35.22 Billion
2035 Market Size$ 98.24 Billion
Key Players
Illumina
Thermo Fisher Scientific
Roche
Abbott Laboratories
PerkinElmer
Agilent Technologies
Opportunities
  • Market Growth Projections
  • Government Initiatives and Funding
  • Increasing Awareness and Education

Markt für Humangenetik Zusammenfassung

Wichtige Markttrends & Highlights

Marktgröße & Prognose

CAGR (2025 - 2035) 10.8%

Hauptakteure

Illumina(US), Thermo Fisher Scientific (US), Roche(CH), Abbott Laboratories (US), PerkinElmer (US), Agilent Technologies (US), BGI Genomics (CN), Myriad Genetics (US), Genomatix (DE)

Markt für Humangenetik Treiber

Market Growth Projections

The Human Genetics Market is poised for substantial growth, with projections indicating a market value of 31.8 USD Billion in 2024 and an anticipated rise to 98.2 USD Billion by 2035. This growth trajectory reflects a compound annual growth rate of 10.8% from 2025 to 2035. 
 
The expansion is driven by various factors, including advancements in genetic testing technologies, increasing prevalence of genetic disorders, and the growing demand for personalized medicine. As the industry evolves, it is likely to attract further investments and innovations, solidifying its position as a critical component of modern healthcare.

Government Initiatives and Funding

Government initiatives and funding play a crucial role in propelling the Human Genetics Market forward. Various countries are investing in genetic research and healthcare infrastructure to enhance disease prevention and treatment strategies. 
 
For instance, the National Institutes of Health in the United States allocates substantial resources for genomic research, fostering innovation in genetic therapies. Such governmental support not only accelerates research but also encourages public-private partnerships, leading to the development of novel genetic solutions. This supportive environment is likely to contribute to the market's growth trajectory, with projections indicating a rise from 31.8 USD Billion in 2024 to 98.2 USD Billion by 2035.

Increasing Awareness and Education

The rising awareness and education regarding genetic health are vital drivers in the Global Human Genetics Market. Public health campaigns and educational programs are informing individuals about the importance of genetic testing and its implications for health management. This heightened awareness is leading to increased demand for genetic services, as individuals seek proactive measures for disease prevention. 
 
Moreover, healthcare professionals are becoming more knowledgeable about genetic testing options, further driving adoption rates. As awareness continues to grow, the market is expected to expand significantly, with a valuation of 31.8 USD Billion in 2024 and a projected increase to 98.2 USD Billion by 2035.

Rising Prevalence of Genetic Disorders

The increasing incidence of genetic disorders globally drives the Global Human Genetics Market. Conditions such as cystic fibrosis, sickle cell anemia, and various hereditary cancers are becoming more prevalent, necessitating advanced genetic testing and therapies. 
 
For instance, the World Health Organization reports that genetic disorders affect approximately 1 in 160 children globally. This growing demand for genetic diagnostics and personalized medicine is projected to contribute significantly to the market, with an estimated value of 31.8 USD Billion in 2024, and a forecasted growth to 98.2 USD Billion by 2035, reflecting a compound annual growth rate of 10.8% from 2025 to 2035.

Growing Demand for Personalized Medicine

The shift towards personalized medicine is a pivotal driver in the Human Genetics Market. Patients increasingly seek treatments tailored to their genetic profiles, enhancing therapeutic efficacy and minimizing adverse effects. This trend is evident in oncology, where targeted therapies based on genetic mutations have shown improved outcomes. 
 
The market's expansion is further supported by the increasing awareness of genetic testing among healthcare providers and patients. As a result, the market is projected to grow significantly, with a valuation of 31.8 USD Billion in 2024 and an expected rise to 98.2 USD Billion by 2035, indicating a robust CAGR of 10.8% from 2025 to 2035.

Advancements in Genetic Testing Technologies

Technological innovations in genetic testing are revolutionizing the market. The development of next-generation sequencing and CRISPR gene-editing technologies has enhanced the accuracy and efficiency of genetic analyses. These advancements allow for comprehensive genomic profiling, enabling early detection of diseases and tailored treatment plans. 
 
For example, companies are now offering whole-genome sequencing at reduced costs, making it accessible to a broader population. As these technologies continue to evolve, they are expected to drive market growth, contributing to the anticipated increase in market value from 31.8 USD Billion in 2024 to 98.2 USD Billion by 2035.

Regionale Einblicke

North America : Market Leader in Innovation

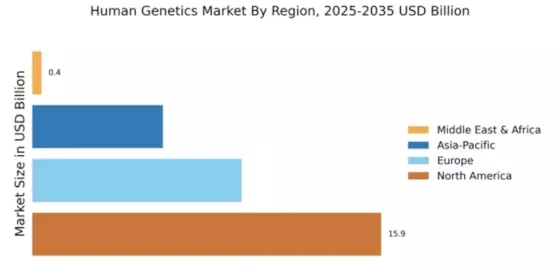
North America is poised to maintain its leadership in the Human Genetics Market, holding a significant market share of 15.89 in 2024. The region's growth is driven by advanced research facilities, high healthcare expenditure, and a robust regulatory framework that encourages innovation. Increasing demand for genetic testing and personalized medicine further propels market expansion, supported by government initiatives promoting genomics research.

The competitive landscape in North America is characterized by the presence of key players such as Illumina, Thermo Fisher Scientific, and Abbott Laboratories. These companies are at the forefront of technological advancements, offering a wide range of genetic testing solutions. The U.S. and Canada are leading countries, with substantial investments in R&D and collaborations between public and private sectors, ensuring a dynamic market environment.

Europe : Emerging Market with Growth Potential

Europe's Human Genetics Market is poised for growth, with a market size of 9.53 in 2024. The region benefits from a strong emphasis on research and development, supported by EU funding and initiatives aimed at advancing genetic research. Europe's mrket is poised for growth, with strong contributions from countries such as Germany, making the Germany market a key regional driver. Regulatory frameworks like GDPR support ethical genetic practices.

Regulatory frameworks, such as the General Data Protection Regulation (GDPR), ensure ethical standards in genetic testing, fostering consumer trust and market demand. Leading countries in Europe include Germany, the UK, and France, where significant investments in biotechnology and healthcare infrastructure are evident. Key players like QIAGEN and Roche are actively involved in expanding their product offerings. The competitive landscape is evolving, with a focus on collaboration between academic institutions and industry, enhancing innovation in genetic testing and therapies.

Asia-Pacific : Rapidly Growing Market Segment

The Asia-Pacific region is witnessing rapid growth in the market, with a market size of 5.95 in 2024. Factors such as increasing healthcare expenditure, rising awareness of genetic disorders, and advancements in technology are driving demand. Governments are implementing supportive policies to enhance research capabilities and access to genetic testing, contributing to market expansion.

Countries like China and Japan are leading the charge, with significant investments in biotechnology and healthcare infrastructure. Countries like China are leading this expansion, positioning the China market as a major contributor to global growth. The presence of companies like BGI Genomics and Genomatix highlights the competitive landscape. Collaborations between public and private sectors are fostering innovation, positioning Asia-Pacific as a key player in the global human genetics arena.

Middle East and Africa : Emerging Market with Challenges

The Middle East and Africa (MEA) region, with a market size of 0.42 in 2024, presents unique challenges and opportunities in the market. Limited access to advanced healthcare services and genetic testing facilities hampers growth. However, increasing awareness of genetic disorders and government initiatives to improve healthcare infrastructure are driving demand for genetic solutions.

Countries like South Africa and the UAE are making strides in genetic research and testing, supported by investments from both public and private sectors. Increasing investments and awareness are contributing to the development of the market GCC, particularly in countries like the UAE. The competitive landscape is gradually evolving, with local and international players seeking to establish a foothold in the region. Collaborative efforts are essential to overcome existing barriers and unlock the market's potential.

Markt für Humangenetik Regional Image

Hauptakteure und Wettbewerbseinblicke

The Human Genetics Market is characterized by a dynamic competitive landscape, driven by advancements in genomic technologies and increasing demand for personalized medicine. Key players such as Illumina (US), Thermo Fisher Scientific (US), and Roche (CH) are at the forefront, leveraging innovation and strategic partnerships to enhance their market positions. Illumina (US) focuses on expanding its sequencing capabilities, while Thermo Fisher Scientific (US) emphasizes its comprehensive portfolio of genetic analysis tools.
 
Roche (CH) is actively pursuing collaborations to integrate diagnostics with therapeutic solutions, thereby shaping a competitive environment that prioritizes technological advancement and customer-centric solutions. In terms of business tactics, companies are increasingly localizing manufacturing and optimizing supply chains to enhance operational efficiency. The market appears moderately fragmented, with a mix of established players and emerging companies vying for market share. The collective influence of these key players fosters a competitive structure that encourages innovation and responsiveness to market demands, ultimately benefiting end-users through improved product offerings and services.
 
In November 2025, Illumina (US) announced a strategic partnership with a leading healthcare provider to enhance genomic testing accessibility. This collaboration aims to streamline the integration of genomic data into clinical workflows, potentially revolutionizing patient care by enabling more personalized treatment plans. The strategic importance of this partnership lies in its potential to expand Illumina's reach and solidify its position as a leader in the genomic testing space.
 
In October 2025, Thermo Fisher Scientific (US) launched a new line of next-generation sequencing (NGS) products designed to improve throughput and reduce costs for laboratories. This product launch is significant as it addresses the growing demand for efficient and cost-effective genetic analysis solutions, positioning Thermo Fisher as a key player in the competitive landscape. The introduction of these products may enhance customer loyalty and attract new clients seeking advanced genomic technologies.
 
In September 2025, Roche (CH) acquired a biotechnology firm specializing in CRISPR technology, aiming to bolster its research and development capabilities in gene editing. This acquisition is strategically important as it aligns with Roche's commitment to advancing precision medicine and expanding its therapeutic offerings. By integrating CRISPR technology, Roche could potentially accelerate the development of innovative treatments, thereby enhancing its competitive edge in the market.
 
As of December 2025, current trends in the market include a pronounced shift towards digitalization, sustainability, and the integration of artificial intelligence (AI) in genetic research and diagnostics. Strategic alliances are increasingly shaping the competitive landscape, fostering collaboration that enhances innovation and accelerates product development. Looking ahead, competitive differentiation is likely to evolve, with a greater emphasis on technological innovation and supply chain reliability, moving away from traditional price-based competition. Companies that successfully navigate these trends will likely emerge as leaders in the market.

Zu den wichtigsten Unternehmen im Markt für Humangenetik-Markt gehören

Recent Industry Developments

January 2026, Thermo Fisher introduced the SwiftArrayStudio microarray analyzer, designed for fast and scalable sample analysis — extending its Applied Biosystems genomic array portfolio (used for SNP genotyping, disease-risk research, and population-scale genetic studies) with improved throughput. (Source: captodayonline.com)

June 2026, Roche received CE Mark approval for its Elecsys ApoE4 biomarker blood test — the first IVD immunoassay to identify carriers of the ApoE4 Alzheimer's genetic risk variant from a blood draw — and filed with Japan's regulators for its companion Elecsys pTau217 plasma test, directly expanding accessible genetic/biomarker risk testing for a disease affecting millions. (Source: diagnostics.roche.com)

Zukunftsaussichten

Markt für Humangenetik Zukunftsaussichten

Der Markt für Humangenetik wird voraussichtlich von 2025 bis 2035 mit einer CAGR von 10,8% wachsen, angetrieben durch Fortschritte in der Genomtechnologie, personalisierte Medizin und die steigende Nachfrage nach genetischen Tests.

Neue Möglichkeiten liegen in:

  • Entwickeln Sie KI-gesteuerte genetische Analysetools zur Verbesserung der diagnostischen Genauigkeit. Erweitern Sie Telemedizin-Dienste für genetische Beratung, um unterversorgte Bevölkerungsgruppen zu erreichen. Investieren Sie in Partnerschaften mit Biotech-Unternehmen, um innovative Gentherapien zu entwickeln.

Bis 2035 wird der Markt für Humangenetik voraussichtlich ein entscheidender Sektor in der Gesundheitsinnovation sein.

Marktsegmentierung

Markt für Humangenetik - Ausblick nach Endbenutzer

  • Krankenhäuser
  • Forschungslabore
  • Pharmaunternehmen
  • Diagnoselabore
  • Akademische Einrichtungen

Markt für Humangenetik - Ausblick nach Technologie

  • Next-Generation-Sequenzierung
  • Polymerase-Kettenreaktion
  • Mikroarray
  • CRISPR
  • Sanger-Sequenzierung

Markt für Humangenetik - Ausblick nach Anwendung

  • Genetische Tests
  • Gentherapie
  • Pharmakogenomik
  • Genetische Forschung
  • Personalisierte Medizin

Berichtsumfang

MARKET SIZE 2024 31.79(USD Billion)
MARKET SIZE 2025 35.22(USD Billion)
MARKET SIZE 2035 98.24(USD Billion)
COMPOUND ANNUAL GROWTH RATE (CAGR) 10.8% (2025 - 2035)
REPORT COVERAGE Revenue Forecast, Competitive Landscape, Growth Factors, and Trends
BASE YEAR 2024
Market Forecast Period 2025 - 2035
Historical Data 2019 - 2024
Market Forecast Units USD Billion
Key Companies Profiled Illumina (US), Thermo Fisher Scientific (US), Roche (CH), Abbott Laboratories (US), PerkinElmer (US), Agilent Technologies (US), BGI Genomics (CN), Myriad Genetics (US), Genomatix (DE)
Segments Covered Application, Technology, End User
Key Market Opportunities Advancements in gene editing technologies create transformative opportunities in the market.
Key Market Dynamics Rising demand for personalized medicine drives innovation and competition in the market.
Countries Covered North America, Europe, APAC, South America, MEA

Frequently Asked Questions

Was ist die aktuelle Bewertung des Marktes für Humangenetik im Jahr 2024?

Der Markt für Humangenetik wurde im Jahr 2024 mit 31,79 Milliarden USD bewertet.

Was ist die prognostizierte Marktbewertung für den Markt für Humangenetik im Jahr 2035?

Der Markt wird voraussichtlich bis 2035 98,24 Milliarden USD erreichen.

Was ist die erwartete CAGR für den Markt für Humangenetik im Prognosezeitraum 2025 - 2035?

Die erwartete CAGR für den Markt für Humangenetik im Zeitraum 2025 - 2035 beträgt 10,8%.

Welche Anwendungssegmente treiben das Wachstum im Markt für Humangenetik voran?

Wichtige Anwendungssegmente sind Krankheitsdiagnose, Arzneimittelentwicklung, genetische Tests und personalisierte Medizin, wobei erwartet wird, dass die genetischen Tests von 10,0 auf 30,0 Milliarden USD wachsen.

Wie tragen Gesundheitsdienstleister zum Markt für Humangenetik bei?

Es wird erwartet, dass die Gesundheitsdienstleister von 10,0 auf 31,0 Milliarden USD wachsen, was ihre bedeutende Rolle im Markt anzeigt.

Welche Technologien beeinflussen den Markt für Humangenetik?

Technologien wie Next Generation Sequencing und Polymerase-Kettenreaktion sind entscheidend, wobei erwartet wird, dass das Next Generation Sequencing von 10,0 auf 32,0 Milliarden USD wächst.

Welche Arten von Dienstleistungen werden im Markt für Humangenetik angeboten?
Der Markt umfasst Laborservices, Beratungsdienste und Datenanalysedienste, wobei erwartet wird, dass die Laborservices von 12,5 auf 39,0 Milliarden USD steigen.
Welche Probenarten werden im Markt für Humangenetik verwendet?
Probenarten umfassen Blutproben, Speichelproben, Gewebeproben und Zelllinien, wobei erwartet wird, dass Blutproben von 10,0 auf 30,0 Milliarden USD wachsen.
Wer sind die wichtigsten Akteure im Markt für Humangenetik?
Wichtige Akteure sind Illumina, Thermo Fisher Scientific, Roche, Agilent Technologies und Myriad Genetics, unter anderem.
Was ist die Bedeutung von genetischen Tests im Markt für Humangenetik?
Genetische Tests werden voraussichtlich erheblich wachsen, was ihre entscheidende Rolle bei der Förderung personalisierter Medizin und Krankheitsdiagnose anzeigt.
Autor
Author Author Profile Nidhi Mandole LinkedIn Senior Research Analyst
She is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Nidhi is comfortably versed in data centric research backed by healthcare educational background. She leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. Her key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, she showcases extensive affinity towards learning new skills and remain fascinated in implementing them.
Co-Author Co-Author Profile Kinjoll Dey LinkedIn Senior Research Analyst
He is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Kinjoll is comfortably versed in data centric research backed by healthcare educational background. He leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. His key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, he showcases extensive affinity towards learning new skills and remain fascinated in implementing them.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of genomic databases, regulatory filings, peer-reviewed genetic research journals, and authoritative public health repositories. Key sources included the US Food & Drug Administration (FDA) Center for Devices and Radiological Health (CDRH), European Medicines Agency (EMA), National Institutes of Health (NIH) National Human Genome Research Institute (NHGRI), National Center for Biotechnology Information (NCBI) GenBank & ClinVar databases, Centers for Medicare & Medicaid Services (CMS), Centers for Disease Control and Prevention (CDC) Office of Genomics and Precision Public Health, World Health Organization (WHO) Human Genomics Programme, European Molecular Biology Laboratory-European Bioinformatics Institute (EMBL-EBI), Online Mendelian Inheritance in Man (OMIM), American College of Medical Genetics and Genomics (ACMG), European Society of Human Genetics (ESHG), International Society for Pharmacogenomics (ISP), UK National Health Service (NHS) Genomic Medicine Service, EU European Health Data and Evidence Network (EHDEN), Organisation for Economic Co-operation and Development (OECD) Health Statistics, and national genomic medicine strategies from key markets. These sources were utilized to collect genetic testing volume statistics, regulatory approval data for NGS-based assays, clinical utility studies, genomic biomarker validation data, reimbursement frameworks, and population-scale genomic screening program metrics across hereditary cancer testing, prenatal screening (NIPT), pharmacogenomic testing, and rare disease diagnostic categories.


Primary Research

Supply-side and demand-side stakeholders were interviewed during the primary research process to acquire qualitative and quantitative insights from various perspectives within the human genetics value chain. Chief Executive Officers, Chief Scientific Officers, Vice Presidents of Genomic Research and Development, Heads of Regulatory Affairs for In Vitro Diagnostics (IVD), and commercial directors from molecular diagnostics OEMs, genetic testing laboratories, bioinformatics solution providers, and NGS platform manufacturers comprised the supply-side sources. Board-certified medical geneticists, molecular pathologists, laboratory directors from hospital-based and reference laboratories, genetic counselors, precision medicine program directors from academic medical centers, and procurement leads from integrated health networks and research institutions comprised demand-side sources. Primary research has validated market segmentation across test modalities, confirmed CLIA-certification and CAP-accreditation timelines for new laboratory-developed tests (LDTs), gathered insights on clinical adoption patterns for whole-genome versus targeted gene panels, pricing dynamics for direct-to-consumer genetic testing versus clinical-grade testing, and developed reimbursement navigation strategies for preventive genomic screening.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (35%), Others (33%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and genetic testing procedure volume analysis across diagnostic, preventive, and wellness application segments. The methodology included:

The identification of over 50 significant manufacturers and service providers in North America, Europe, Asia-Pacific, and Latin America, including molecular diagnostic companies (Myriad Genetics, Labcorp), NGS platform vendors (Illumina, Thermo Fisher Scientific), and bioinformatics providers

Product mapping across NIPT, carrier screening, pharmacogenomic testing, karyotype analysis, thrombophilia testing, Septin 9 biomarker testing, and comprehensive NGS-based applications

Analysis of reported and modeled annual revenues specific to human genetics portfolios, including instrument sales, consumables, and testing services revenue

Coverage of manufacturers and service providers representing 70-75% of global market share in 2024

Extrapolation using bottom-up (test volume × average selling price by country/region, segmented by test type and clinical indication) and top-down (manufacturer revenue validation and bioinformatics services quantification) approaches to derive segment-specific valuations for diagnostic & treatment, preventive medicine, and wellness & e-commerce applications

Cross-validation against national genomic medicine spending data, insurance claims databases for genetic testing procedures, and direct-to-consumer genetic testing market tracking

Kostenloses Muster herunterladen

Bitte füllen Sie das folgende Formular aus, um ein kostenloses Muster dieses Berichts zu erhalten

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.